Buy 1 barrel of oil for $100, get one barrel free!That makes $50 a barrel. Looks like a sale. Hurry before it ends. Spare a thought for the poor oil industry losing $ 4.5 billion every day in this special promotion. That would make $ 1.6 trillion in a year. And think of the oil price the oil industry would need in order to recover these losses. So put your petrol savings under the mattress now, you will need it later. And, by the way, what would you do if your salary were cut by 50%? How long would you survive this?
(1) The road to recovery
The question everyone asks: when will oil prices go up again? And how fast? Will they follow the path of recovery we saw in 2009, when QE1 was started? 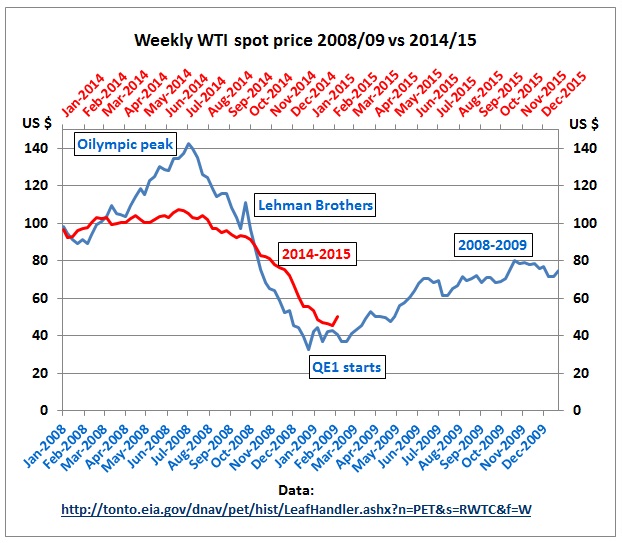
Fig 1: Two different oil price drops
What will happen if oil prices stay lower for some time?
(2) Investment drought
The IEA’s World Energy Investment Outlook published 3rd June 2014 – before the oil price drop – calculated investments for fossil fuel supplies including oil: 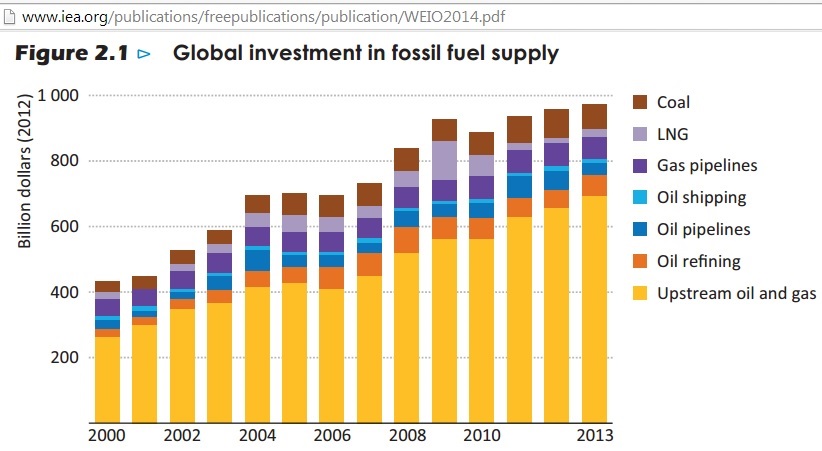
Fig 2: CAPEX assigned in year of 1st production (p 52)
Let’s compare upstream oil and gas from Fig 2 with actual oil production:
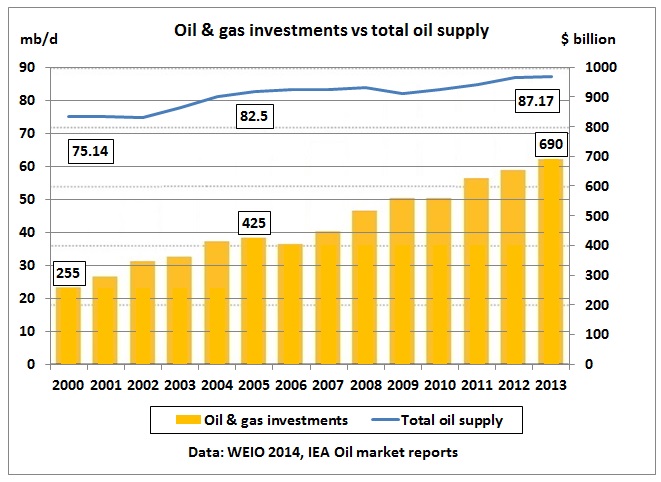
Fig 3: Comparison Oil & gas investments with actual oil production
We see that total oil supply (including gas plant liquids but excluding bio-fuels and refinery processing gains) has not increased commensurate with investments. While investments since 2005 increased at an average of 8% pa, production went up by less than 1% pa Oil alone needs $500 bn investments pa, 90% of which [=$ 450 bn] is required to keep oil production at current levels. (p 60 WEIO). At the Davos World Economic Forum in January 2015, Fatih Birol, Chief Economist of the IEA warned: “In 2015 we expect oil and gas upstream investments to decline $ 100 bn or 15%. [100 bn out of 700 bn] And the big chunk of it will come from the high cost areas. And this will have implications, not perhaps immediately but for 2016-2017. And if this comes together with a stronger demand this will have strong implications for the price and the markets” http://www.weforum.org/sessions/summary/geo-economics-energy
Out of this $ 100 bn, appr. $ 70 bn would be for oil, thus reducing $ 500 bn to $ 430 bn. So this is lower than the amount needed just to keep production flat. 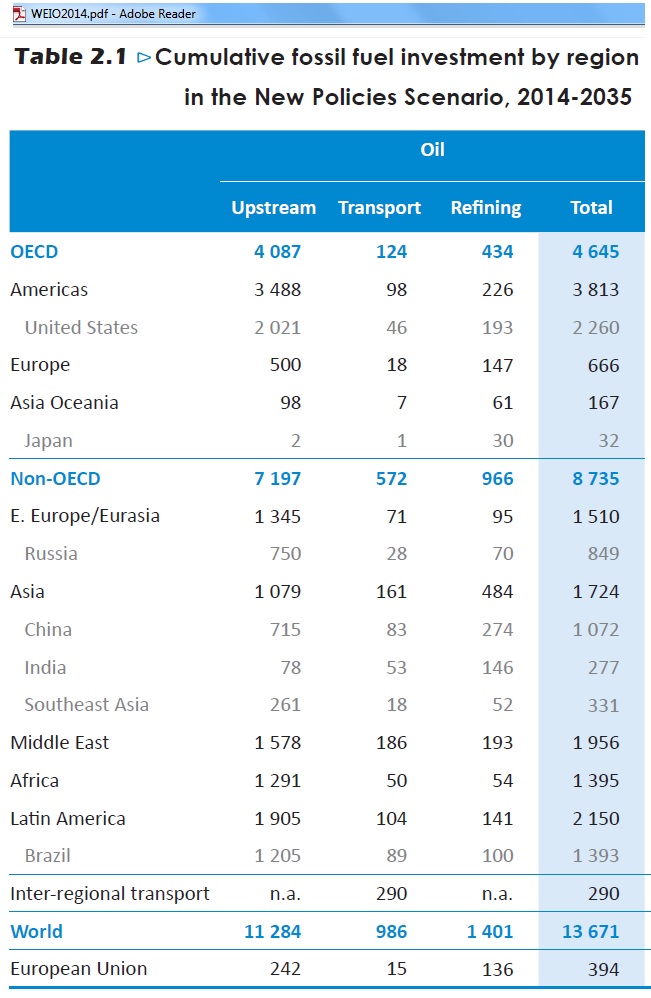
Fig 4: Investments in oil (extract from table 2.1 WEIO 2014)
This table is important because in future we are going to get many media reports on oil and gas investments (or lack thereof) in different countries so we can relate these to the numbers in Fig 4. Note the IEA assumes that future investments in upstream oil will only increase by 0.25% pa, resulting in US$ 11.28 trillion by 2035. This seems to be on the low side. Nevertheless, the IEA thinks following production can be achieved with these investments: 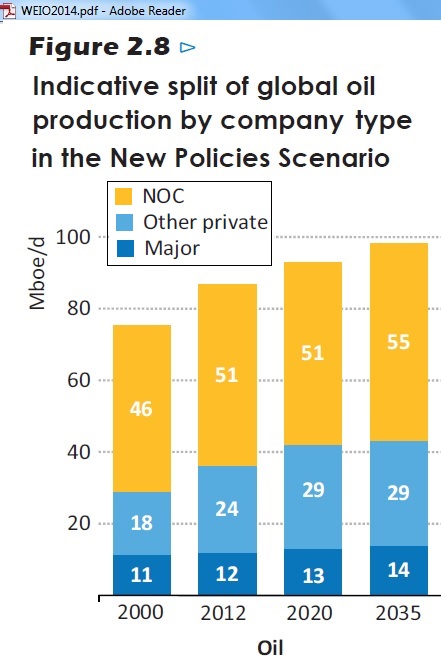
Fig 5: Assumed oil production (total 756 Gb between 2014-2035)
Growth rates in Fig 5 are appr. 0.9% between 2014 and 2020 and 0.4% between 2020 and 2035. 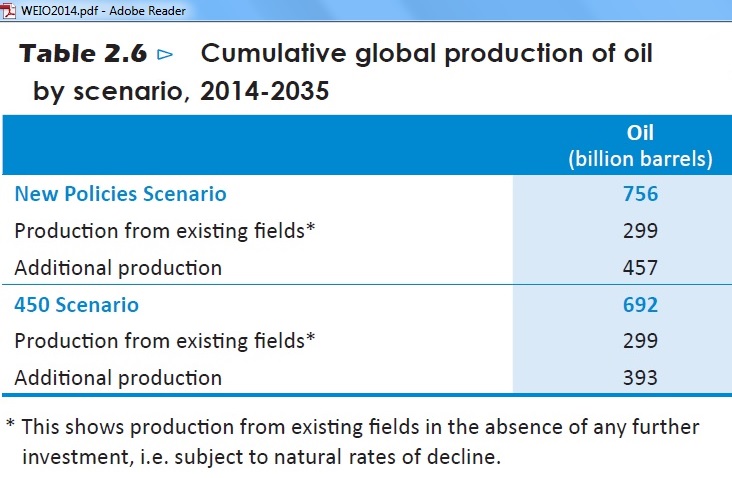
Fig 6: Cumulative total oil production vs production from existing fields
Note that cumulative production without investments will only be around 40%. The assumed oil price is $128 by 2035 in real terms (p. 51) In order to understand how oil production drops in existing fields the following graph uses data from the IEA’s World Energy Outlook published a couple of months later in November 2014: 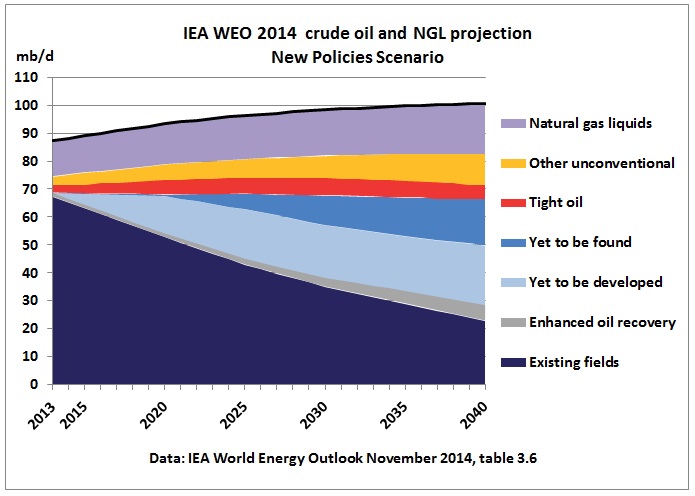
Fig 7: Oil production forecast in the WEO 2014
So the main “battlefield” will be conventional oil fields: 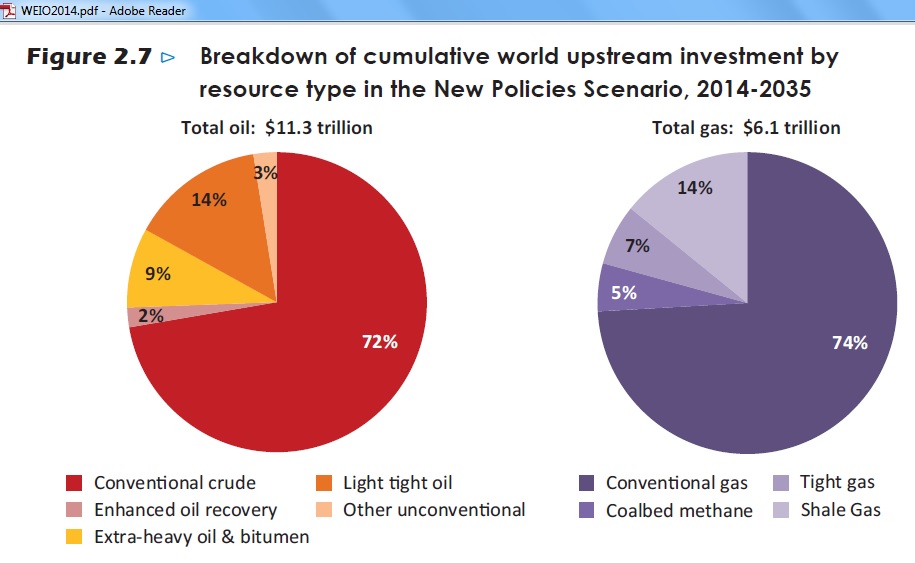
Fig 8: 72% of investments will be in conventional oil
(3) The US tight oil peak
The icing on the current cake is still US tight oil. The following graph is from the EIA oil and gas outlook Nov 2014 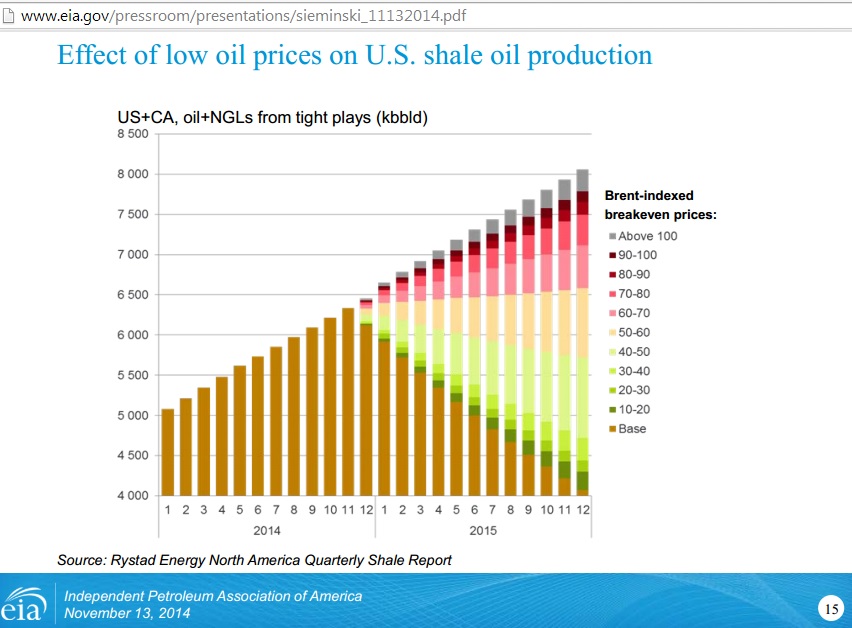
Fig 9: Impact of low oil prices on US tight oil production
http://www.eia.gov/pressroom/presentations/sieminski_11132014.pdf
What you pay is what you get. Select an oil price and see where production goes. The lower the oil price, the earlier the US tight oil peak.
(4) Call to oil prayer
For many years, the international Energy Agency’s projections have followed this methodology:
(a) Assume (or wish for) a certain global GDP growth in % pa
(b) Calculate resulting oil demand
(c) Assess future Non-OPEC supply
(d) Call on OPEC = difference of (b) and (c) 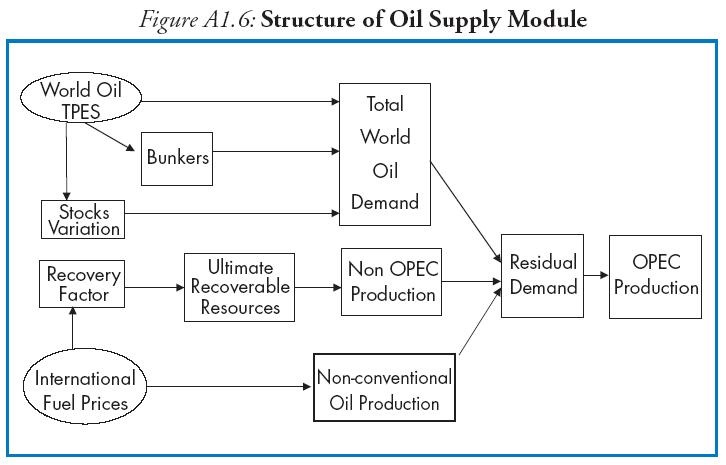
Fig 10: IEA’s oil supply model in WEO 2000
Many think that this model is now outdated. This is a premature view. Have a look at this graph from the WEO 2014 presentation to the press: 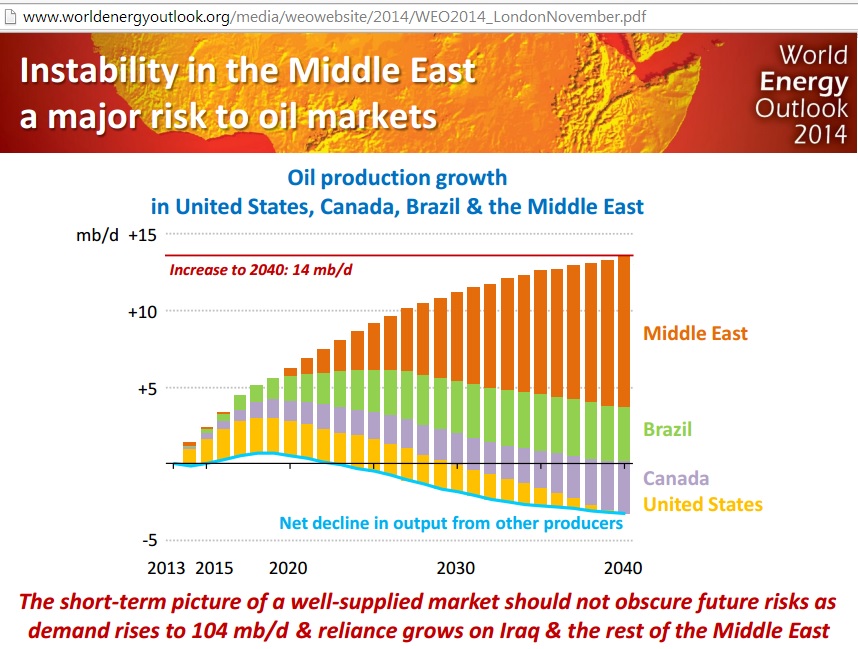
Fig 11: Slide 5
http://www.worldenergyoutlook.org/media/weowebsite/2014/WEO2014_LondonNovember.pdf
After the US peak, the world will rely on Brazil’s expensive sub-salt oil and the Middle East.
Conclusion:
The longer oil prices stay low, the earlier the US tight oil peak. Then pray that eternal peace starts in the Middle East. And elsewhere, too.
PS Oh, and don’t forget that there is yet another deadline approaching end March 2015. Will that be the end of negotiations on 200,000 centrifuges Iran wants to install? A couple of months later we have the hurricane season 2015 along the coast of the Gulf of Mexico where a lot of the tight oil is now processed in refineries. And bankers have to expect some Subprime oil