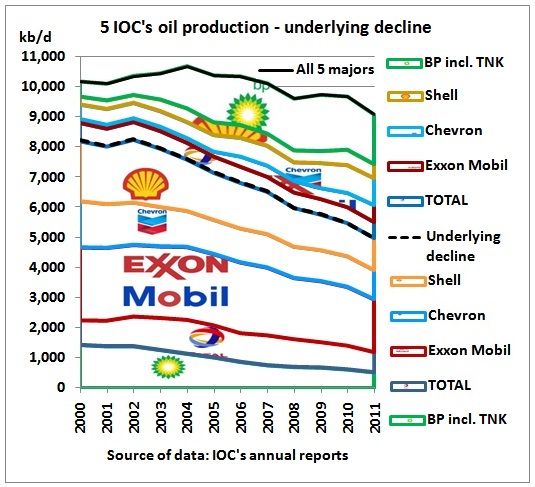
Oil production (crude and NGLs) of 5 international oil companies has been declining by a total of 15% over the period 2004-2011.
Merci, Jean (Lahererre, ASPO France) pour m’avoir envoyé quelques graphes sur le déclin du production des compagnies pétrolières internationales. Ça m’a donné l’ideee de faire d’autres graphes plus détaillés.
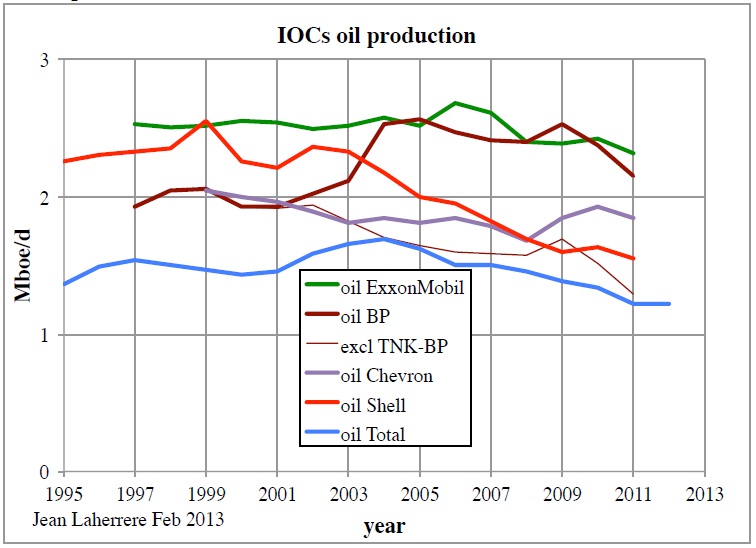 We stack the above curves and find a decline rate of 2.1 % between a peak in 2004 and 2011.
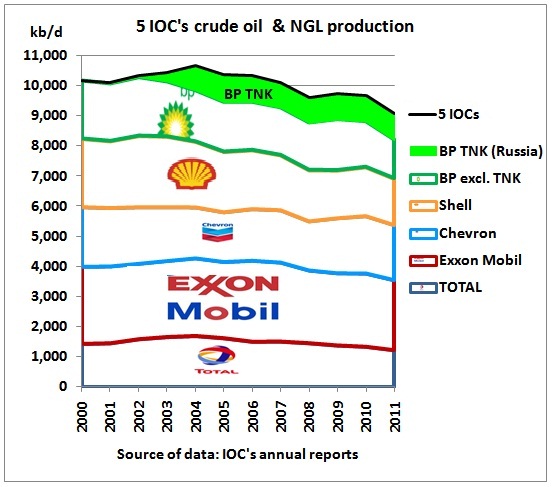 The peak in 2004 was created by BP acquiring 50% of the Russian oil assets of Tymen Oil Company (TNK), Onako and Sidanco in 2003. This asset is being sold again, to pay for damages of the Deepwater Horizon oil spill.
BP Earnings Fall on Lower Production and Higher Costs
5/2/2013
The company began an extensive restructuring after the April 2010 explosion on the Deepwater Horizon rig in the Gulf of Mexico that killed 11 people and unleashed a huge oil spill. Among the asset sales announced, BP agreed Oct. 22 to sell its 50 percent stake in a Russian joint venture, TNK-BP, to the state-controlled Rosneft for about $27 billion in cash and stock.
http://www.nytimes.com/2013/02/06/business/global/bp-earnings-fall-on-lower-production-and-higher-costs.html?_r=0
EU Commission Clears Acquisition of TNK-BP by Rosneft
8/3/2013
http://www.eurasiareview.com/08032013-eu-commission-clears-acquisition-of-tnk-bp-by-rosneft/
Without BP-TNK, the peak of all 5 IOCs was in 1999 and the over-all decline rate since then 1.9 % pa
So let’s have a look at BP first:
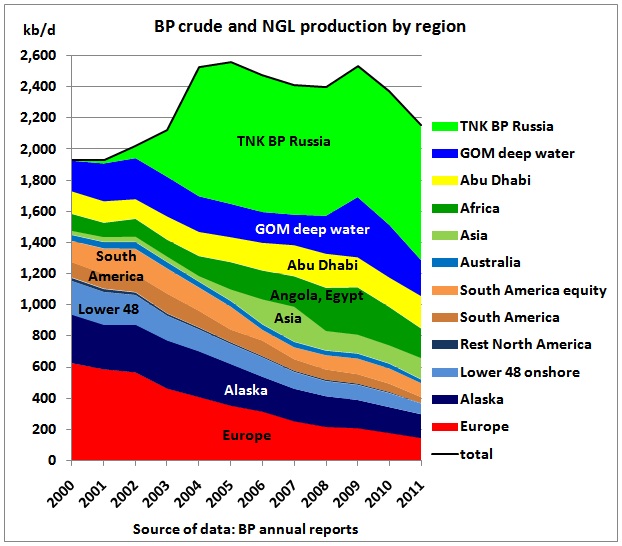 BP’s overall decline rate between 2000 and 2011 without BP-TNK was 3% pa. The underlying decline rate of the declining group (Europe, Alaska, US lower 48, South America and Australia) was a whopping 5.8 %.
So will BP now produce enough oil for their refineries?
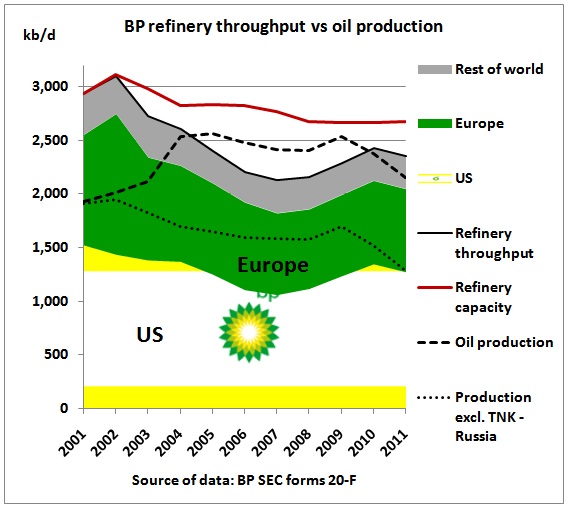 This graph shows a comparison of BP’s oil production with the capacity and throughput of BP’s refineries. The sale of BP-TNK means that, on a net-basis, BP needs to buy expensive crude oil and other feedstock on the global market in order to keep their refineries going.
All data for the above graphs can be found here (BP annual reports):
http://www.bp.com/extendedsectiongenericarticle.do?categoryId=9039692&contentId=7072683
In his paper on IOCs, Jean also makes the point that production forecasts of international oil companies have been consistently on the high side as shown on this graph:
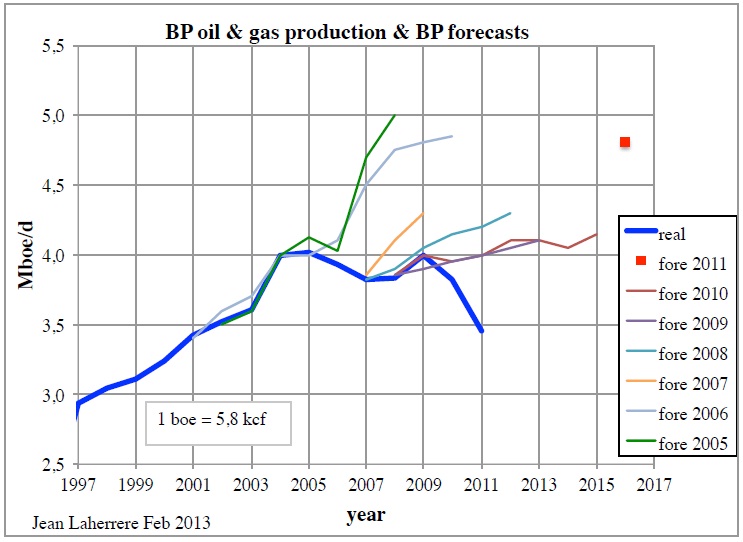 Jean’s production curve includes gas which has been converted to barrels of oil equivalent.
Let’s have a look at the French oil major TOTAL:
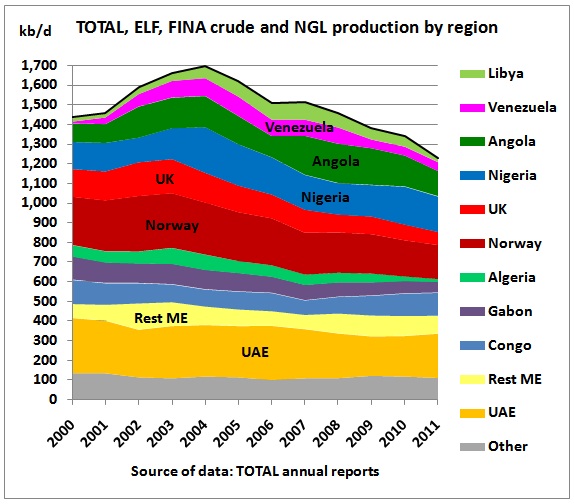 Total’s oil production peaked in 2004 and declined since then by 4% pa. The underlying decline rate (declining areas) was also a steep 5.7 % pa.
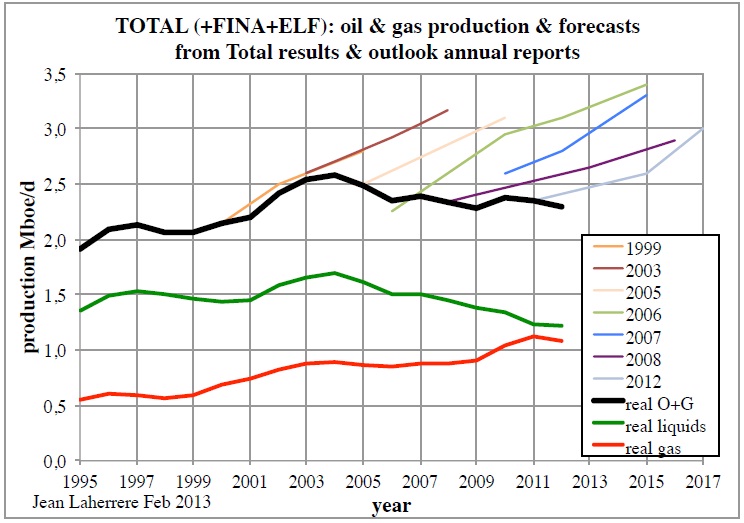 This graph from Jean shows declining oil production for TOTAL since 2004 and growing gas production (measured in equivalent oil barrels). In energy terms, the growth in gas could not offset the decline in oil. All oil and gas forecasts have been too high compared with actual production. Upward curves for the future attract investors and keep shareholders happy.
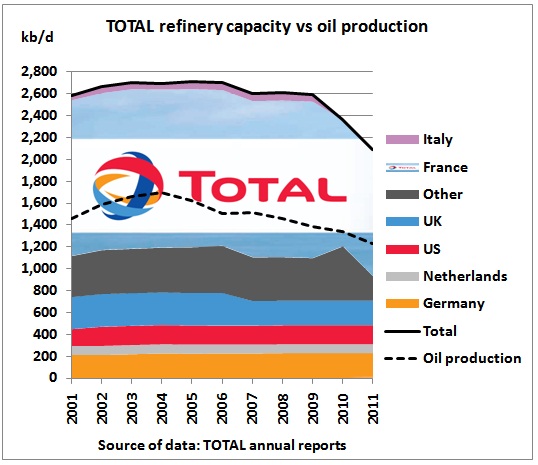 TOTAL seems to adjust their refinery capacity (colored areas) to peaking oil production (dashed line). Their own oil is sufficient for only around 58% of their refinery capacity.
All TOTAL data are from here:
http://www.total.com/en/investors/regulated-information-in-france/annual-reports-922804.html
We continue with the next oil major, Exxon Mobil
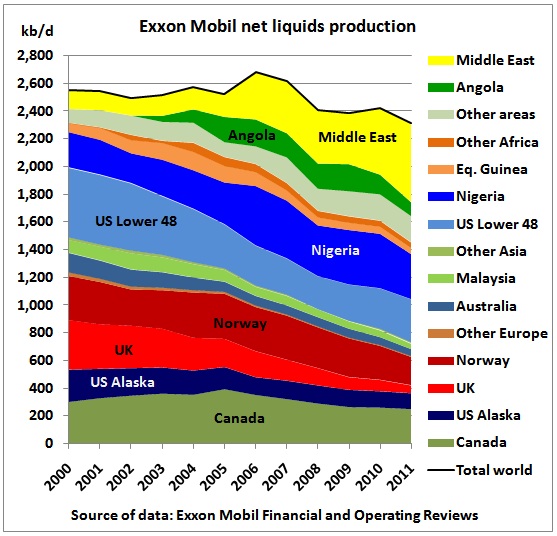 Exxon Mobil’s net liquids production peaked in 2006 and declined since then at 2.8%. The peak was supported by oil from the Middle East. The underlying decline rate after 2004 (without Middle East) was 4%
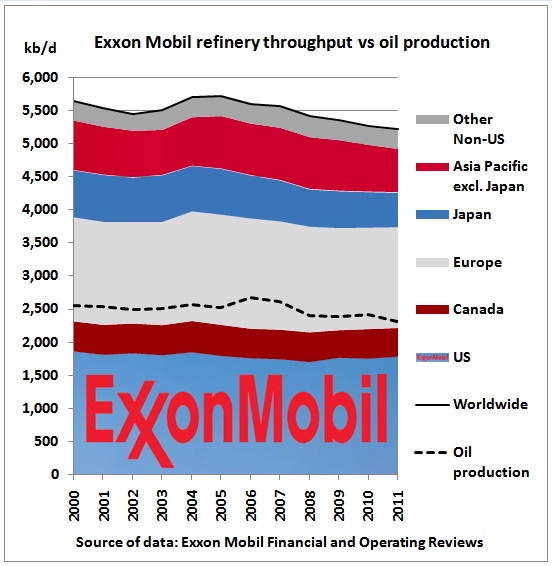 Exxon Mobil’s oil fills only 44% of its refinery throughput. All data are from here:
http://ir.exxonmobil.com/phoenix.zhtml?c=115024&p=irol-reportsannual
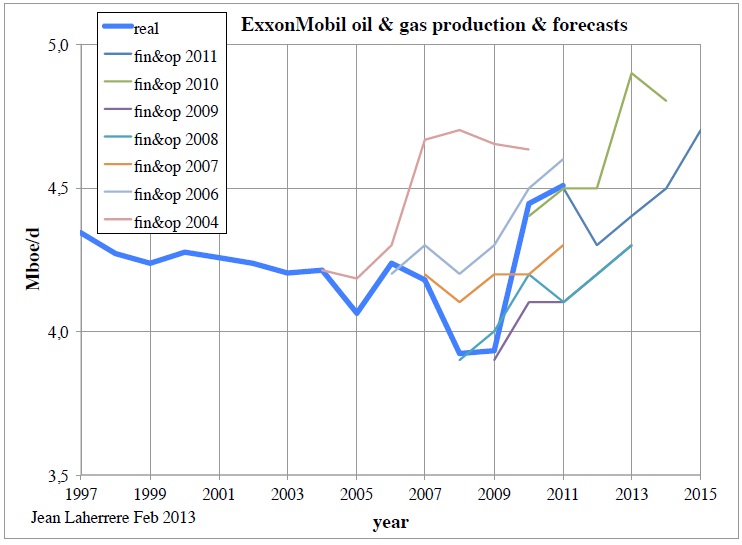 On this graph from Jean, Exxon Mobil’s gas production increased as a result of projects in Qatar and shale gas which more than offset – in energy terms – declining oil production. Only 2009 forecasts were lower than actual. 2010 forecasts were correct for 2011.
Chevron’s production peaked in 2000 but managed to build up a 2nd, albeit lower peak in 2010, thanks to oil mainly from Kazakhstan, Nigeria and the US.
 It is too early to calculate a reliable overall decline rate after the 2nd peak but the underlying decline rate of countries with stagnating or declining production is a modest 3.4 % since 2000.
 After selling off the Motiva and Equilon refineries to Shell, Chevron’s oil production is more or less in line with its refinery inputs, on a net basis.
Chevron data are from here (including earlier reports)
http://phx.corporate-ir.net/phoenix.zhtml?c=130102&p=irol-reportsAnnualArchive_pf
The last of the 5 majors is Shell which peaked in 2002.Except for very modest contributions from Russia, Brazil and Nigeria (on a bumpy plateau), the rest of the supply system is in decline.
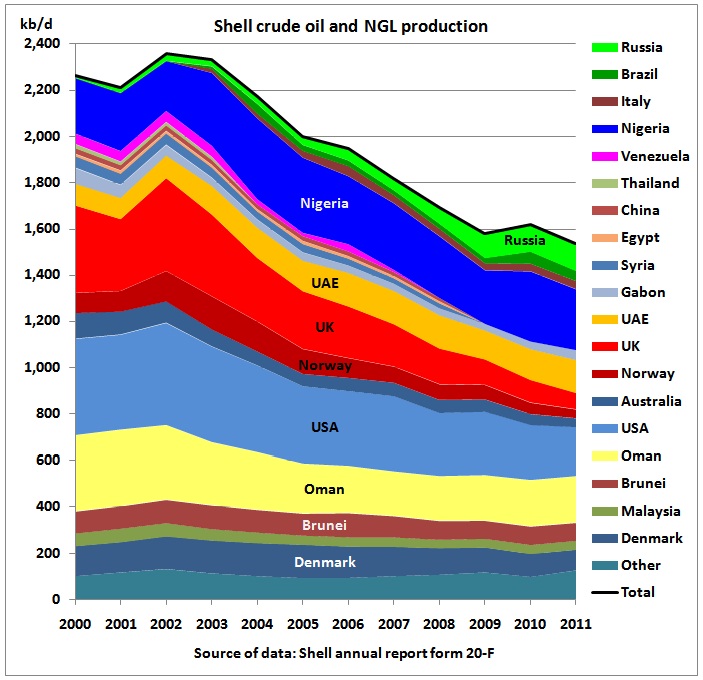 The overall decline rate was 3.9 %, and the underlying decline rate 5.4%.
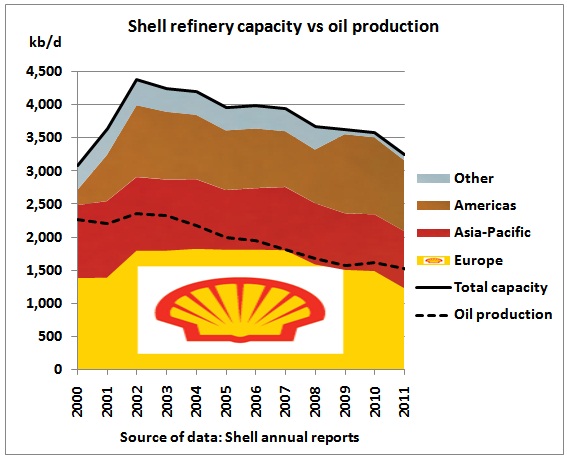 We see the acquisition of refineries in 2001/02, e.g. from Chevron as mentioned above, but since then Shell’s refinery capacities are adjusted according to declining oil production, which is just enough for 47 % of capacities.
Summary
We can now add all production graphs, starting the stack with the underlying decline:
 and put the results into a table:
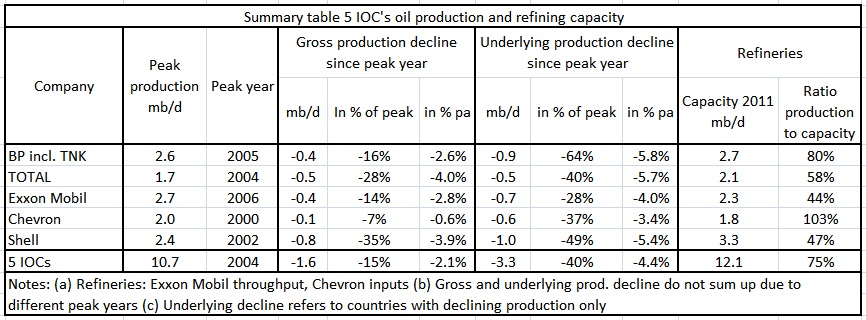
Conclusion:
The underlying decline rate of production is the most important parameter for future production and thus refinery utilization. This rate determines the over-all decline once the growing, offsetting countries no longer grow. Oil companies with refining capacities greatly exceeding their own oil production will face cost pressures as this oil has to be procured from globally available crude exports which are shrinking. There is no way this system can survive long without further price increases when demand grows and crude exports decline. This will have a negative impact on all oil-dependent infrastructure like toll-ways, airport expansions etc. All such new projects should be shelved for good.