It is quite obvious that high oil prices in the last 3-4 years
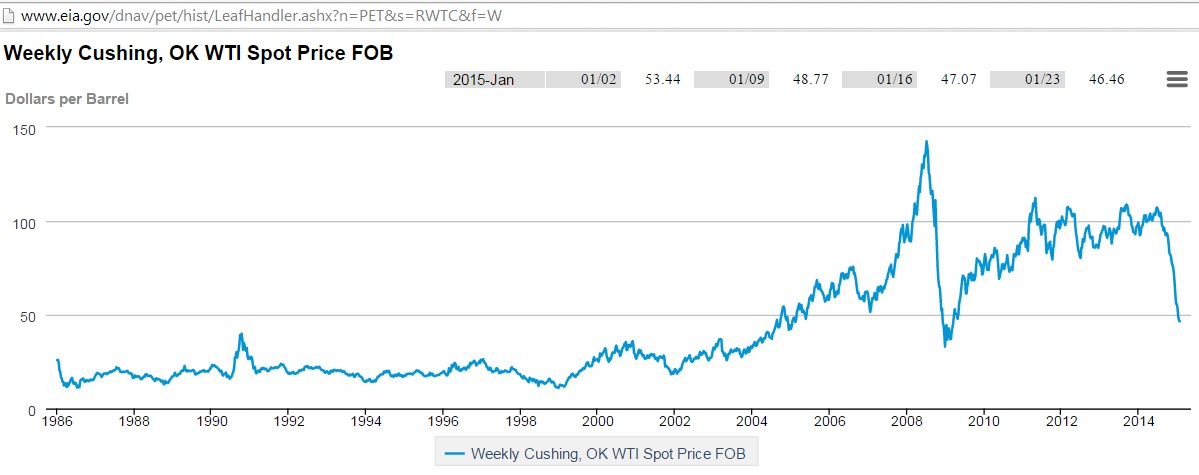
Fig 1: WTI spot prices to 23/1/2015
http://www.eia.gov/dnav/pet/hist/LeafHandler.ashx?n=pet&s=rwtc&f=w
have reduced demand for oil, as shown in this IEA graph for OECD countries:
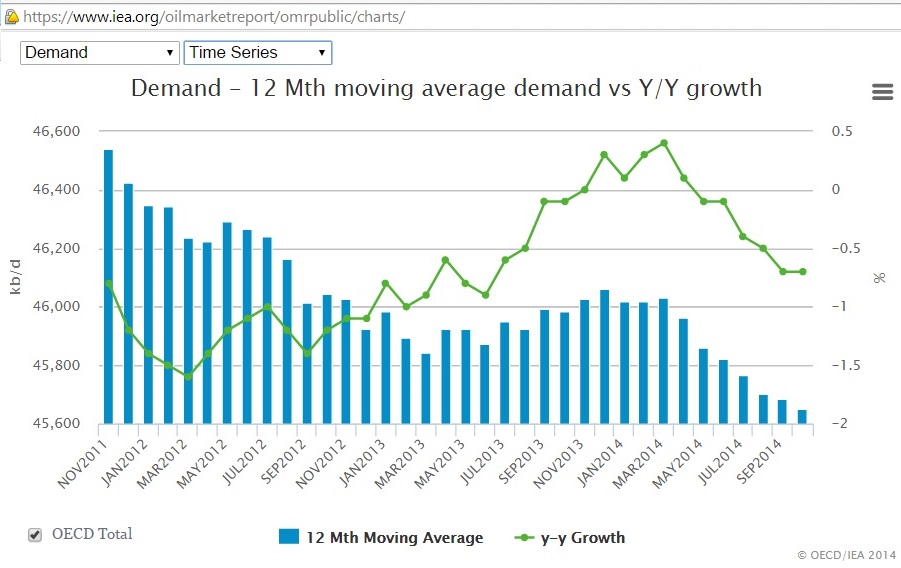
Fig 2: Oil demand in OECD countries Oct 2011 – Sep 2014
https://www.iea.org/oilmarketreport/omrpublic/charts/
So which oil is affordable? Let’s use a graph of the Monetary Policy Report (January 2015) of the Bank of Canada (which would be favourable to Canadian tar sands)
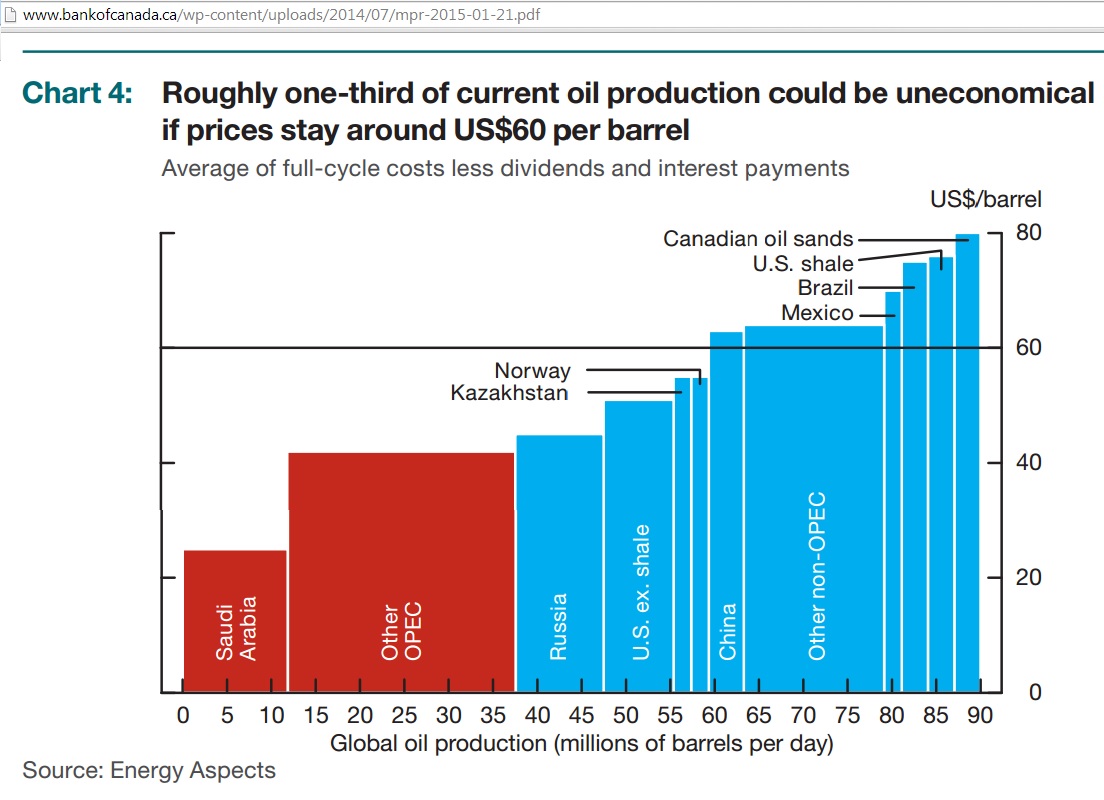
Fig 3: Oil production by area and full-cycle costs
The Bank of Canada report reads: “Based on recent estimates of production costs, roughly one-third of current production could be uneconomical if prices stay around US$60, notably high-cost production in the United States, Canada, Brazil and Mexico (Chart 4). More than two-thirds of the expected increase in the world oil supply would similarly be uneconomical. A decline in private and public investment in high-cost projects could significantly reduce future growth in the oil supply, and the members of the Organization of the Petroleum Exporting Countries (OPEC) would have limited spare capacity to replace a significant decrease in the non-OPEC supply.”
http://www.bankofcanada.ca/wp-content/uploads/2014/07/mpr-2015-01-21.pdf
Let’s put these costs into oil production graphs:
(1) Total Oil Supply
Fig 3 refers to 90 mb/d (x-axis) which was the world’s total oil supply for 2013, according to EIA’s stats available here: http://www.eia.gov/cfapps/ipdbproject/IEDIndex3.cfm?tid=5&pid=53&aid=1
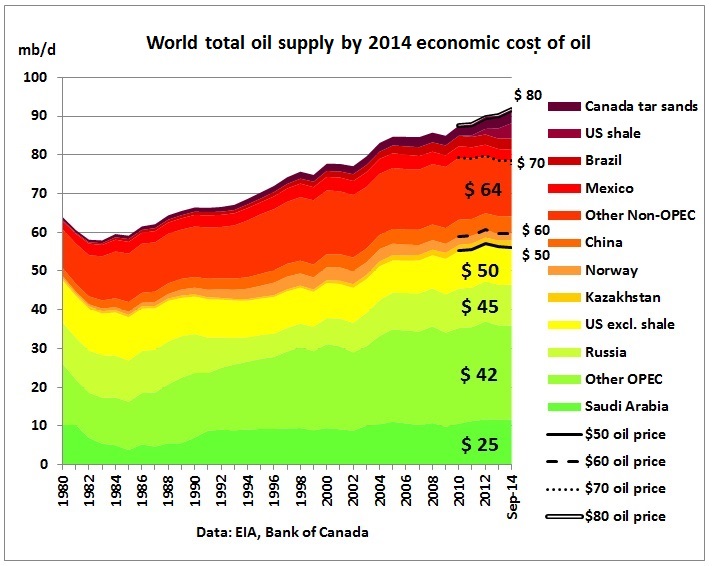
Fig 4: Oil supply by country/area and economic cost of oil
In Fig 4, oil supplies are stacked by 2014 economic cost of oil, starting with Saudi Arabia ($25/barrel, green) and going up to Canadian tar sands ($80/barrel, dark red). The colors have been extended over the whole period to 1980 so that the production history can be seen. Lines in various styles show 4 different cost levels, whereby their lengths are indicative only to show corresponding production levels for the last years.
It seems that oil supplies up to around $75 have peaked (all countries up to Brazil). In other words, if the world is willing (or able) to pay only $75 a barrel, corresponding oil production declined since 2012 – at around 1.6% over 2 years. $50 oil was up and down, but at only 56 mb/d or 60% of current demand. What is important here is that affordable oil does not appear to increase in volume. That has serious implications for economic and transport planning
In Fig 4, oil supply includes: crude oil, natural gas plant liquids, refinery processing gains and other liquids (including bio fuels). The EIA definitions are here:
http://www.eia.gov/cfapps/ipdbproject/docs/IPMNotes.html#p1
Let’s check how that graph would look like if we used just crude oil and condensate.
(2) Crude oil and condensate
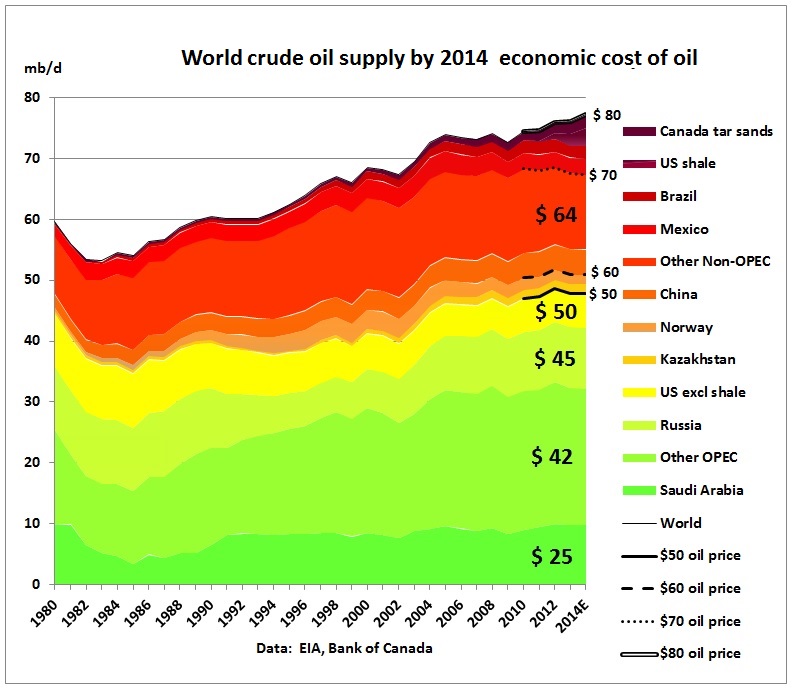
Fig 5: Same as Fig 4, but for crude oil only
All crude oil up to $75 is basically flat since 2005. Expensive unconventional oil has covered up this indisputable trend.
(3) Canadian tar sand costs
So how did the Bank of Canada arrive at $90 for tar sands? The following table is from a July 2014 report of the Canadian Energy Research Institute (http://ceri.ca/)
CANADIAN OIL SANDS SUPPLY COSTS AND DEVELOPMENT PROJECTS (2014-2048)
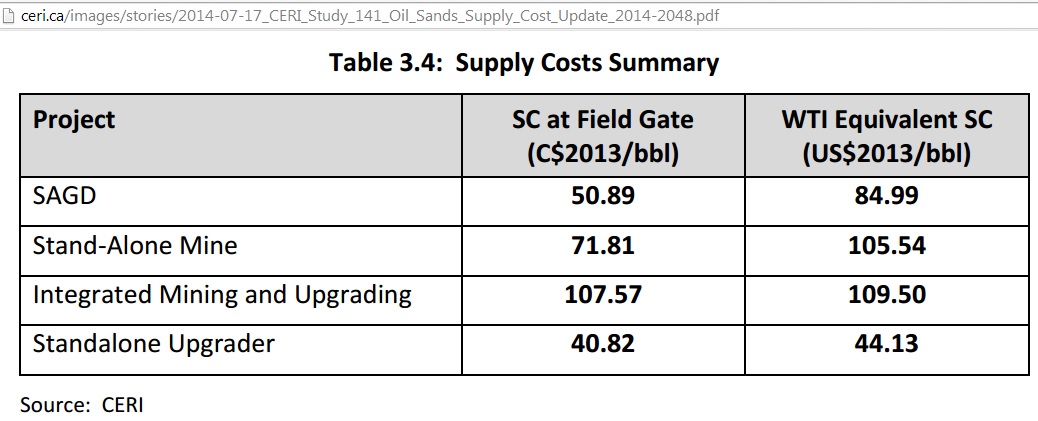
Fig 6: Cost of Canadian tar sands
SAGD stands for steam assisted gravity drainage for in-situ tar sand projects as described here: http://www.connacheroil.com/index.php?page=great_divide_oil_sands
So the Bank of Canada has taken $90 as a WTI equivalent average. The above prices assume a light/heavy differential of $18 a barrel between West Texas Intermediate and West Canadian Select, even after the reversal of the Seaway pipeline and the construction of the southern leg of the Keystone XL in 2013 to connect Cushing to the Gulf of Mexico. This increased WTI, thereby narrowing the differential to Brent, but not to historical levels of $2-5/barrel “potentially indicating two things: either the two markets are no longer correlated and prices are representative of regional markets only or the market to market connectivity is not sufficient to increase WTI prices to Brent levels (sans transportation costs) or a combination of both….. Over time as more blended bitumen and SCO (syncrude oil) continue to penetrate the existing markets as well as new markets, such as the US Gulf Coast and markets outside of North America, the light heavy differential might narrow in the future.”
http://ceri.ca/images/stories/2014-07-17_CERI_Study_141_Oil_Sands_Supply_Cost_Update_2014-2048.pdf
Conclusion:
Using the assessment of the Bank of Canada, production of affordable oil at price levels up to $75 has peaked or is at peak since the turning point of 2005. This means that the global economy cannot grow “normally” again.