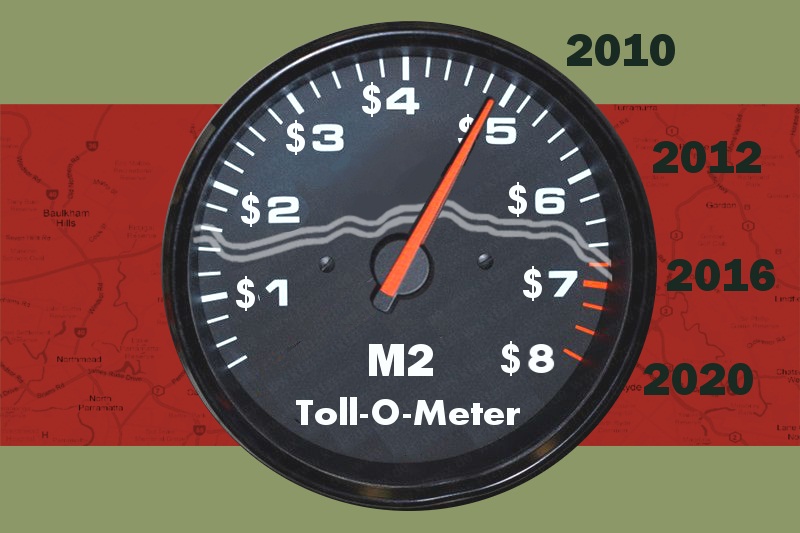
 Let’s calculate future tolls on the M2 toll-way. Starting point for this analysis is this news item from 26th October 2010:
Roads Minister David Borger said the RTA had signed a contract with Hills Motorway Ltd to widen the M2 to three lanes plus a breakdown lane creating an extra 18km of laneway at a cost of $550 million.
“Once completed, project costs will be passed back onto motorists who will foot the bill through a 7.7 per cent hike in road tolls increasing the cost from $4.95 to $6”. [Ref…]
More widely publicised in Ten News:
httpv://www.youtube.com/watch?v=BAjHTR4q_48#t=0m40s
Minister Borger:
“And the project will be funded by a one-off toll increase at the end of the project” The toll is currently $4.95, but the project cost plus inflation will lift the toll to $6”. [Ref…]
So we have a one-off increase of 7.7% on $4.95 plus inflation. The latest CPI (September 2010 quarter) was 2.8%. [Ref…] The RBA forecast is:
“In year-ended terms, underlying inflation is forecast to remain around 2½ per cent until mid 2011, before picking up gradually to 3 per cent by late 2012”.
So we have until the widening opens end 2012:
$ 4.95 * 1.077 * 1.025 [2011] * 1.03 [2012] = $ 5.65 (rounded to nearest 5c)
Obviously, that doesn’t add up to $6. The in-built inflation rate for a $ 6 toll by end 2012 would actually have to be 6%
$ 4.95 * 1.077 * 1.0609 [2011] * 1.0609 [2012] = $ 6.00
That is more than double the target of the Reserve Bank at between 2-3 %.
Inflation Target
The Governor and the Treasurer have agreed that the appropriate target for monetary policy in Australia is to achieve an inflation rate of 2–3 per cent, on average, over the cycle. This is a rate of inflation sufficiently low that it does not materially distort economic decisions in the community. Seeking to achieve this rate, on average, provides discipline for monetary policy decision-making, and serves as an anchor for private-sector inflation expectations. [Ref…]
The RBA’s inflation target doesn’t seem to concern Transurban. Their in-built inflation clock – with or without M2 widening – ticks at 1% per quarter or 4.06% pa and has its own starting point and increase mechanism in 50 cent steps.

Embedded Inflation Protection
Hills M2* Escalated quarterly by the greater of quarterly CPI or 1%.
*Escalation description denotes theoretical toll only. Actual toll increases on M1, M2, M4 and M5 in Sydney are based on the rounding of theoretical tolls in 50 cent increments to accommodate cash toll collection. p 35/75. [Ref…]
 So let’s put that into a graph. This graph shows tolls with and without widening and RBA’s inflation band of 2-3%. The tolls charged go up in 50 cents increments, touching the 4% curve whenever a new toll is introduced. The average increase over 10 years is 3.3% pa, above the RBA’s upper inflation limit. Using the 1% per quarter increase, there might be a $ 5.45 toll by end 2011, BEFORE the widening would open. That would be a bad surprise for many.
Conclusion:
The widening pushes tolls way beyond the RBA inflation target, thus contributing towards higher interest rates which will hit motorists with mortgages, the very motorists who are using the M2. The root cause for this is the low productivity with which cars (low occupancy rate) use high-way infrastructure in terms of person-kms (and therefore revenue) per invested dollar. The productivity could be lifted by introducing tolls per occupant, not per car. That will be a technical challenge for e-tolling. It will have to happen when petrol rationing is introduced, in order to maintain toll-revenue. So don’t pull down the old booths. One day they will be needed again.
Needless to say, high tolls will encourage motorists to take public transport.
Disclaimer: Great care has been taken to do a fair analysis. No responsibility can be taken for its accuracy. Its sole purpose is to alert the reader to this toll increase problem. It is strongly recommended the reader tries to do his/her own calculations. Transurban may decide to increase tolls different from the above.