Skip to content

Crude Oil Peak

Menu
  • Home
    • About
    • Disclaimer
  • OECD imports
    • France
    • Germany
    • Italy
    • Japan oil imports
    • OECD Europe
    • OECD Pacific
    • South Korea
    • UK
    • US Imports
  • Australian graphs
    • Australian electricity supply graphs
    • Australian crude oil production
    • Australian crude oil reserves
    • Oil import dependency
    • Oil and fuel imports
    • ULP prices
    • Industry stocks
    • End use of oil
    • WA crude oil
    • WA domestic gas
    • East coast conventional gas
    • Geoscience Australia March 2010
    • Geoscience Australia 2005/2006
    • Gippsland
    • LPG
    • Petrol rationing in WW2
  • Oil reserves
    • OPEC paper barrels
    • Kuwait Reserves
    • Strategic Oil Reserve
  • Global Peak
    • Algeria peak
    • Angola peak oil
    • Argentina peak
    • Azerbaijan peak
    • Brazil
    • Brunei peak
    • Canada and tar sands
    • Caspian peak
    • China Peak Oil
    • Deepwater peak
    • Egypt
    • Gabon peak
    • India peak oil
    • Indonesia peak
    • Iran Peak
    • Libya peak oil
    • Malaysia-peak
    • Mexico peak
    • Norway peak oil
    • Qatar peak
    • Russia peak
    • Saudi Arabia export peak
    • Sudan Peak
    • Syria
    • Tunesia
    • UAE peak
    • UK Peak
    • US Peak
    • Vietnam peak
    • Venezuela peak
    • Yemen
  • Energy Transitions
    • Germany energy transition
    • Japan Energy Transition
    • UK Energy Transition
    • US
  • Fuel Shortages
    • China Fuel Shortages
    • Egypt Diesel shortages
    • India petrol price hike
    • Malawi fuel shortage
    • Nepal
    • Nigeria fuel shortage
    • Pakistan petrol shortage
    • Russia
    • Tanzania fuel shortage
    • Uganda Fuel Shortage
    • Yemen fuel shortages
  • I told you so
    • Top Ryde Shopping Centre
    • North South Bypass Tunnel (Clem7) Brisbane
    • Airportlink Brisbane
    • Cross City Tunnel
    • Lane Cove Tunnel
    • Too late for Metro tunnels
    • Australian car manufacturing closing down
    • How the first phase of peak oil brought Virgin Australia into minus after 2008
  • Solutions
    • Night trains
    • Electric Rail on Freeways
    • LNG locomotive conversion
    • Electric trolley buses
    • Walk to school
  • Oil crises
    • Oil crisis 1973
    • My experience oil crisis 1979
    • Historical Oil Disruptions
  • Food and Oil
    • Farm Costs Australia
    • Food crises and political instability
  • Global warming
    • Storms of my Grandchildren
    • Extreme weather events
    • Global warming and petrol lines
    • Compensation claims from global warming damage
    • Sea level rises
    • Why coal seam gas will not reduce CO2 emissions
Menu

US shale oil too expensive, peaks 1H 2015

Posted on September 30, 2015

According to EIA data, monthly US crude oil production peaked in April 2015 at 9.6 mb/d.

Fig 1: US crude oil production to June 2015

http://www.eia.gov/dnav/pet/pet_crd_crpdn_adc_mbblpd_m.htm

The above graph shows that US crude production increased by around 4 mb/d between mid 2011 and mid 2015, mostly from shale oil which took off – with a delay – when oil prices exceeded US$ 80-90. That stellar growth has come to an end, also with a delay, after oil prices plummeted.

Let’s zoom into the period starting with January 2014:
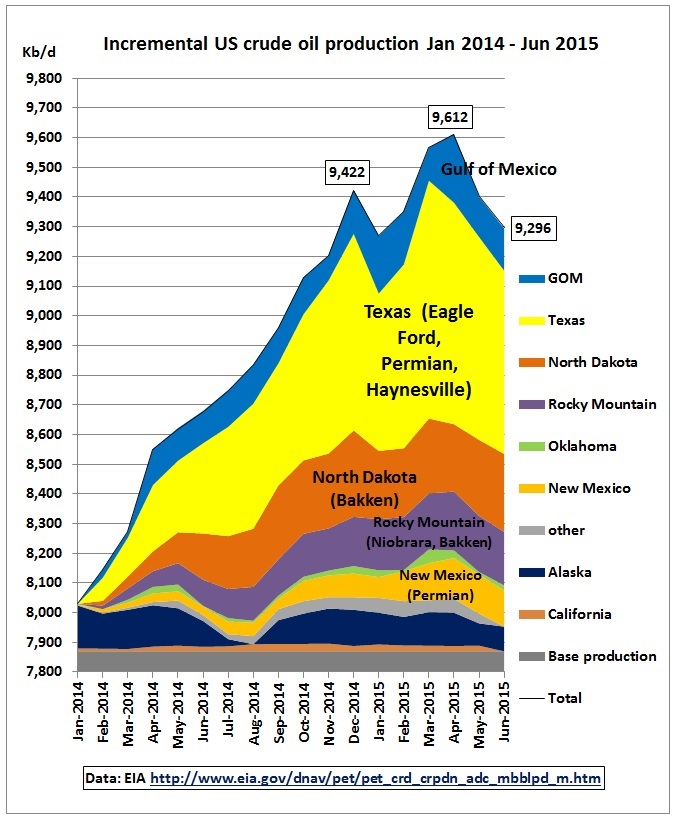
Fig 2: US incremental crude production Jan 2014 – Jun 2015

The April 2015 peak was caused by higher GOM production resulting from production start-ups after lifting the drilling moratorium in 2010. Shale oil peaked one month earlier, after the winter drop. However, month by month production can change and future revisions of data are likely due to reporting delays.  What is more important than the month of peaking is the fact that US oil production stopped growing.

(Note: Incremental production is calculated as production minus the minimum production in the period under consideration. The sum of the minimum production is the base production)

North Dakota

As an example, the following graphs show the peaking in the Bakken oil field.

Fig 3: North Dakota oil production

https://www.dmr.nd.gov/oilgas/stats/statisticsvw.asp

Fig 4: Bakken production from EIA’s drilling productivity report

http://www.eia.gov/petroleum/drilling/

Fig 5: Bakken monthly production changes

This graph shows that in March 2015 production from new wells dropped below the replacement requirements given by decline in old wells, causing the peaking of production.

Drilling Rig Count

Fig: 6 US oil drilling rig count

Fig 7: Offshore drilling rigs by region

http://www.eia.gov/todayinenergy/detail.cfm?id=23032

In August 2015, the number of active GOM offshore rigs had fallen by 46% over one year, much more than the global average of 20%  (from 377 to 304).

Shale oil bubble flying high

Fig 8: CAPEX by type of oil

From Schlumberger’s presentation at the Scotia Howard Weil 2015 Energy Conference
New Orleans, 23 March 2015
http://www.slb.com/news/presentations/2015/~/media/Files/news/presentations/2015/Kibsgaard_Scotia_Weil_03232015.ashx

 83% of cash flow for servicing debt

Using data up to the 2nd quarter of 2015, the EIA analysed 44 US onshore companies contributing 2.7 mb/d to crude oil production growth. They had negative free cash flows (difference between operating cash flow and capital expenditure) since 2011:

Fig 9: US onshore companies free cash flow

http://www.eia.gov/petroleum/weekly/archive/2015/150910/includes/analysis_print.cfm

That the 1H 2015 result was not worse has likely to do with a reduction in CAPEX which was 12% for international oil companies in 4Q 2014.

With low oil prices, servicing debt has become a major problem for these oil producers. 83% of cash flow (curve, RHS) is used for debt repayments (blue negative columns, LHS):

Fig 10: Cash flow for US onshore producers

http://www.eia.gov/petroleum/weekly/archive/2015/150910/includes/analysis_print.cfm

This means less money is available for dividends, investments in new wells and contingencies.

Shale oil companies are particularly hard hit as their wells decline very fast in the first 2 years. The following graph is from a slide show (Sep 2015)

The North American Unconventional Revolution & The 2014-2015 Oil Price Collapse

by Art Berman who specializes in monitoring US shale oil companies.

Fig 11: CAPEX to cash and debt to cash ratios for 14 selected US companies

Fig 12: Cost per barrel oil equivalent for 3 US companies

http://www.artberman.com/wp-content/uploads/The-Shale-Revolution-The-Current-Oil-Price-Collapse-21-Sept-2015-copy.pdf

The unconventional oil spike sits on top of a bumpy production plateau in the rest of world, where crude production in 2014/15 was just 1 mb/d higher than in 2005, the year when the peaking started.

Fig 13: Incremental US shale oil and tar sands vs RoW

Conclusion:

The world lives on borrowed oil. And on borrowed time because we don’t know how long this debt/oil blend will last.

Key data & graphs

  • Net oil importers
  • Oil Exports
  • Crude oil imports
  • Downloads
  • Latest Graphs
  • Oil price analysis
  • US drilling rig count
  • International drilling rig count
  • Australian fuel prices
  • Diary
  • International oil companies
  • US tight oil production
  • China peak oil
  • World liquids supply – demand balance
  • Tankers arriving and departing in Sydney
  • Australian oil and fuel imports

Latest posts

  • Australian Energy Minister – Asked About Reports of Three Tankers Burning in Hormuz – Sees Only “General Uncertainty”
  • Jet fuel stocks just 2.6 days above the Minimum Stockholding Obligation as new Western Sydney Airport enthusiasm soars
  • Asia Pacific peak oil update 2025, consumption 5x higher than production
  • Australian jet fuel stock floating offshore while fuel prices are flying away
  • Australian Diesel imports in August dropped from high in May
  • First early hot summer day in spring 2026 and power prices spike at a whopping AUD 23k per MWh

Archives

©2026 Crude Oil Peak | Design: Newspaperly WordPress Theme