The media is full with news that there is a global oil glut.
There are now more than 3bn barrels of excess oil in the world
13/11/2015
http://www.telegraph.co.uk/finance/oilprices/11993687/There-are-now-more-than-3bn-barrels-of-excess-oil-in-the-world.html
Record oil glut stands at 3bn barrels
13/11/2015
http://www.bbc.com/news/business-34808487
It was parroted by the Australian public broadcaster ABC TV, using this (unsuitable) opportunity to take a swipe at peak oil:
Peak oil losing credibility as renewables shift accelerates
24/12/2015
“With the world awash with too much crude oil at the moment, the fear of an economic catastrophe when fossil fuels start running out is quietly fading in the background.”
http://www.abc.net.au/news/2015-12-24/peak-oil-losing-credibility-as-shift-to-renewables-accelerates/7052196
These stories go back to the IEA’s Monthly Oil Market Report (OMR), November 2015 which reads:
“Stockpiles of oil at a record 3 billion barrels are providing world markets with a degree of comfort. This massive cushion has inflated even as the global oil market adjusts to $50/bbl oil.”
https://www.iea.org/oilmarketreport/reports/2015/1115/
So how much is 3 bn barrels?
Let’s have a look at the statistics in the latest IEA OMR of December 2015. It’s only about OECD stocks, not the whole world.
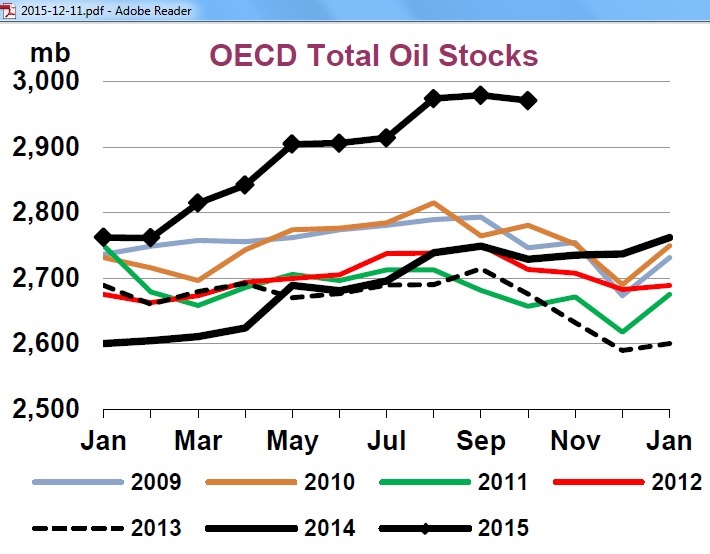
Fig 1: OECD total oil stocks
https://www.iea.org/media/omrreports/fullissues/2015-12-11.pdf
We see that oil stocks in the period 2009 (light blue line) to 2013 (dotted line) varied between 2,6 bn and 2.8 bn barrels along with seasonal changes. The average stocks for this time of the year is 2.7 bn barrels. We can consider this range as the result of normal operating conditions allowing for accidents, refinery maintenance, transport disruptions, strikes etc but also demand side changes from a weak economy (2009) to high oil prices (2013).
Therefore, that magic glut is 3 bn – 2.7 bn = 300 million barrels or roughly 10% of the average. The long term trend of OECD stocks is shown in the next graph:
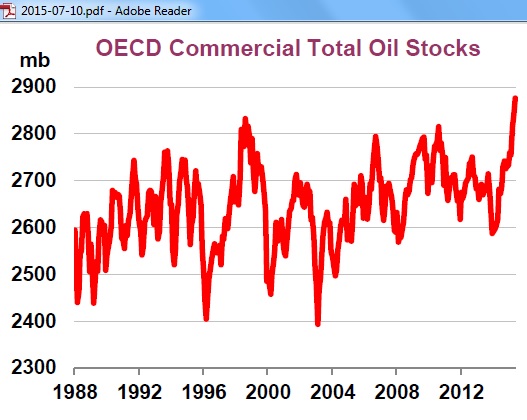
Fig 2: OECD stock changes since 1988
In 1988, average stocks were 2.5 bn barrels One can put many trend lines into Fig 2, depending on which period one selects and which exceptional events are excluded. OECD consumption peaked in 2005 at 23% higher than in 1988 but is now only 11% higher. So one would expect average stocks also to be higher accordingly, at around 2.8 bn barrels.
Regional distribution of OECD stocks
So where exactly is that so-called glut?
OECD Europe
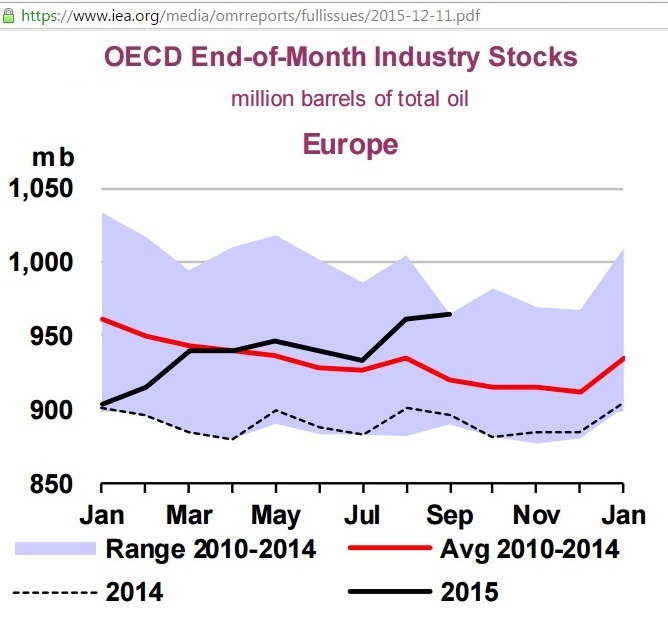
Fig 3: Europe total oil stocks
European total oil stocks (crude plus products) are in the upper range.
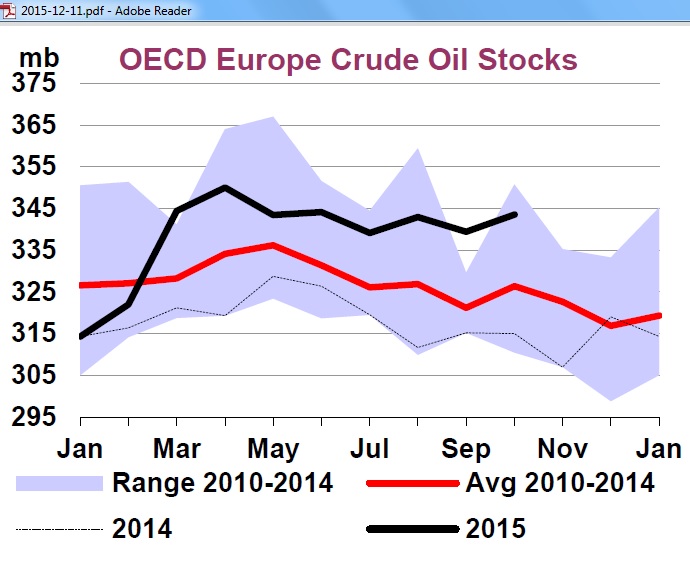
Fig 4: Europe crude oil stocks
European crude stocks are also at the upper end of the range, but that’s not really a glut.
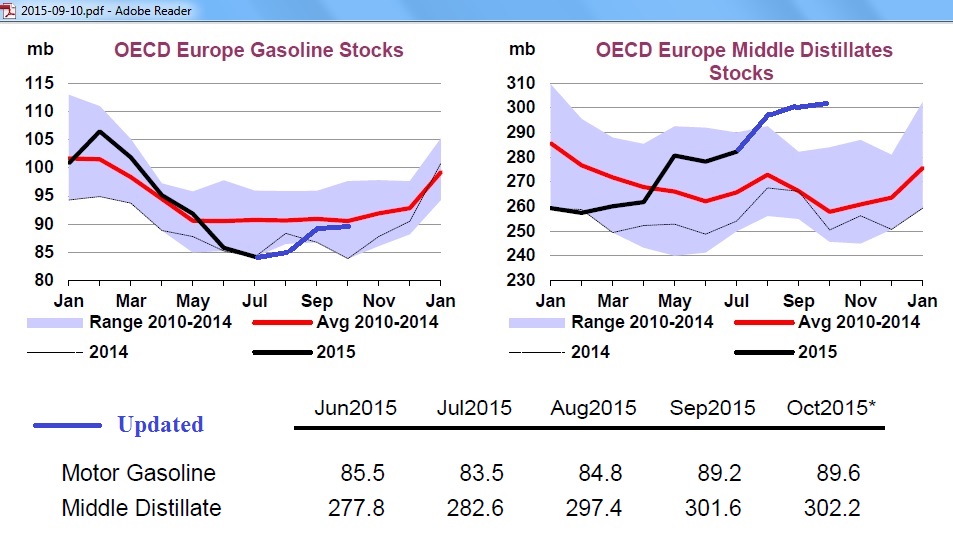
Fig 5: Europe gasoline and distillate stocks
Europe’s gasoline stocks are average, but distillates are 18% higher. Half of that higher stock results from an unseasonal increase in the Netherlands.
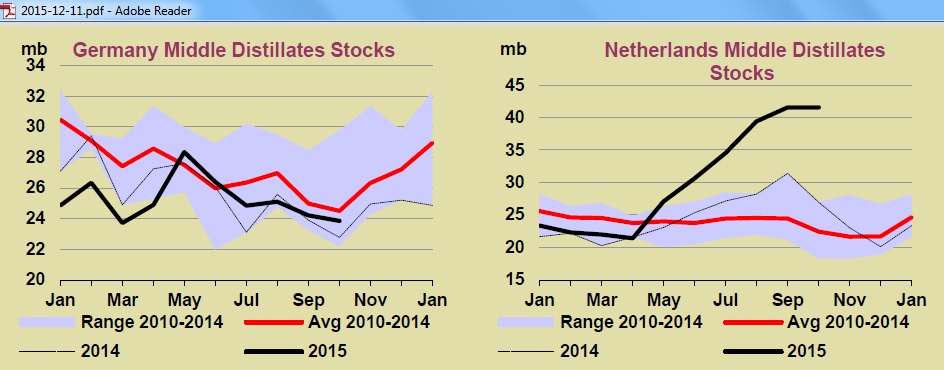
Fig 6: Middle Distillate Stocks in Germany and Netherlands
The reason for higher stock-levels in the Netherlands is that products cannot be easily transported on river Rhine which experienced low water levels for many months in 2015, due to lack of rainfall in the catchment.
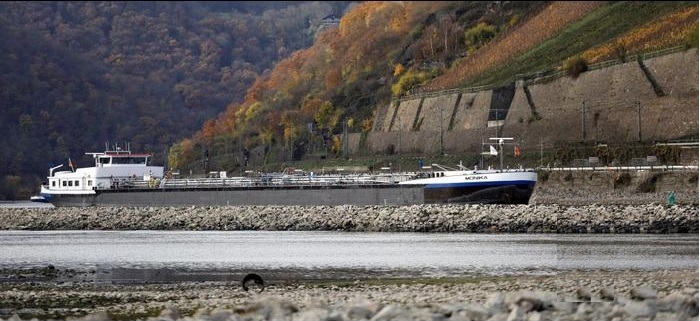
Fig 7: Tankers can’t take full load due to low water levels on river Rhine
Shrinking Rhine: shipping scrapes by as river stays at lowest level for 40 years
12/11/2015
European ‘extreme weather belt’ linked to worst drought since 2003
http://www.theguardian.com/world/2015/nov/12/shrinking-rhine-shipping-scrapes-by-as-river-stays-at-lowest-level-for-40-years
OECD Asia Oceania
Australia, Japan, Korea
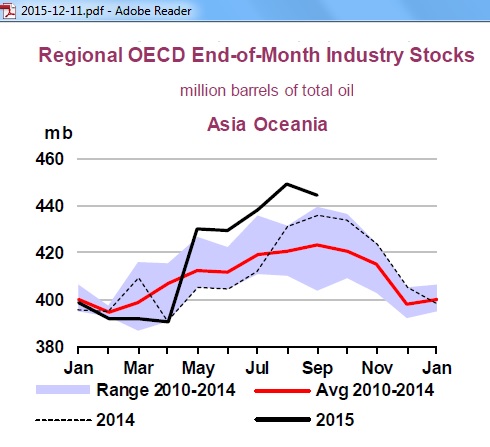
Fig 8: Asia Oceania total oil stocks
Total oil stocks in Asia Oceania are slightly above the usual range and 5% above average.
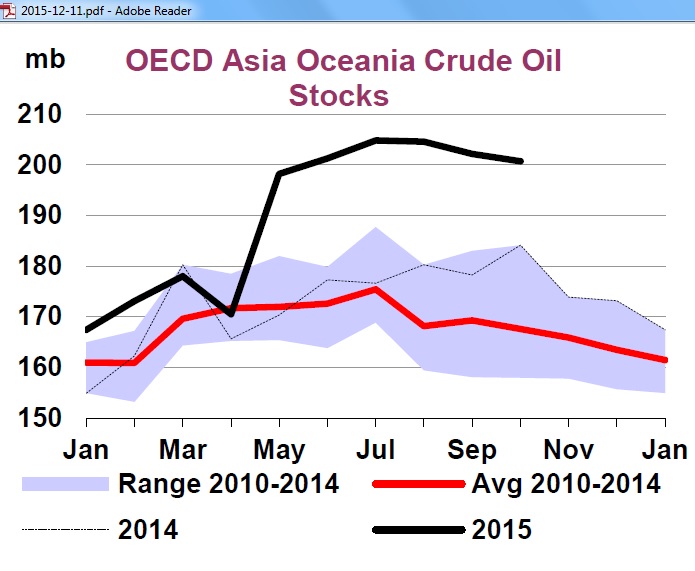
Fig 9: Asia Oceania crude oil stocks 21% above average
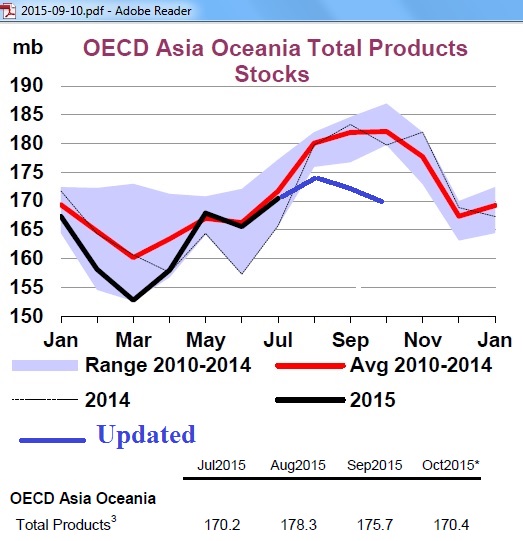
Fig 10: Asia Oceania total product stocks 7% below average
OECD Americas
US, Canada, Mexico
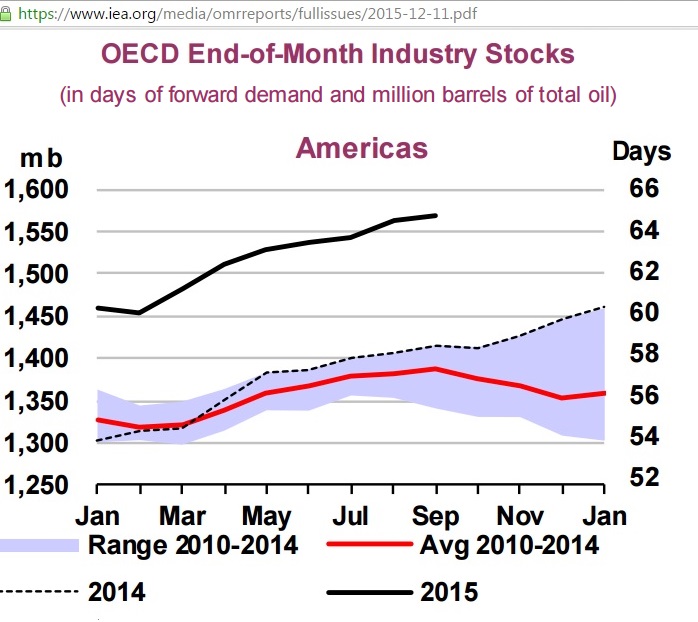
Fig 11: Americas total oil stocks
Ah, here we finally have a large part of that magic glut, around 190 mb, 15% higher than average and around 7 days of forward demand, most of it crude in the US:
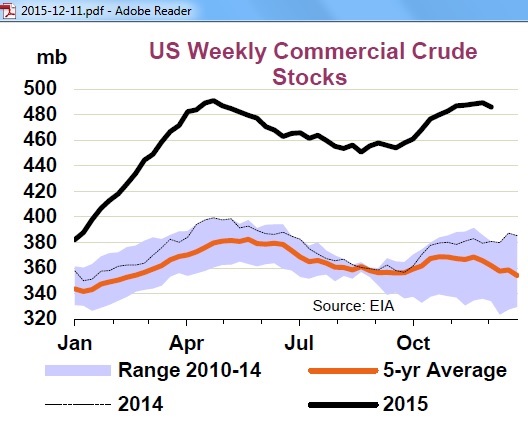
Fig 12: US commercial crude stocks 100 mb > average
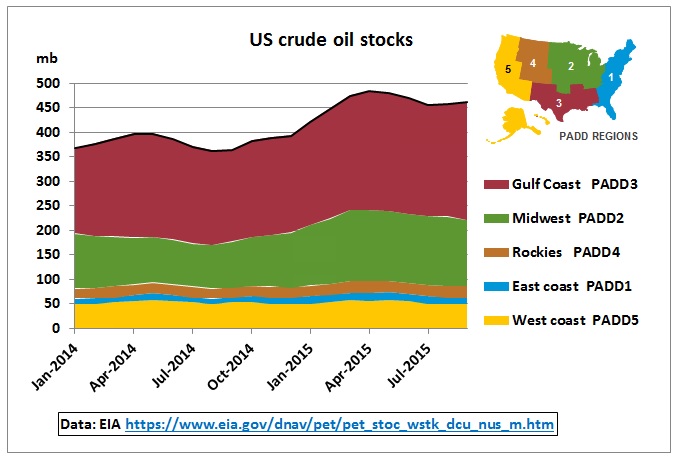
Fig 13: US crude stocks by region
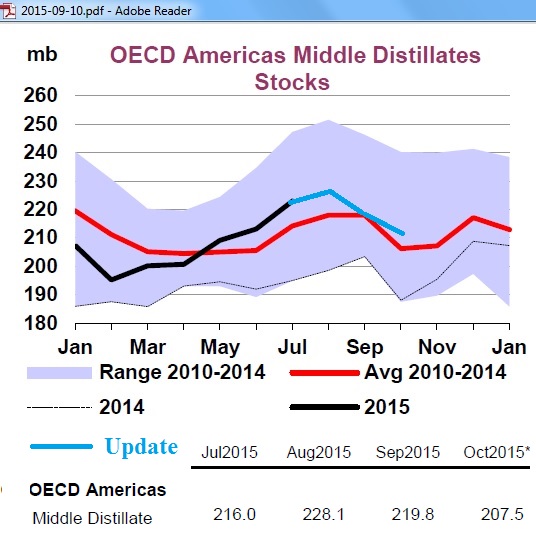
Fig 14: Americas distillate stocks around average
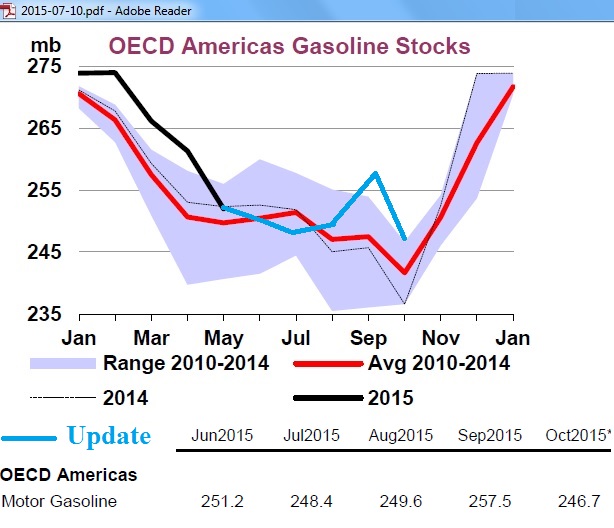
Fig 15: America’s gasoline stock a bit above average
Summary OECD
Let’s put all this in 2 summary graphs
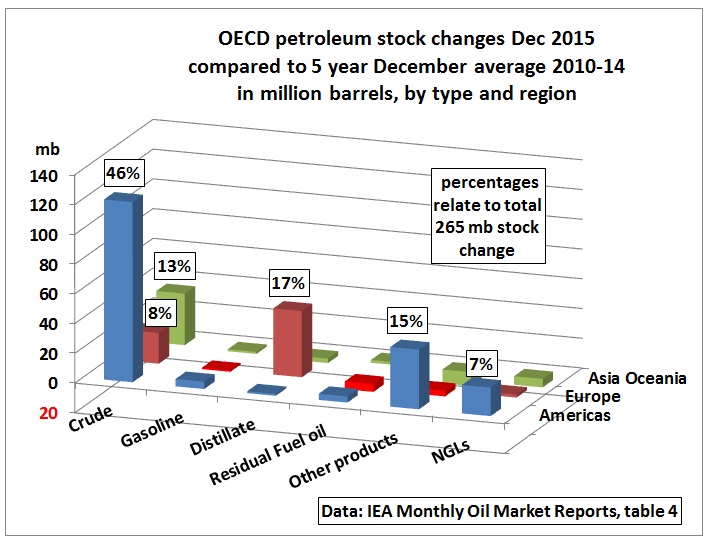
Fig 16: OECD stock changes in comparison to 5 year average
Fig 16 shows that 2/3 of the above-average oil stocks are in America, mainly in the US. 46% is crude oil, most likely light tight (shale) oil (LTO) including condensate which requires special refining. 15% are other products like LPG, also coming mainly from LTO. 7% of additional stocks are NGLs, much of it from shale gas.
When the tight oil boom started in 2010/11 there were following phases/options to accommodate growing quantities of LTO
- Replacement of light oil imports of similar grade (eg. From West/North Africa)
- Blending with medium and heavy crudes (however resulting in refining inefficiencies and different product mix)
- Increased capacity utilisation of existing refineries
- Debottlenecking refineries by e.g. modifying the atmospheric distillation unit
- New stabilizers, splitters and hydroskimmers
It seems options 1-4 have been exhausted. It could well be that tight oil inventories went up as phase 5 is too slow and expensive.
Next option is to export:
Congressional Leaders Agree to Lift 40-Year Ban on Oil Exports
16/12/2015
http://www.wsj.com/articles/congressional-leaders-agree-to-lift-40-year-ban-on-oil-exports-1450242995
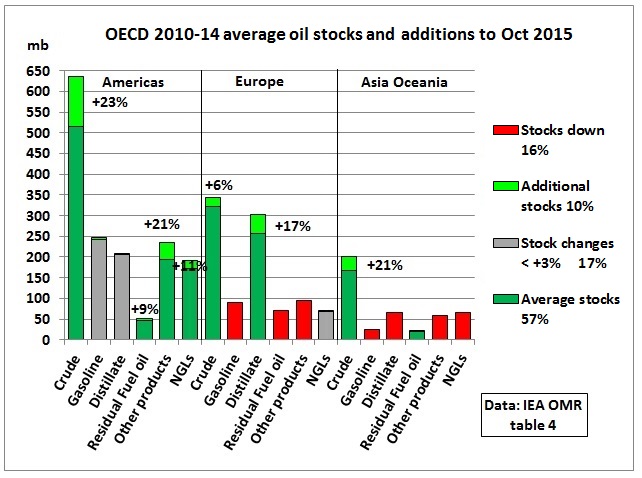
Fig 17: OECD stocks and changes compared to 5 year average
Fig 17 is a zero scaled graph showing the average stocks 2010-14 (dark green, grey and red columns) and the additional stock build until October 2015 (light green columns) for each of the 3 OECD regions. Only 57% of the total stocks of 2.97 bn barrels have really grown (dark green columns) by 10% (light green columns) to arrive at a 67% share. 17% have increased by less than a negligible 3% (grey columns) and 16% have actually decreased.
Whether LTO stocks will remain at current levels will be interesting to watch as US oil production seems to have peaked.
Singapore
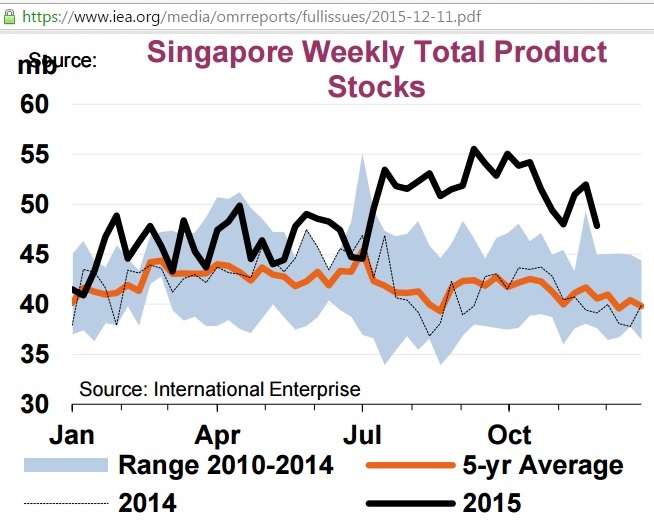
Fig 18: Singapore product stocks slightly above range
China

Fig 19: China product stocks
Chinese oil consumption has increased by around 20% since 2010. A similar increase in peak stocks would require 180 mb. Compared to OECD countries China’s product stocks per 1 mb/d product consumption are much lower so there is no case of stocks being too high.
Conclusion
It is misleading to say the world sits on excess stocks of 3 bn barrels of oil, 2.7 bn of which are already needed in both crude and product stocks for a smooth operation of the refining and distribution system. Most of the stock build since mid 2014 seems to be related to US light tight oil which refineries could not accommodate due to their original designs.
Further reading
Assessment of the Cost and Scale of Refinery Capacity Additions Necessary to Absorb Projected US Light Tight Oil Increase
October 2014
http://energypolicy.columbia.edu/turnermasonanalysis
http://energypolicy.columbia.edu/sites/default/files/energy/Turner%20Mason%20Analysis_October%202014.pdf
Technical Options for Processing Additional Light Tight Oil Volumes Within the United States
6/4/2015
http://www.eia.gov/analysis/studies/petroleum/lto/
The Crude Oil Export Ban–What, Me Worry About Peak Oil?
27/12/2015
http://www.artberman.com/the-crude-oil-export-ban-what-me-worry-about-peak-oil/