As Ford Australia announced the closure of its factory in 2016, the Sydney Morning Herald ‘s headline was:
24/5/2013 Era of the Aussie car over
http://www.smh.com.au/business/era-of-the-aussie-car-over-20130523-2k48f.html
Right. There is an overproduction of cars worldwide. Let’s have a look at the numbers.
In the last 10 years the world’s annual car production went up from 41 million to 63 million cars in 2012, or 52%. Almost 2/3 of this growth came from China. However, in the same period, global liquid supplies went up only 16%, an obvious mismatch.
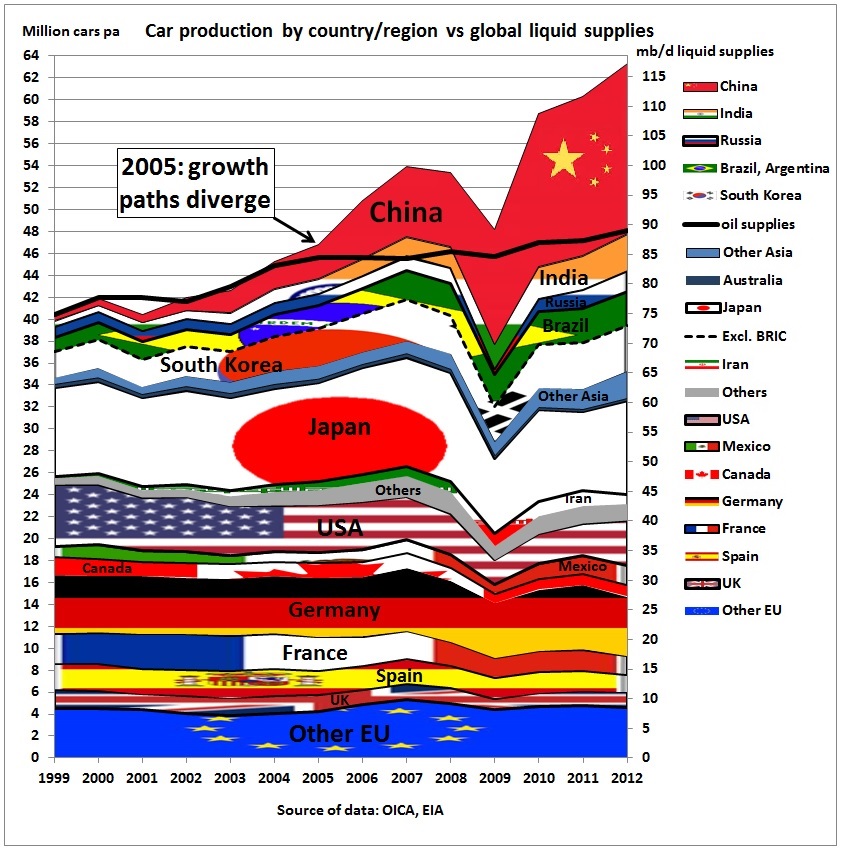
Data are from here http://oica.net/category/production-statistics/ and http://www.eia.gov/cfapps/ipdbproject/iedindex3.cfm?
In the above graph, car production (LHS, in million cars pa) is stacked as follows: EU countries, North America (US, Canada, Mexico), Others, Iran, Asia and BRIC countries (above the dotted line). Global oil supplies (RHS, in million barrels per day) include crude oil, lease condensate, natural gas plant liquids, refinery processing gains and other liquids. The scale of oil supplies is chosen in such a way that on the graph it coincides with car production in 1999.
We see that in 2005 global car production starts to grow much faster than liquids supplies. Incidentally, this is the beginning of peak oil. The global financial crisis – triggered by the convergence of high oil prices and accumulated debt – interrupted the growth, but not in BRIC countries (except in Russia)
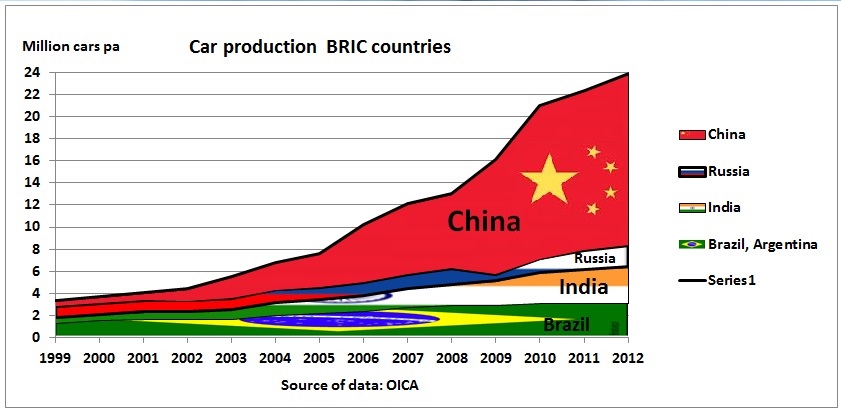
Growing car production in BRIC countries
So how can that gap between car production and oil production be explained?
Let’s compare car production with petroleum consumption:
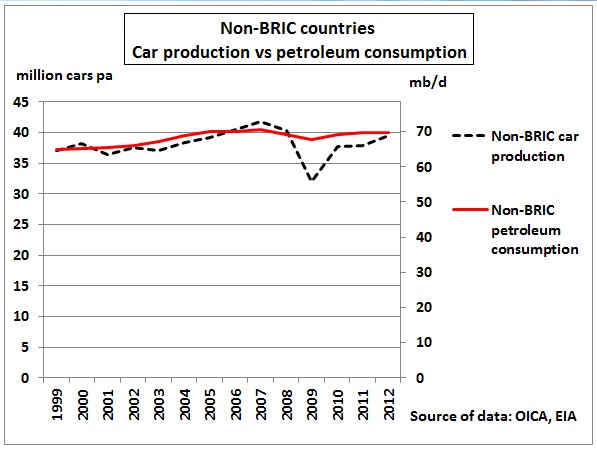
We see that non-BRIC car production in 2012 was more or less in line with petroleum consumption trends (+6% over 10 years, less than half of global oil production growth) except during the GFC. Quantitative easing brought the system back to life but nevertheless car production peaked in 2007 at 41.8 million cars, with 2012 production 2.3 million lower.
The situation is totally different in BRIC countries
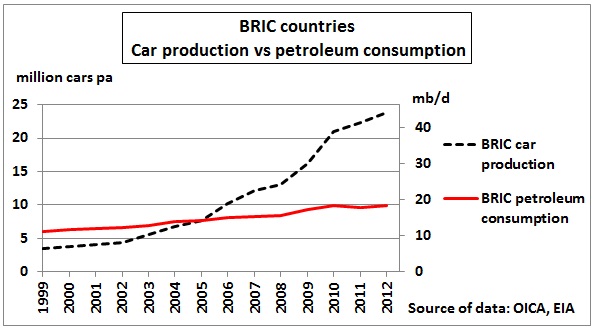
Using the same ratio of petroleum consumption to car production as in the non-BRIC graph above we see that cars before 2005 were under-produced and after that over-produced. The trend line of car production and petroleum consumption have completely different directions, meaning that BRIC cars are driven less. If that should change, there would be an unbridgeable gap in oil production of more than 25 mb/d
Back to the small world of Australian car production
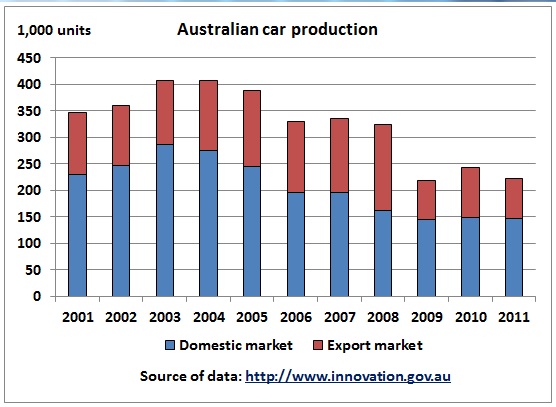
It peaked in 2004 and profitability dramatically changed in 2005. Does that year ring a bell?
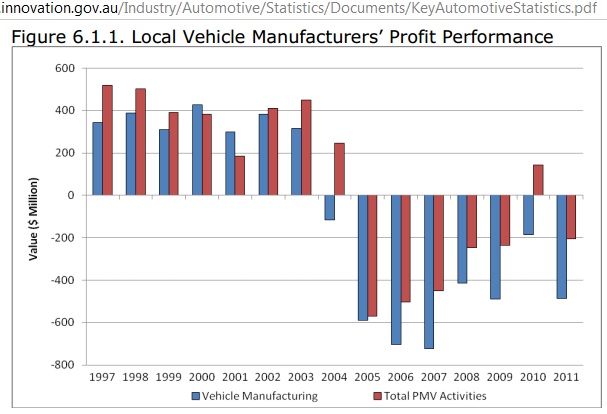
http://www.innovation.gov.au/Industry/Automotive/Statistics/Documents/KeyAutomotiveStatistics.pdf
Summary: The footprint of 2005 as a pivotal year of change is everywhere. Western countries are lucky BRIC’s cars don’t gas guzzle around like their own. But the conflict is pre-programmed. The more cars, the worse it will get. Those politicians wishing an Asian Century with 100s of millions of new prosperous consumers should check what they wish for.
Outlook: We had Aussie road tunnels in receivership, Aussie refineries closing and now another Aussie car factory closing. All part of peak oil. Who’s next and when? Airlines? Toll-way operators sitting on huge debts? Remember we are in a phase where oil production growth since 1999 was not enough to provide for normal economic growth. Just picture what will happen when oil decline starts in serious.
What to do: Re-tool car industry to manufacture non-automotive products. CNG buses, rail cars and components for the renewable energy should be on the top of the list
What not to do: Build more road tunnels, motorways, highways and new airports.
Related post:
31/8/2011 1 billion vehicles in year #7 of peak oil
http://crudeoilpeak.info/1-billion-vehicles-in-year-7-of-peak-oil
Further reading
Foreign Technology in China’s Automobile Industry:
Implications for Energy, Economic Development, and Environment
2003 (10 years ago: what were the projections?)
http://www.wilsoncenter.org/sites/default/files/2-feature_1.pdf
Designated drivers: How China plans to dominate the global auto industry
2012
http://www.amazon.com/Designated-Drivers-Dominate-Global-Industry/dp/111832885X