This is another post in the series on how US tight oil has impacted on global oil markets. This time we look at US petroleum product exports.
(1) Destination of US product exports
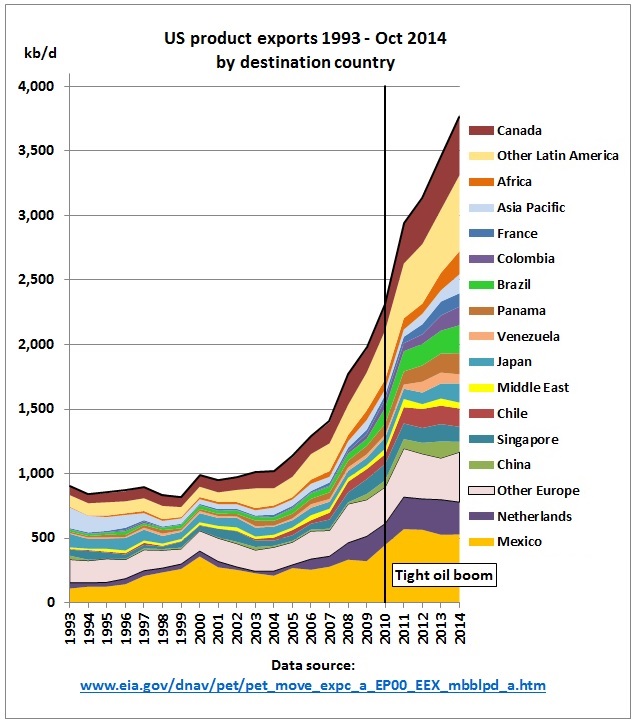
Fig 1: US petroleum product exports by destination and type of growth
Data source: http://www.eia.gov/dnav/pet/pet_move_expc_a_EP00_EEX_mbblpd_a.htm
Exports started to grow already in 2005, a year which appears in many graphs as a turning point. While the growth looks impressive, around 40% of US exports no longer increased since 2011, a year after the very beginning of the tight oil boom (see 1,500 kb/d grid line in Fig 1)
Note that in all graphs of this post 2014 figures have been estimated with data up to October 2014, without seasonal adjustments.
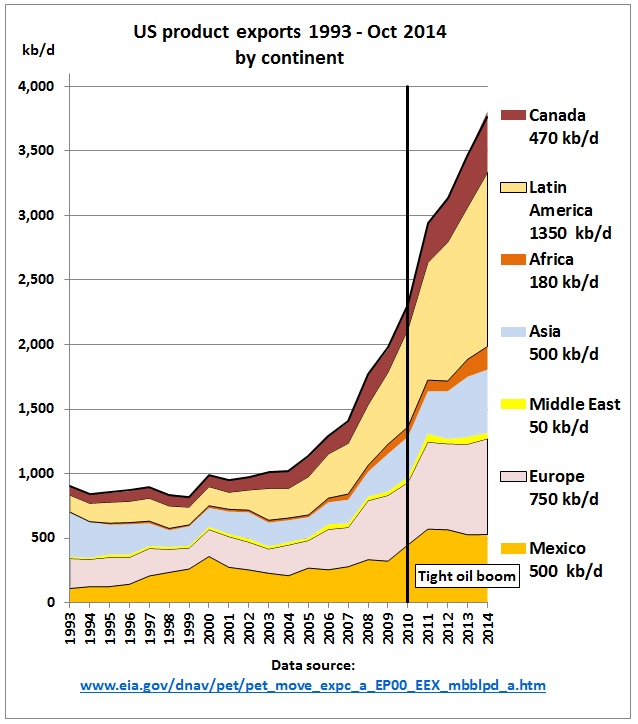
Fig 2: US product exports by continent
One quarter of exports goes to the neighbouring countries Canada (+33% pa) and Mexico (+13% pa), a third to Latin America (+28% pa) and the rest mainly to Europe (+9% pa) and Asia (+ 14% pa). The following graph is from the EIA:
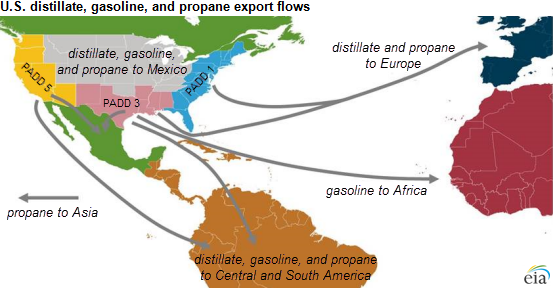
Fig 3: US export flows
http://www.eia.gov/todayinenergy/detail.cfm?id=15951
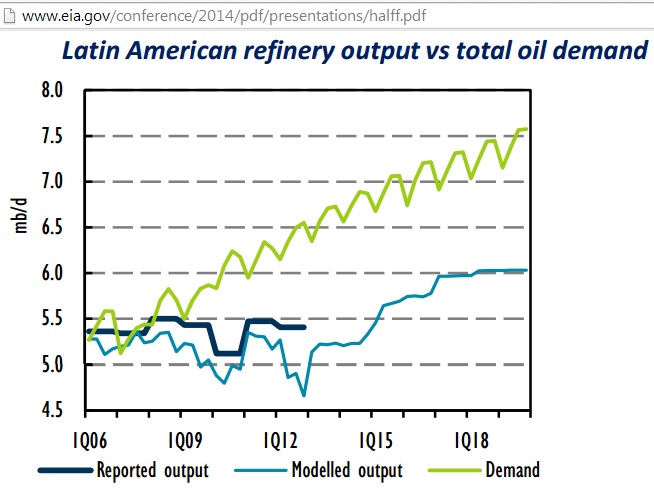
Fig 4: Latin American refinery output and oil demand (July 2014)
http://www.eia.gov/conference/2014/pdf/presentations/halff.pdf
Increasing US product exports to Latin America can be explained by a huge gap opening between refinery output and total oil demand.
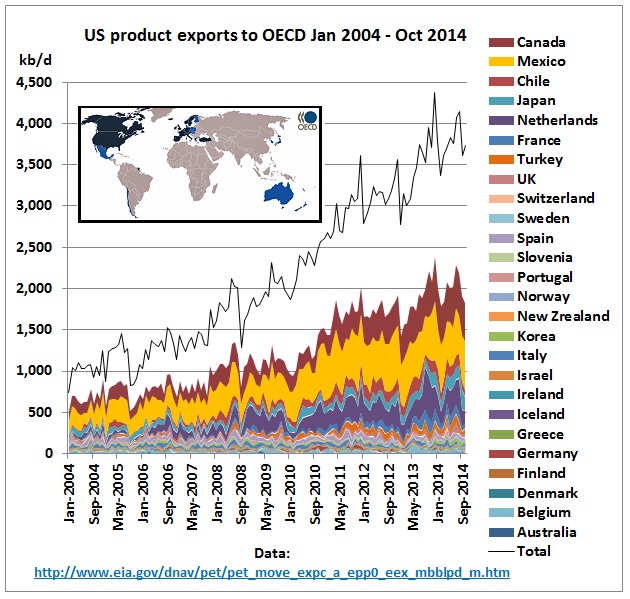
Fig 5: US product exports to OECD
US product exports to OECD countries have grown much less than the total to all countries. And within OECD most of the growth since 2010 was limited to neighbouring countries Canada and Mexico as well as a couple of other countries like Japan, Netherlands, France, Chile and Turkey.
(2) US product exports by fuel type
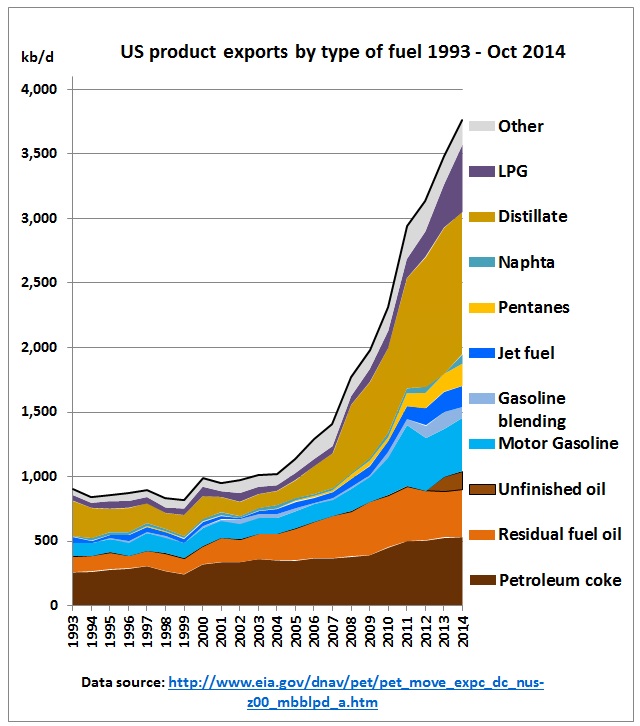
Fig 6: US product exports by fuel type
The main growth came from Diesel. Let’s have a look which countries imported it.
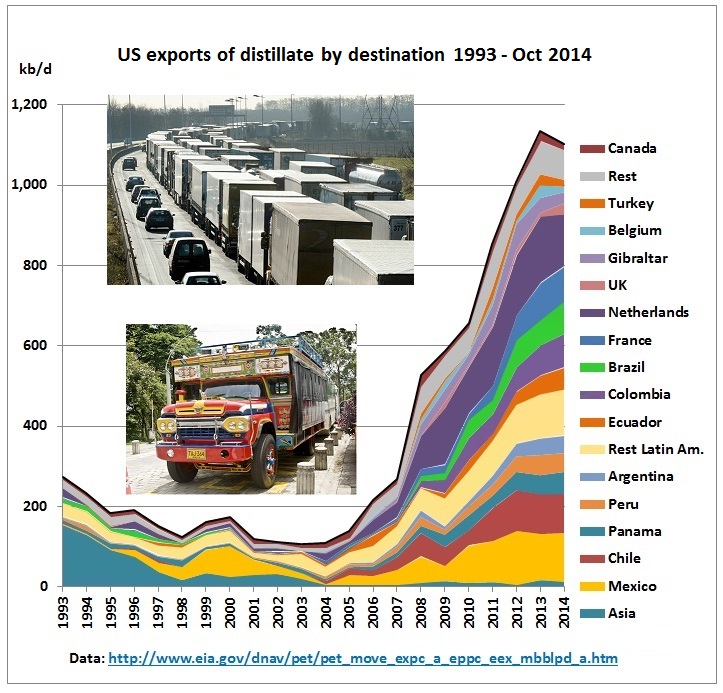
Fig 7: US distillate exports by destination country
Around 60% of distillate is exported to Latin America, 25% to Europe. It is interesting that almost nothing is going to the Asian market (maybe because of the Panama canal limitations – a widening project is under way).
But look at the increasing, dirty business of petroleum coke.
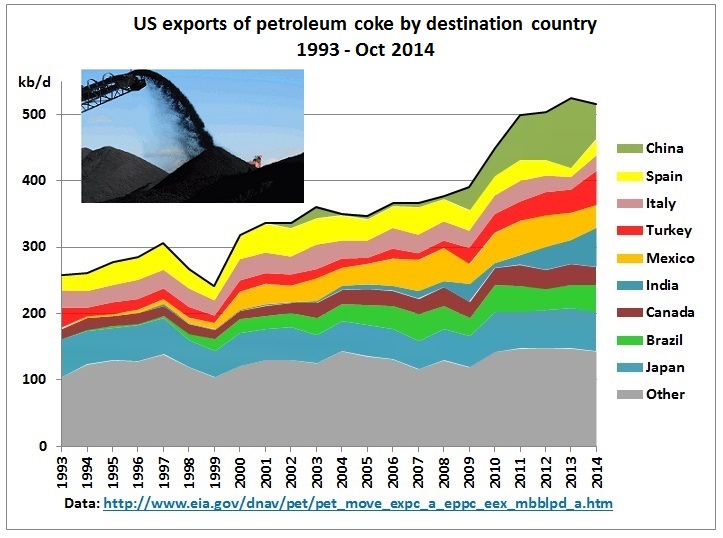
Fig 8: US exports of petcoke
http://www.eia.gov/dnav/pet/pet_move_neti_a_EPPC_IMN_mbblpd_a.htm
Note that coke is a heavy metal contaminated waste product of refining, especially from Canadian tar sands with a high content of carbon. It is burned in power plants with a high level of soot and green-house gases. It is not clear why EIA includes this in liquid fuel statistics.
Petroleum coke piles worry Midwesterners
Nov 2013
http://www.japantimes.co.jp/news/2013/11/29/business/petroleum-coke-piles-worry-midwesterners/#.VMNw4P6UcXs
Petcoke cloud from storm July 27 2013
Storm blowing through Detroit/ Windsor area blows a huge cloud of petcoke dust over the river from Detroit pile to Windsor
https://www.youtube.com/watch?v=35cIPgOLt3g
(3) US net product exports
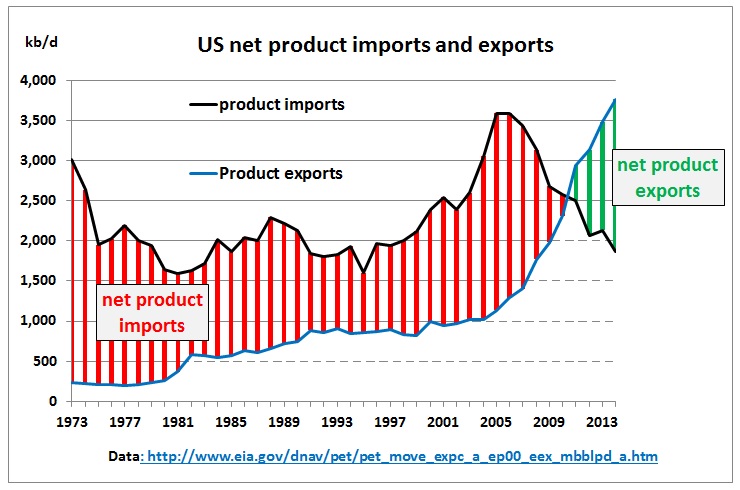
Fig 9: US product imports vs exports
US net product exports have been increasing while imports peaked in 2005 and have declined since. Net imports turned into net exports in 2011, coinciding with the beginning of the tight oil boom.
(4) US net product imports/exports by country
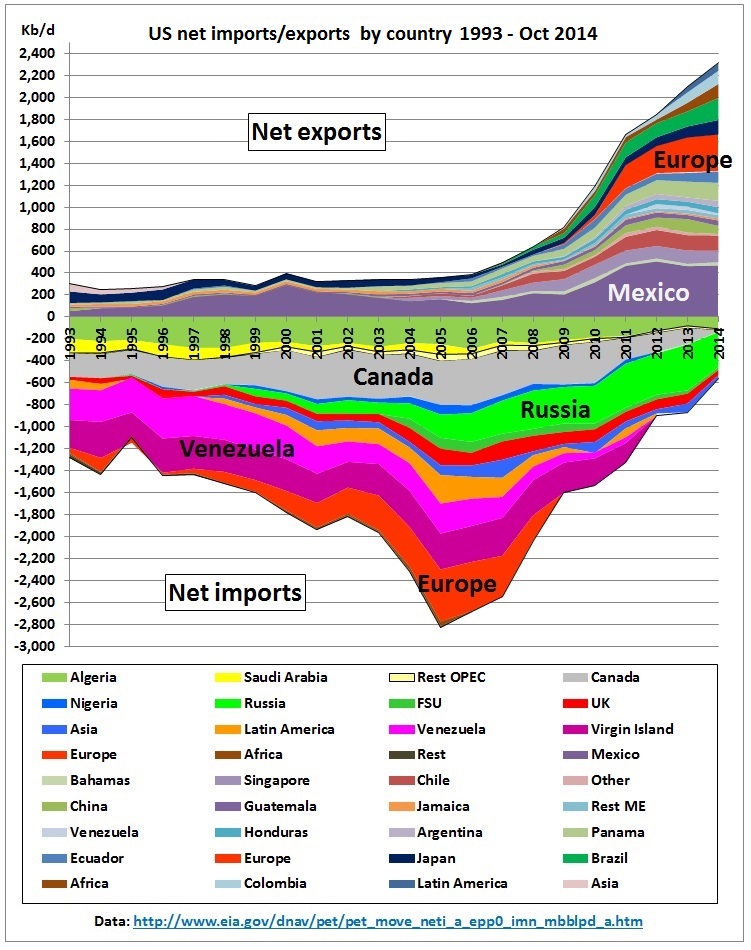
Fig 10 US net product imports (below x-axis) and exports (above x-axis)
While Fig 9 shows the net product imported/ exports from and to all countries together, Fig 10 shows the net balance for each country, stacked from imports to exports. Net product imports have petered out with the exception of Russia. So the potential for further import reductions is limited to that country. On the net export side about half of the exports are flat. An example is Mexico
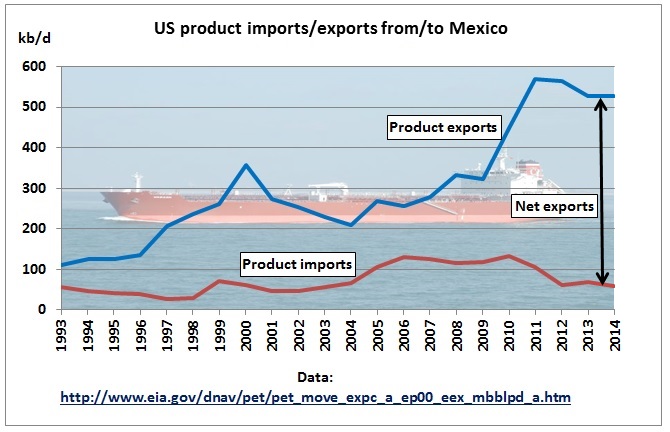
Fig 11: US product imports and exports to/from Mexico
There are basically only 6 growth areas remaining: Europe (but growth rates have been declining), Japan (LPG), Brazil (Diesel, LPG), Colombia, rest of Latin America and Africa. No wonder that US product export growth to Europe slowed down. Take the example of Germany, a car crazy country:
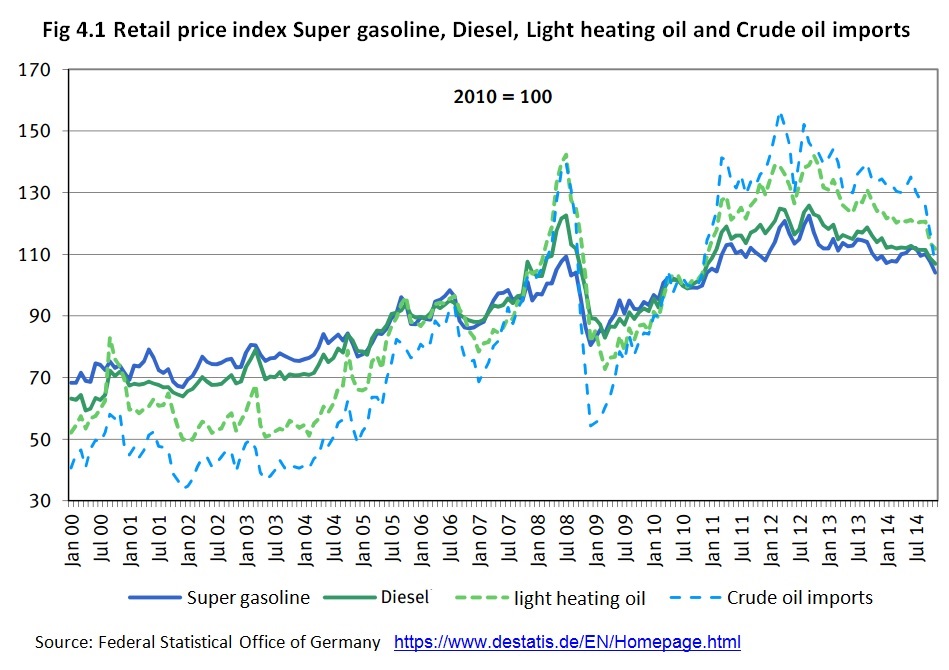
Fig 12: German retail price index for fuels and crude imports
Just as the tight oil boom started retail gasoline and diesel prices climbed steadily to record levels and stayed there for 4 long years.
Summary and conclusion:
The US tight oil boom accelerated growth of US petroleum product exports which had already started in 2005, the year in which global crude oil production began to peak – while the tight oil boom took off 5 years later in 2010. Most of the growth comes from Diesel exports to Latin America. However, the export boom cannot continue for ever. 40% of product exports did not increase since 2011
Related articles:
13/1/2015
Tight oil boom can explain only part of drop in US oil product imports
http://crudeoilpeak.info/tight-oil-boom-can-explain-only-part-of-drop-in-us-oil-product-imports
3/12/2014
US crude imports from Non-OPEC countries peaked 10 years before tight oil boom
http://crudeoilpeak.info/us-crude-imports-from-non-opec-countries-peaked-10-years-before-tight-oil-boom
6/11/2014
US oil dependency on Middle East has hardly changed since 2007
http://crudeoilpeak.info/us-oil-dependency-on-middle-east-has-hardly-changed-since-2007