The International Energy Agency’s Medium Term Oil Market Report 2015 included an interesting graph showing changes in US and Russian oil production for the next 5 years:
IEA MTOMR February 2015
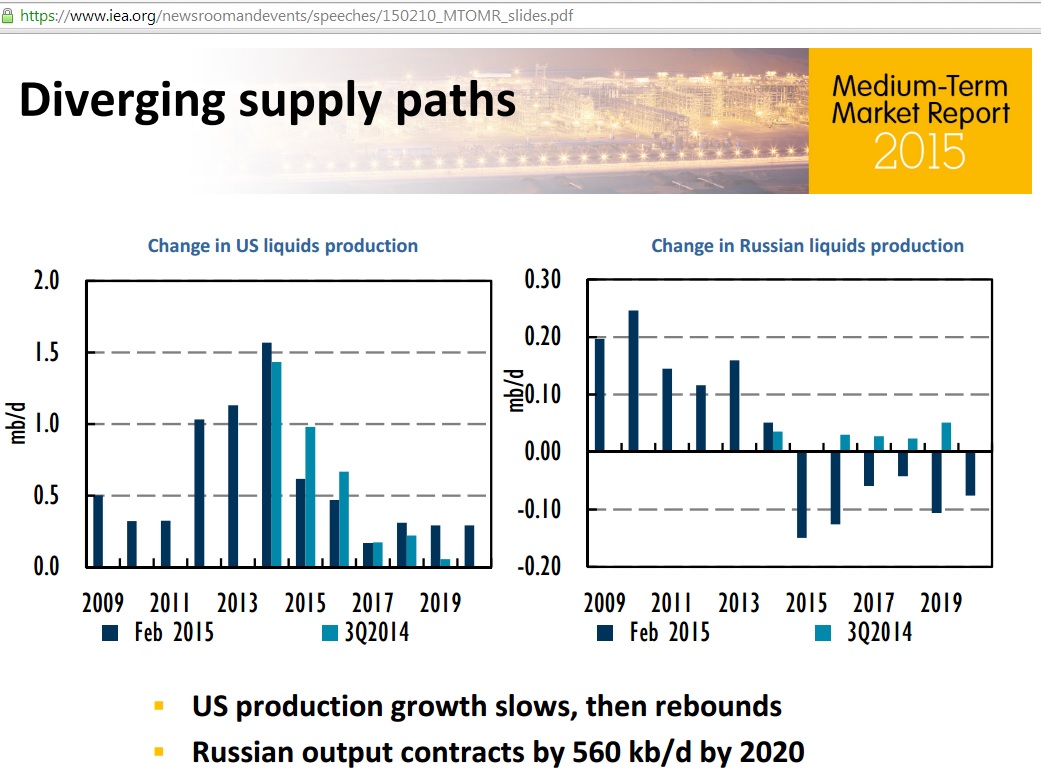 Fig 1: US and Russian oil production changes 2009-2020
https://www.iea.org/newsroomandevents/speeches/150210_MTOMR_slides.pdf
The light blue columns show forecasts done in the 3rdquarter 2014, the dark blue columns those done in February 2015. US growth is seen to decline to a meagre 160 kb/d by 2017. That is plausible given the high decline rates in tight oil fields In the 3 following years 1918-2020 the IEA assumes US growth to be 300 kb/d. That of course is pure speculation. It would require the kind of high oil prices which have killed demand. In all likelihood, QE4 would also be needed which in turn would send the US$ down.
Implied US production graph
Let’s put the changes from Fig 1 into a production graph 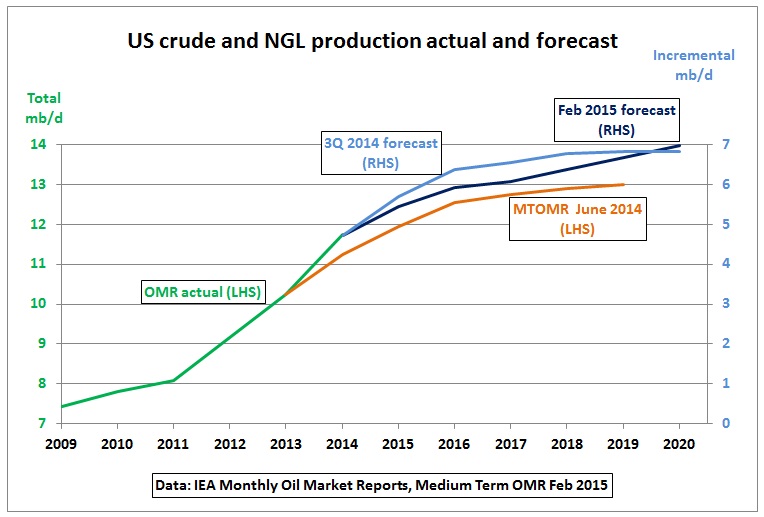
Fig 2: US C&C and NGL production with 3 forecasts
The green line shows actual production up to 2014. Then the changes are added. The light blue line is the 3rd quarter 2014 forecast (when oil prices were still around the $100 mark), peaking by the end of the decade. It was obviously arrived at by shifting the earlier MTOMR 2014 (brown line) up by around 1 mb/d to allow for a higher actual production during the course of 2014. The dark blue forecast done in Feb 2015 (when oil prices had dropped to $50) depicts slower growth, but no peaking. Remember that the IEA prefers to show growth because its member states want it that way.
This was last year’s MTOMR:
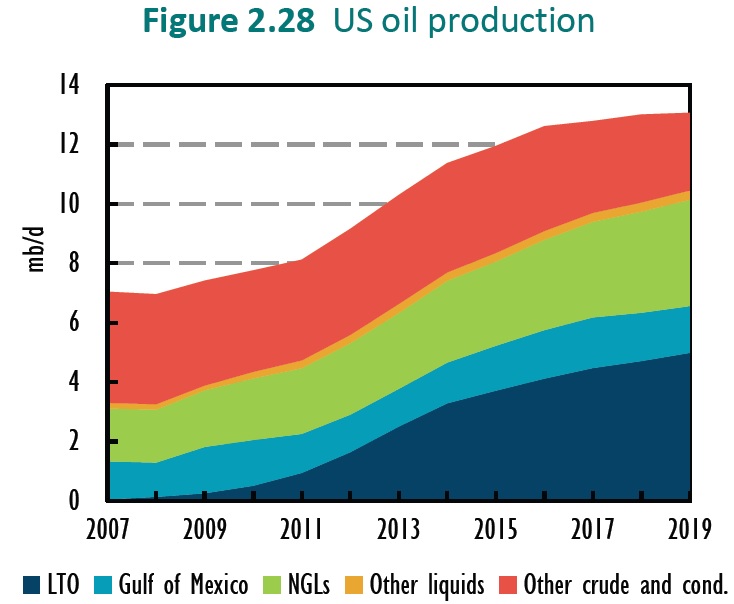
Fig 3: IEA MTOMR June 2014 (p 80)
Note the increasing volumes of NGLs (natural gas liquids like ethane, butane and propane) which also depend on future production of wet gas. So let’s put the NGLs from Fig 3 into Fig 2: 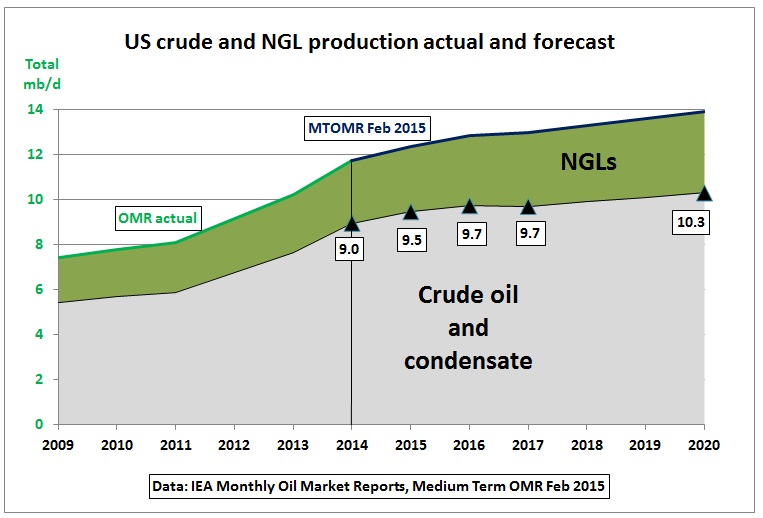
Fig 4: US crude oil and NGLs IEA forecast Feb 2015
Crude oil and condensate, most important as refinery input, is shown to grow less than the total oil production.
EIA forecast January 2015
For comparison, this is a 2-year forecast from the Energy Information Administration: 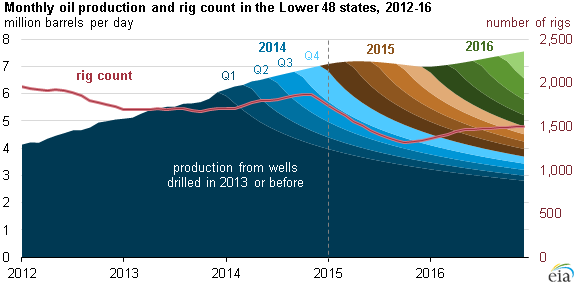
Fig 5: US oil production in lower 48 states 2012-2016
Source: U.S. Energy Information Administration, January Short-Term Energy Outlook Note: Graph does not include production from Alaska and the Federal Gulf of Mexico. http://www.eia.gov/todayinenergy/detail.cfm?id=19711
Fig 5 shows the quarterly additions stacked on legacy production. It demonstrates the real problem of this oil supply system in which production profiles are getting steeper and steeper. In 2014, annual decline in existing wells was 2 mb/d (34%!), in 2015 it will be 2.4 mb/d. The graph also shows the number of rigs (for both oil and gas) but in the meantime the drop since Oct 2014 has increased. The oil rig count end February was down by almost 40% 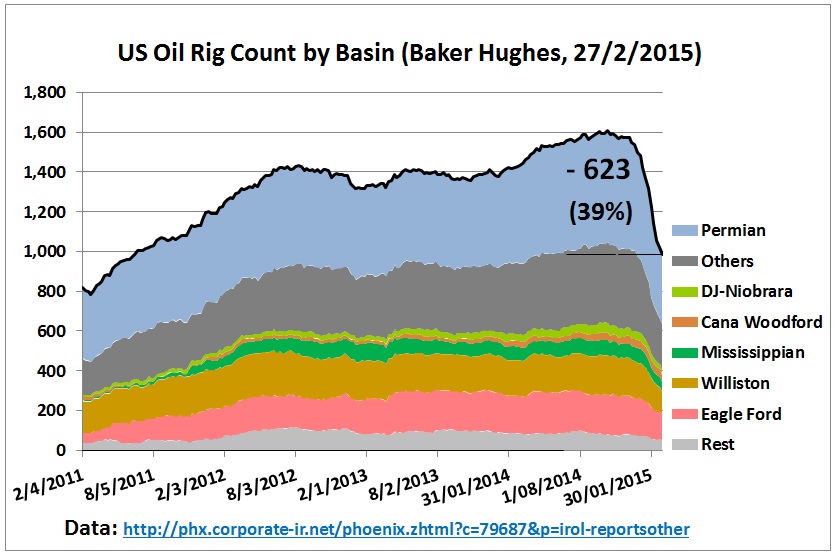
Fig 6: US drilling rig count as of 27/2/2015
http://phx.corporate-ir.net/phoenix.zhtml?c=79687&p=irol-reportsother
Fig 5 excludes Alaska and the Gulf of Mexico (1.96 kb/d in 1Q 2015) so let’s have a look at their historic production to see the difference to shale oil: 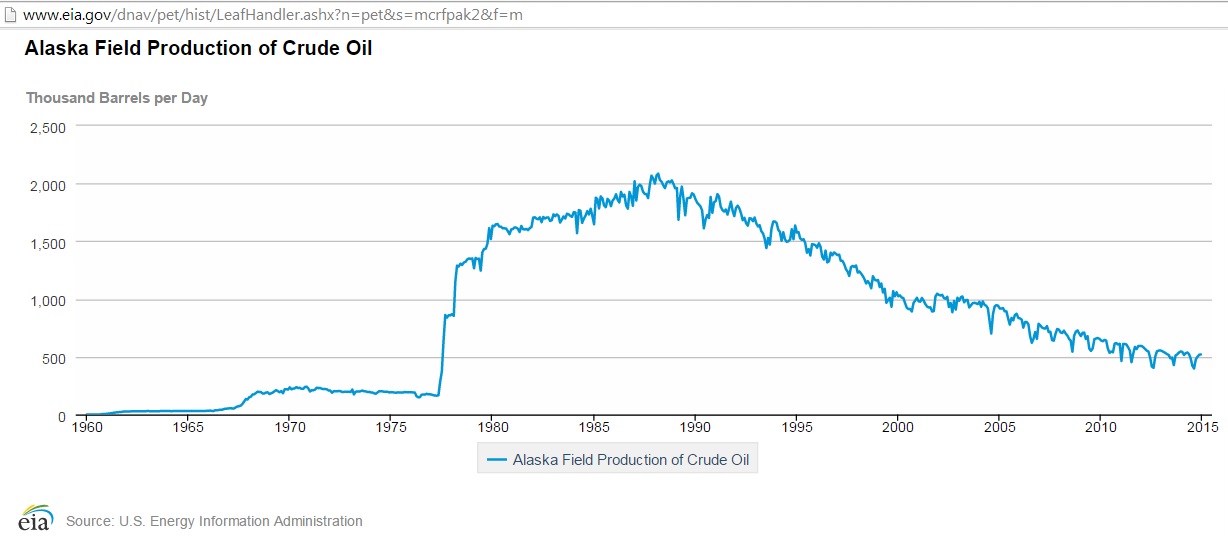
Fig 7: Alaska crude oil production
http://www.eia.gov/dnav/pet/hist/LeafHandler.ashx?n=pet&s=mcrfpak2&f=m
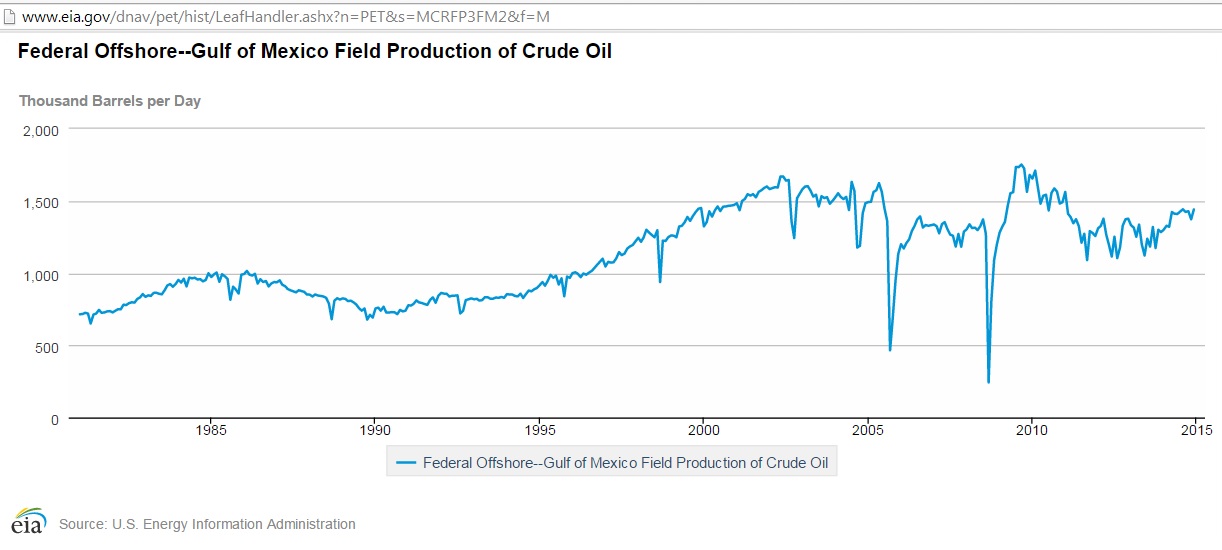
Fig 8: GOM crude oil production http://www.eia.gov/dnav/pet/hist/LeafHandler.ashx?n=PET&s=MCRFP3FM2&f=M
The graphs speak for themselves. EIA’s Short Term Energy Outlook has Alaskan oil declining by 30 kb/d and GOM increasing by 150 kb/d between 1Q 2015 and 4Q 2016, for a total of just 120 kb/d (p 34) http://www.eia.gov/forecasts/steo/
Comparison EIA – IEA
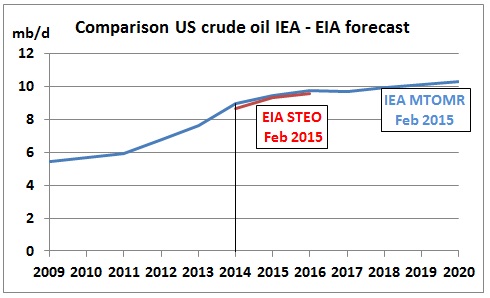
Fig 9: Comparison EIA – IEA crude oil forecast
The numbers from the EIA are marginally lower by 200-300 kb/d. Most importantly, the trend of slowing growth is the same.
US tight oil reserves
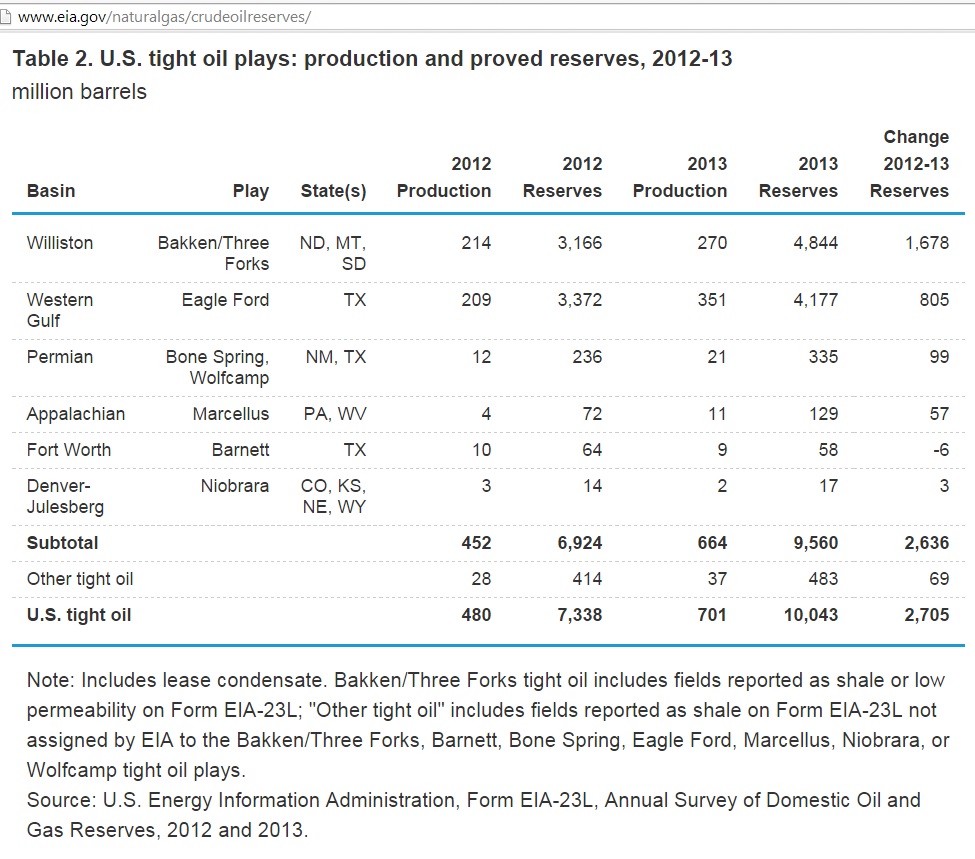
Fig 9: US tight oil reserves as published in Dec 2014
http://www.eia.gov/naturalgas/crudeoilreserves/
To keep everything in perspective US tight oil proved (P1) reserves end 2013 were just 10 Gb, approximately 4 months of global oil consumption. The reserve is produced at a very high 7% pa
Russian oil peak
Back to the IEA report where the production changes from Fig 1 have been used to arrive at a production graph: 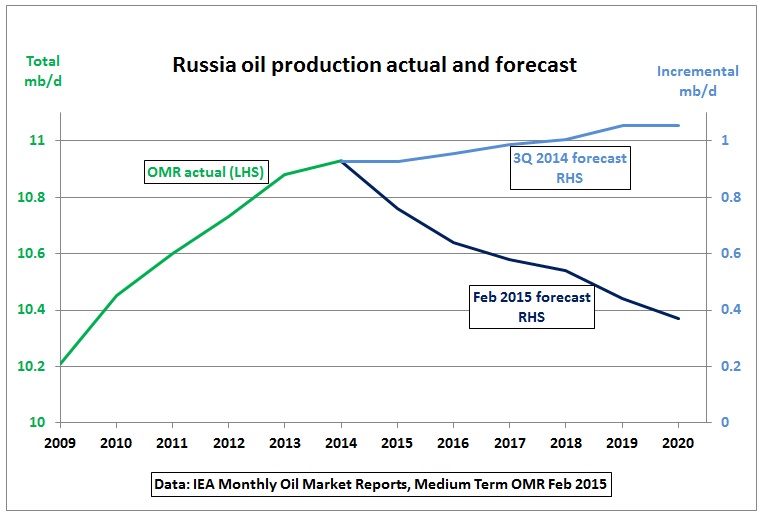
Fig 10: Russian oil production from IEA’s MTOMR Feb 2015
Note Fig 10 is not zero scaled and has a totally different scale compared to the US production graph (Fig 2). The peak is actually quite flat. The decline is no surprise as the Russian Ministry of Finance warned in July last year that oil production would fall in 2016.
http://crudeoilpeak.info/russia-peak
Conclusion:
Russia is at peak. US production growth is going to slow down. Whenever the 2nd (and last) US peak happens, that will be the global peak, barring eternal peace breaks out in the Middle East and Iraq can produce 6 mb/d by 2020.
Related post: 14/8/2014
IEA report implies US crude oil production may start to peak in 2016
http://crudeoilpeak.info/iea-report-implies-us-crude-production-may-start-to-peak-2016
Addendum
US oil production IEA Medium Term Oil Market Report Feb 2015
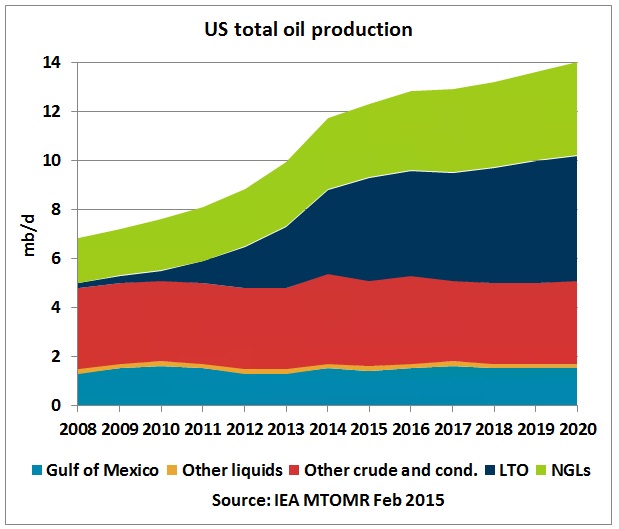
The graph from the video presentation (link below) is re-stacked so that NGLs are on top of crude and light tight oil is on top of the rest of crude (which is flat)
From this video:
http://csis.org/multimedia/video-international-energy-agencys-medium-term-oil-market-report-2015