Skip to content

Crude Oil Peak

Menu
  • Home
    • About
    • Disclaimer
  • OECD imports
    • France
    • Germany
    • Italy
    • Japan oil imports
    • OECD Europe
    • OECD Pacific
    • South Korea
    • UK
    • US Imports
  • Australian graphs
    • Australian electricity supply graphs
    • Australian crude oil production
    • Australian crude oil reserves
    • Oil import dependency
    • Oil and fuel imports
    • ULP prices
    • Industry stocks
    • End use of oil
    • WA crude oil
    • WA domestic gas
    • East coast conventional gas
    • Geoscience Australia March 2010
    • Geoscience Australia 2005/2006
    • Gippsland
    • LPG
    • Petrol rationing in WW2
  • Oil reserves
    • OPEC paper barrels
    • Kuwait Reserves
    • Strategic Oil Reserve
  • Global Peak
    • Algeria peak
    • Angola peak oil
    • Argentina peak
    • Azerbaijan peak
    • Brazil
    • Brunei peak
    • Canada and tar sands
    • Caspian peak
    • China Peak Oil
    • Deepwater peak
    • Egypt
    • Gabon peak
    • India peak oil
    • Indonesia peak
    • Iran Peak
    • Libya peak oil
    • Malaysia-peak
    • Mexico peak
    • Norway peak oil
    • Qatar peak
    • Russia peak
    • Saudi Arabia export peak
    • Sudan Peak
    • Syria
    • Tunesia
    • UAE peak
    • UK Peak
    • US Peak
    • Vietnam peak
    • Venezuela peak
    • Yemen
  • Energy Transitions
    • Germany energy transition
    • Japan Energy Transition
    • UK Energy Transition
    • US
  • Fuel Shortages
    • China Fuel Shortages
    • Egypt Diesel shortages
    • India petrol price hike
    • Malawi fuel shortage
    • Nepal
    • Nigeria fuel shortage
    • Pakistan petrol shortage
    • Russia
    • Tanzania fuel shortage
    • Uganda Fuel Shortage
    • Yemen fuel shortages
  • I told you so
    • Top Ryde Shopping Centre
    • North South Bypass Tunnel (Clem7) Brisbane
    • Airportlink Brisbane
    • Cross City Tunnel
    • Lane Cove Tunnel
    • Too late for Metro tunnels
    • Australian car manufacturing closing down
    • How the first phase of peak oil brought Virgin Australia into minus after 2008
  • Solutions
    • Night trains
    • Electric Rail on Freeways
    • LNG locomotive conversion
    • Electric trolley buses
    • Walk to school
  • Oil crises
    • Oil crisis 1973
    • My experience oil crisis 1979
    • Historical Oil Disruptions
  • Food and Oil
    • Farm Costs Australia
    • Food crises and political instability
  • Global warming
    • Storms of my Grandchildren
    • Extreme weather events
    • Global warming and petrol lines
    • Compensation claims from global warming damage
    • Sea level rises
    • Why coal seam gas will not reduce CO2 emissions
Menu

Mexico peak

Update with 2023 data

Update July 2017

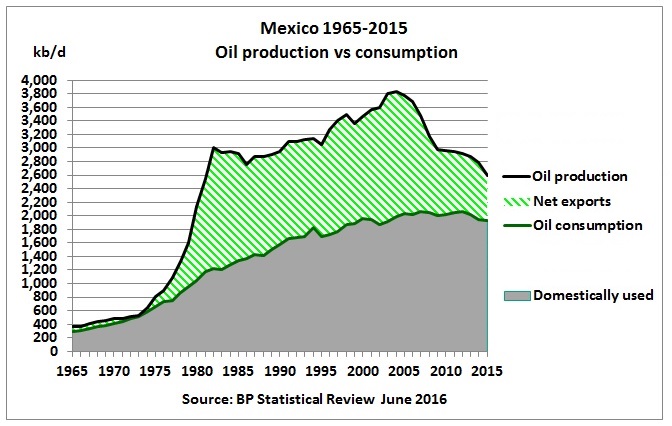
Using data from BP Statistical Review
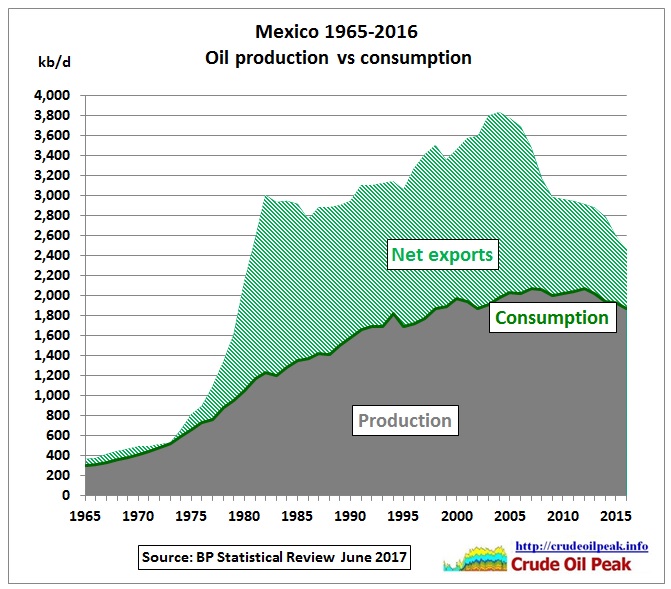
Mexico_oil_production_vs_consumption_1965-2016

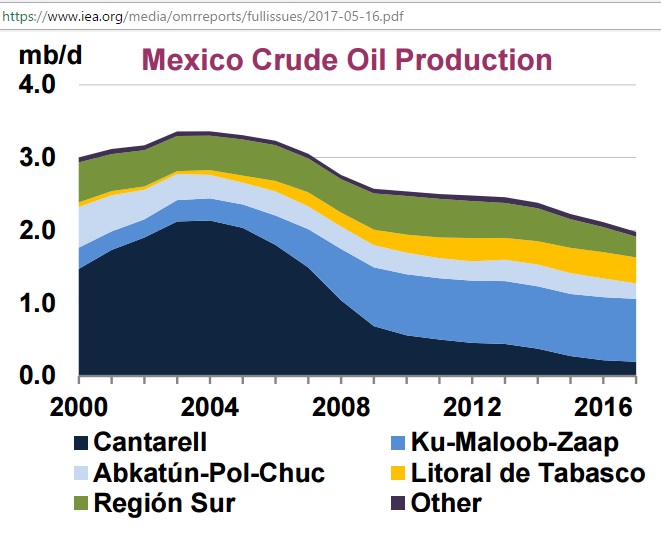
Update May 2017

Mexico_crude_production_2000-16
https://www.iea.org/media/omrreports/fullissues/2017-05-16.pdf

Update January 2017
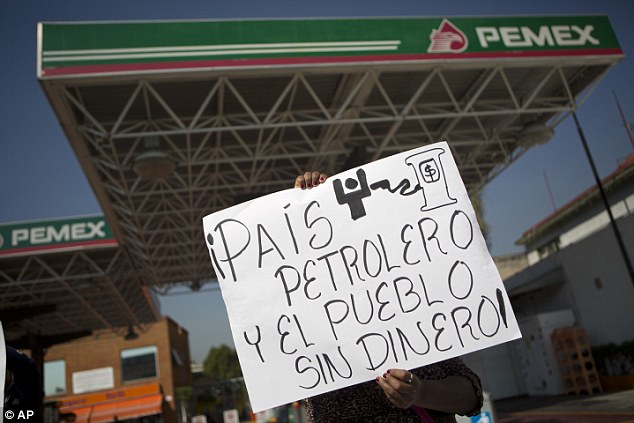
pais_petrolero_sin_dinero_jan2017

Looting and riots erupt in Mexico as gas prices spike 20 percent in one weekend as the government stops regulating oil prices
5/1/2017
http://www.dailymail.co.uk/news/article-4089408/Mexican-president-defends-gas-price-hike-protests-spread.html
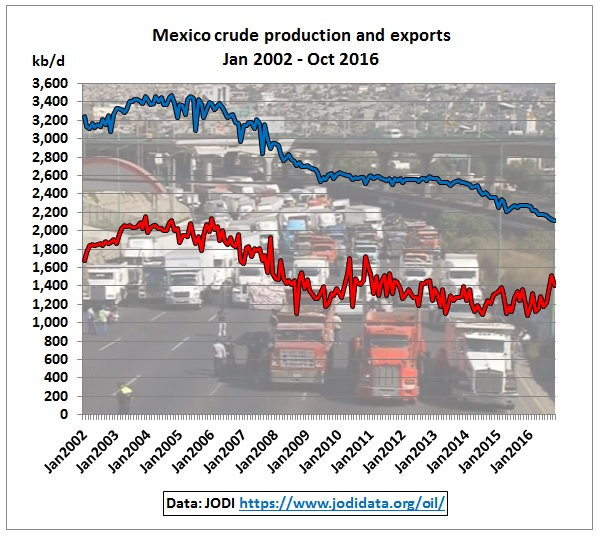
mexico_crude_production_exports_jodi_2002-oct2016

https://www.jodidata.org/oil/

October 2016

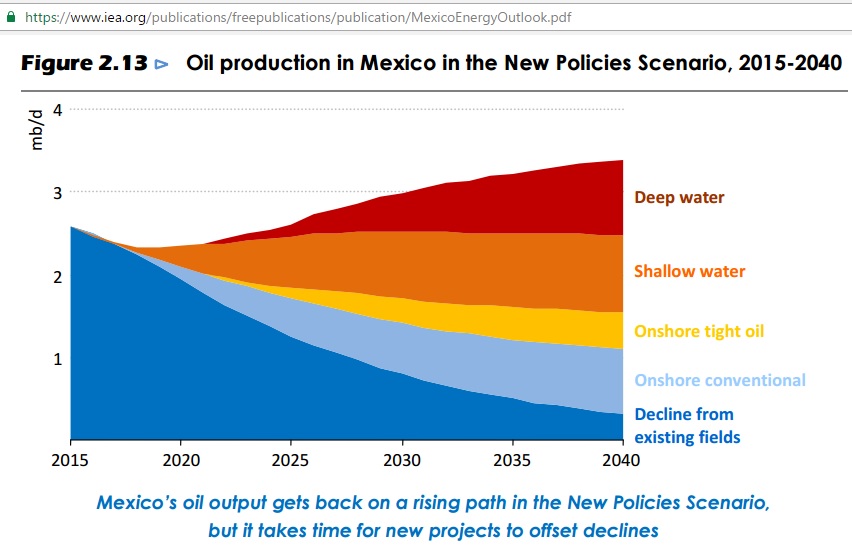
mexico_iea_oil_production_scenerio_2015-2040

https://www.iea.org/publications/freepublications/publication/MexicoEnergyOutlook.pdf

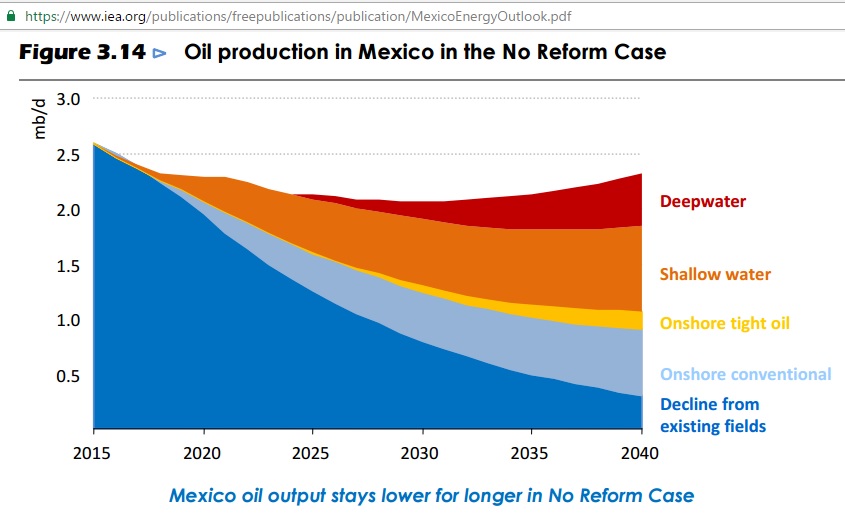
This Scenario is much more optimistic than the WEO 2014 (Fig 3.13 below). It assumes that Mexico’s oil industry reform is fully implemented.

Pemex reform bills were introduced in August 2014

https://www.brookings.edu/articles/mexicos-energy-reforms-become-law/
mexico_iea_oil_production_no_reform_2015-2040

The IEA explains:

“The difference in projected oil production between the New Policies Scenario and the No Reform Case widens steadily over the period to 2040, by which time it exceeds 1 mb/d (2.3 mb/d versus the 3.4 mb/d reached in the New Policies Scenario) (Figure 3.14). The divergent trajectories take some time to become apparent, reflecting the lead times of the projects that are awarded in the New Policies Scenario but that fail to proceed in the No Reform Case. The key difference between the two trajectories is the amount of capital available for the upstream investment. In the New Policies Scenario, investment (and technology) comes from many sources. In the No Reform Case, the more limited capital available to PEMEX (especially in the current period of lower oil prices) needs to be spread over a wide range of assets, including capital-intensive deepwater projects. The company continues to do a commendable job (as it has done, for example, in exploring the deepwater Perdido area in the northern Gulf of Mexico), but the amount of upstream activity is significantly lower.”

Leftist Candidate Could Threaten Pemex Reforms.
12/8/2016
“A firebrand leftist who twice narrowly missed becoming Mexico’s president is riding high with a fresh bid for election in 2018, vowing to upend a landmark energy sector opening championed by President Enrique Pena Nieto”
http://www.maritime-executive.com/article/leftist-candidate-could-threaten-pemex-reforms

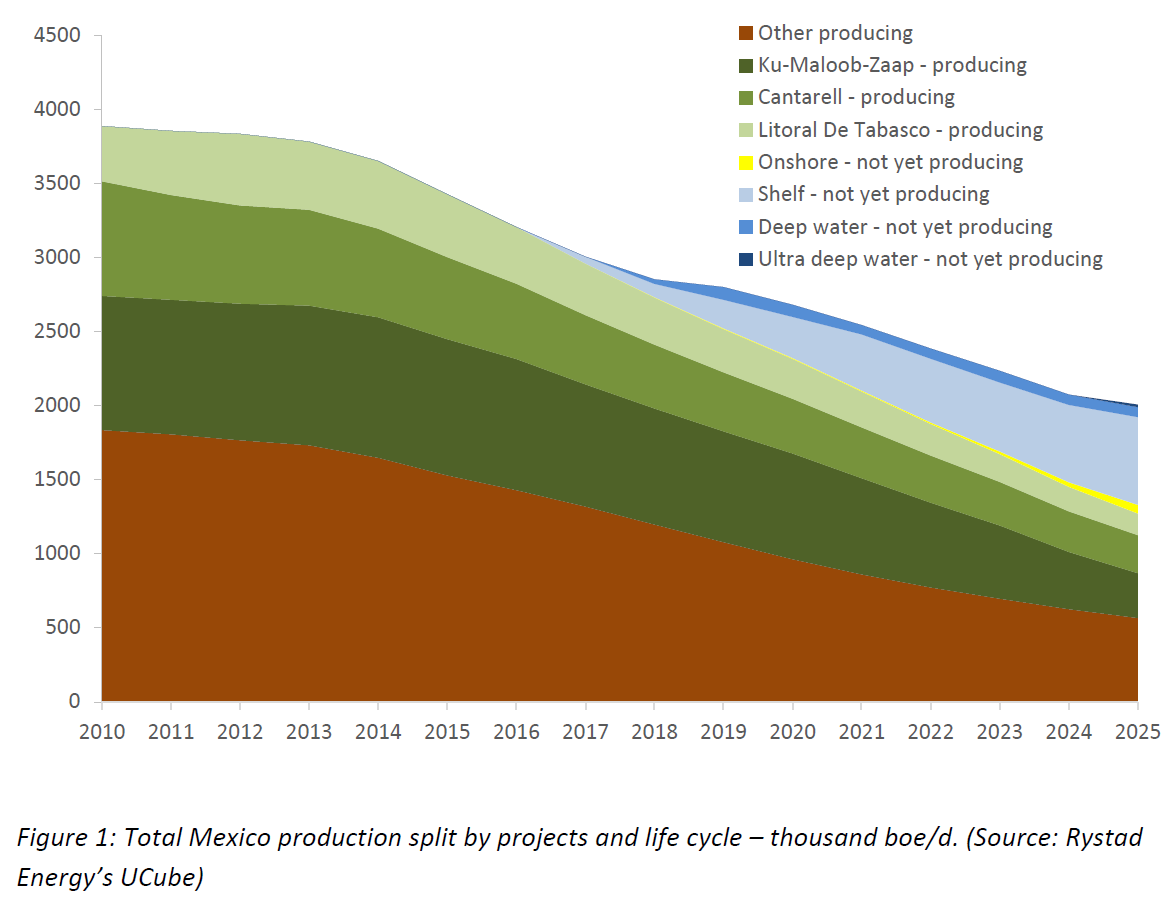
Both IEA scenarios are quite different from the Rystad graph shown below. The only agreement is on decline in producing fields.

June 2016
mexico_oil_production_consumption_1965_2015

March 2016

Estimate from Rystad

“Figure 1 shows Mexico’s production, split by projects, life cycle and onshore/offshore from 2010 to 2025. Production is in decline, a trend driven mainly by the country’s supergiant offshore oil fields, Ku-Maloob-Zaap, Cantarell and Litoral De Tabasco. From 2016 and onwards, production is expected to continue declining, but at a slower pace, thanks to substantial contribution from the new discoveries in the Litoral De Tabasco (Xikin, Esah and Batsil) and Cantarell (Cheek), infill drilling at Ku as well as the deepwater project Lakach. ”
mexico_2010-2015_rystadmar2016

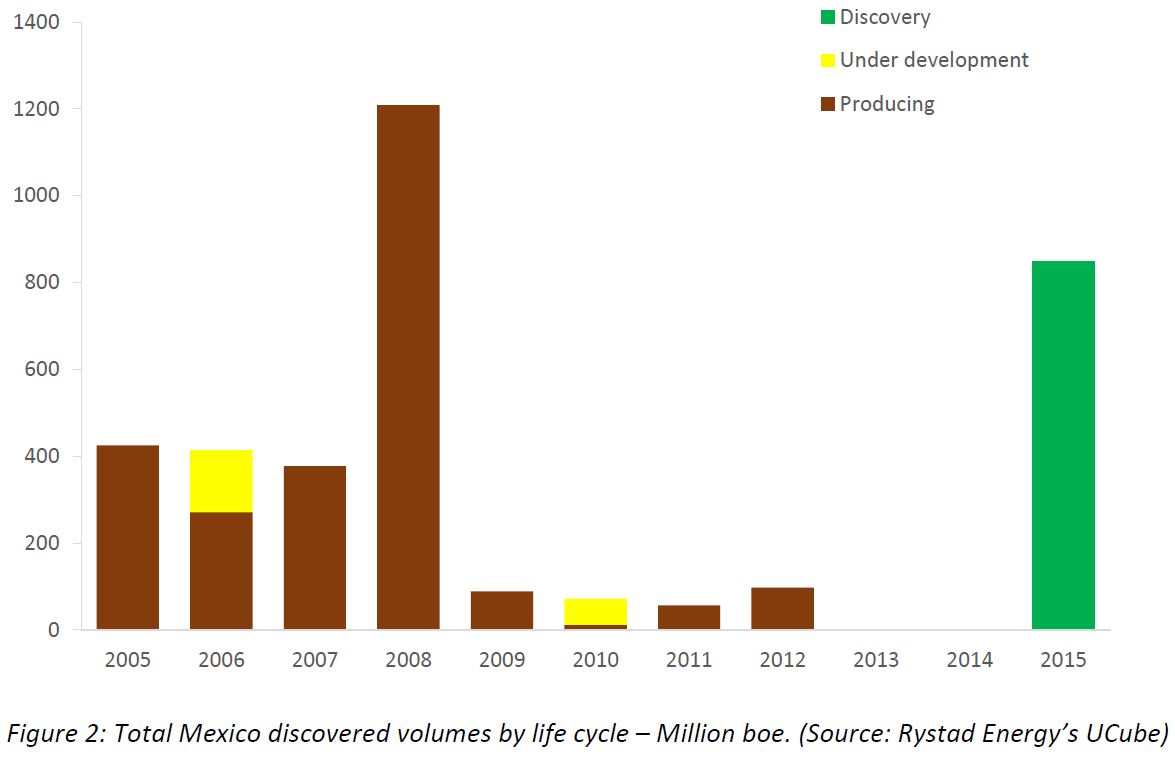
Figure 2 shows the discovered volumes for Mexico from 2005 to 2015. The year with the highest discovered volumes in the last decade was 2008. Two major discoveries, Ayatsil-Tekel and Tsimin (Litoral De Tabasco), make up around 60% of the 2008 discovered resources. After three years of low exploration success, Pemex discovered the deep water Kunah, Trion and Puskon fields in 2012. None of these discoveries, however, are expected to be put into production before 2025 and are not considered to be commercial at the current oil price forecast (and are not shown in Figure 2).
mexico_discoveries_2005-2015_rystadmar2016

http://www.rystadenergy.com/NewsEvents/PressReleases/are-mexicos-2015-discoveries-enough

January 2016
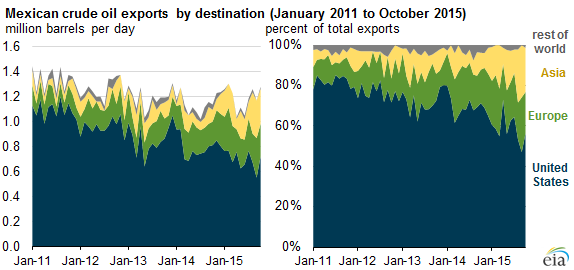
http://www.eia.gov/todayinenergy/detail.cfm?id=24112

November 2014
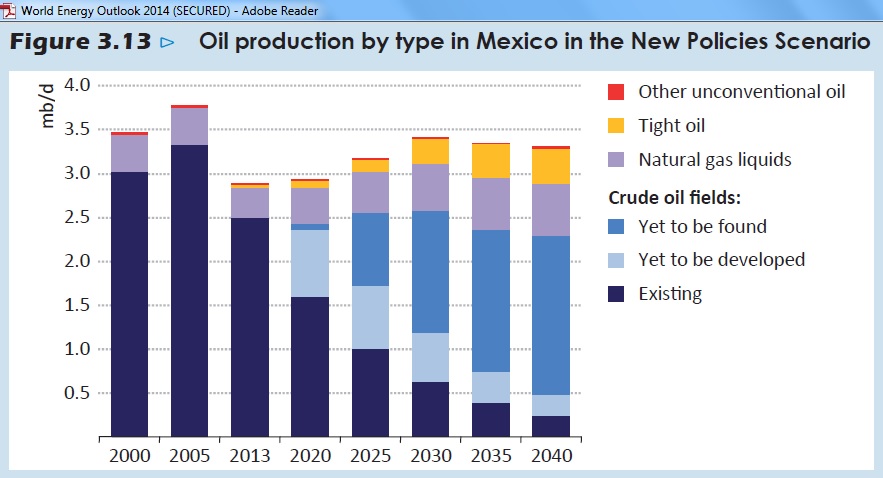
http://www.worldenergyoutlook.org/weo2014/

June 2014
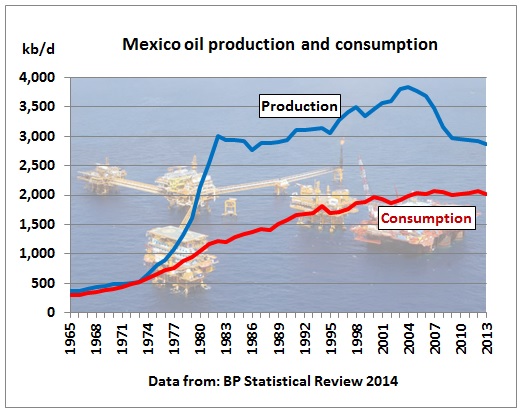
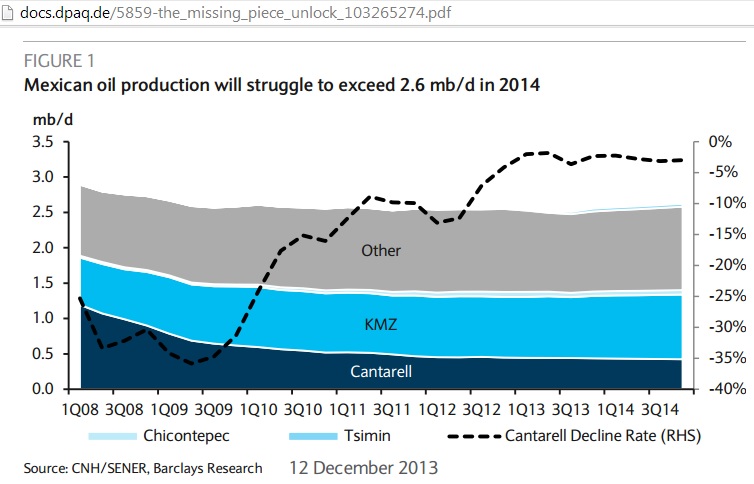
December 2013
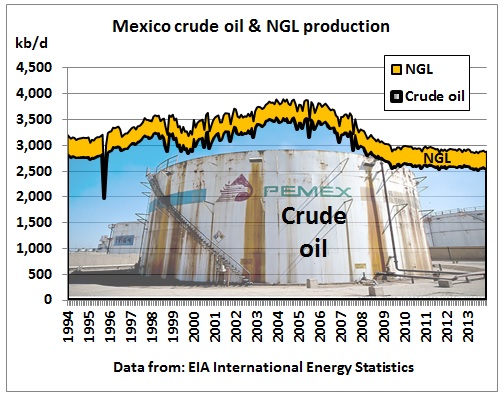
Data from here: http://www.eia.gov/cfapps/ipdbproject/iedindex3.cfm?
.
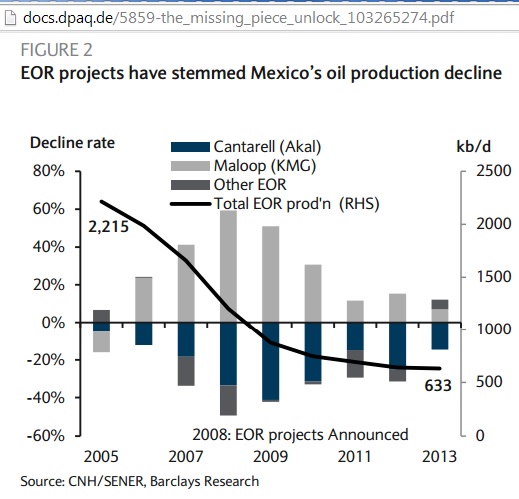
http://docs.dpaq.de/5859-the_missing_piece_unlock_103265274.pdf

June 2013
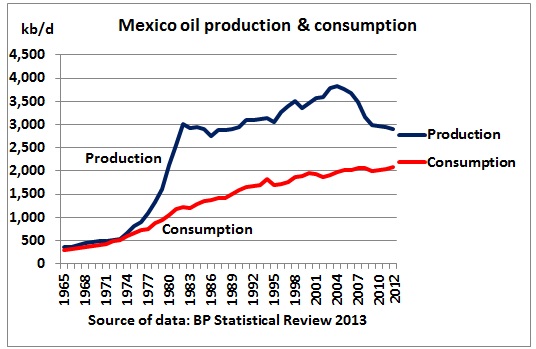
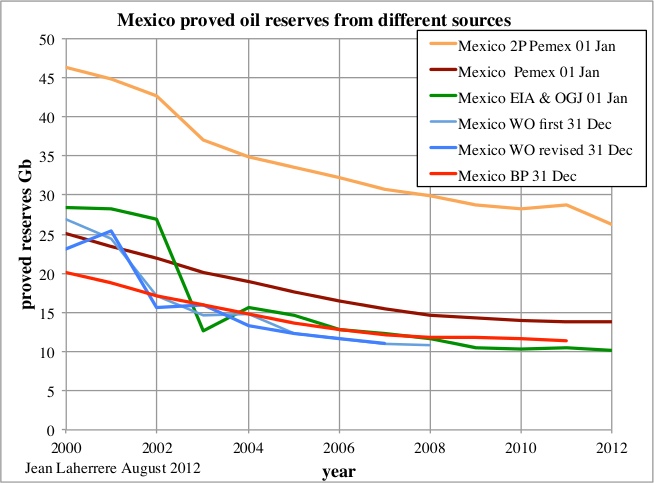
February 2012

Mexico: time for action
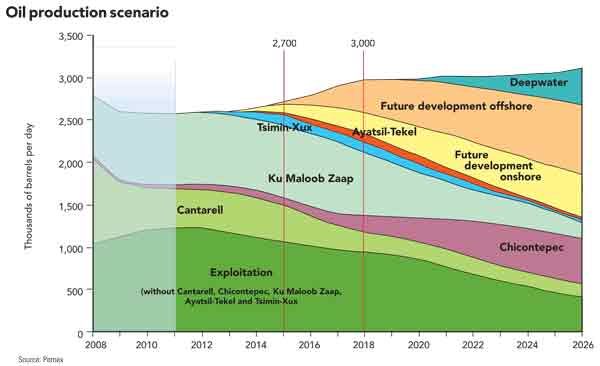
http://www.ogfj.com/articles/print/volume-9/issue-2/features/special-report/mexico-time-for-action.html

2010

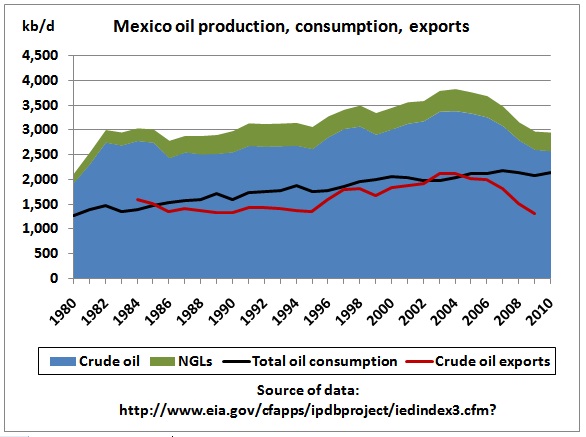
Crude oil exports declined by 800 Kb/d between 2004 amd 2009, mainly caused by the peaking of the Cantarell field
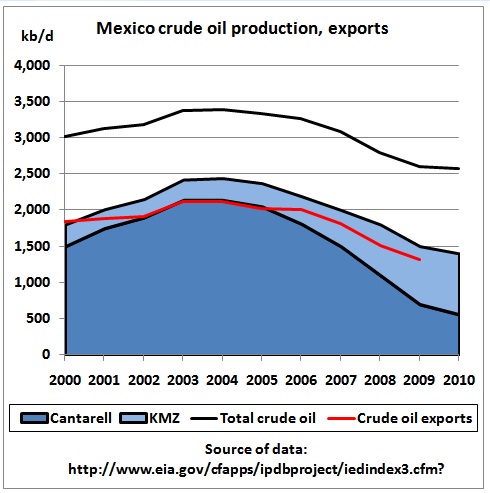
Source of data: http://www.eia.gov/cfapps/ipdbproject/iedindex3.cfm?
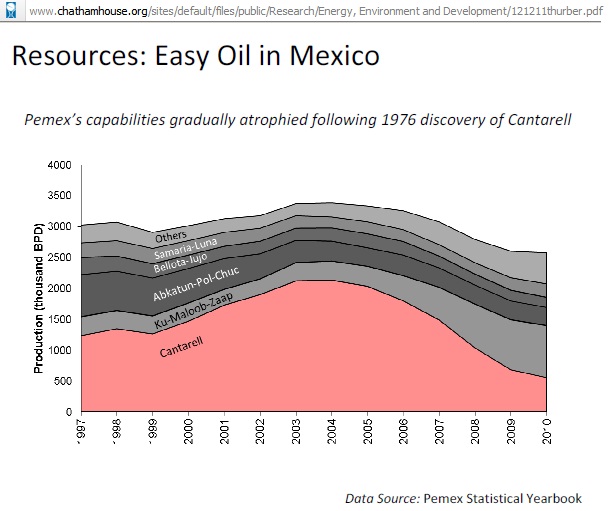
Heavy Maya crude, around 60% of total Mexican production is exported to the US which has the refining capacity for this oil. More details here:

http://www.eia.gov/cabs/Mexico/Full.html
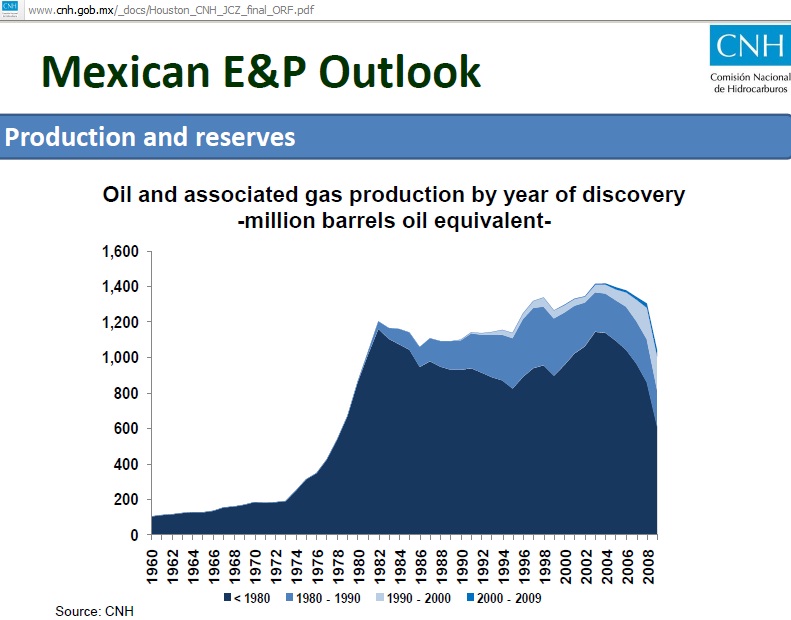
2009

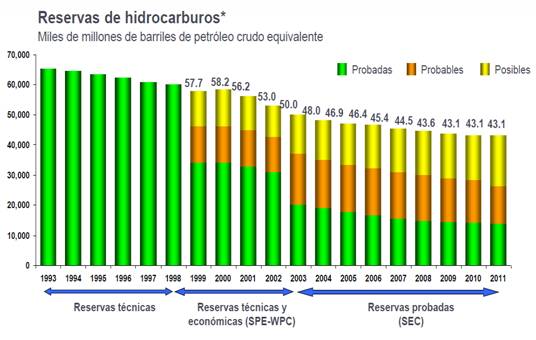
http://www.cnh.gob.mx/_docs/Houston_CNH_JCZ_final_ORF.pdf

http://geo-mexico.com/?p=6357

 From:  http://www.theoildrum.com/node/9547#more

Key data & graphs

  • Net oil importers
  • Oil Exports
  • Crude oil imports
  • Downloads
  • Latest Graphs
  • Oil price analysis
  • US drilling rig count
  • International drilling rig count
  • Australian fuel prices
  • Diary
  • International oil companies
  • US tight oil production
  • China peak oil
  • World liquids supply – demand balance
  • Tankers arriving and departing in Sydney
  • Australian oil and fuel imports

Latest posts

  • Australian jet fuel stock floating offshore while fuel prices are flying away
  • Australian Diesel imports in August dropped from high in May
  • First early hot summer day in spring 2026 and power prices spike at a whopping AUD 23k per MWh
  • Energy Minister Bowen firm in refusing Russian fuel imports but keeps options open for diesel imports from Russian dependent India
  • Australian Energy Minister Bowen downplays diesel supply risk after Saudi Arabia visit
  • Australia to expect less petrol and jet fuel deliveries in next 4 weeks as diesel economy guzzles along

Archives

©2026 Crude Oil Peak | Design: Newspaperly WordPress Theme