Currently lower oil prices due to a combination of increasing oil supplies and subdued demand come at a high cost to the environment and the climate. Additional oil supplies are exclusively from fracking tight oil in the US and from Canadian tar sands.
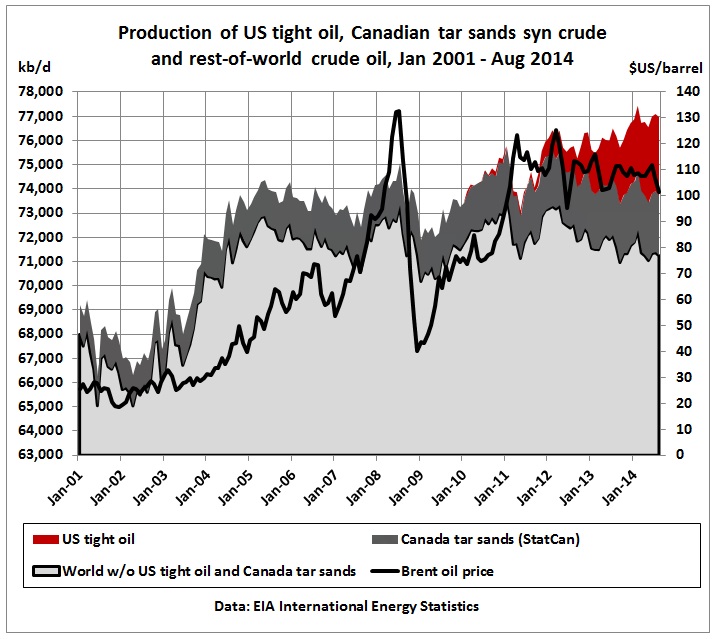
Fig 1: Production of US tight oil, Canadian tar sands and rest-of-world crude
The graph shows that crude oil production outside the US and Canada is on a bumpy plateau since 2005. In fact, after 2011, rest-of-world crude production declined like in 2005-2007:

Fig 2: Overlay of rest-of-world crude production 2005/07 and 2012/14 periods
Let’s have a more detailed look at the changes to crude oil production since 2001:
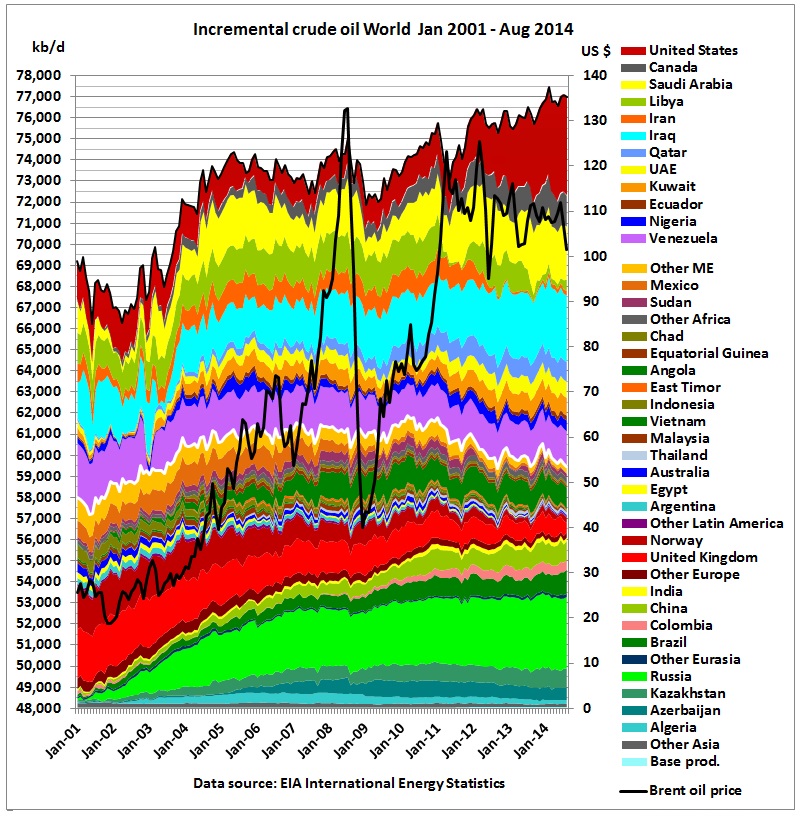
Fig 3: Incremental crude oil production Jan 2001 – Aug 2014
All data are from here: http://www.eia.gov/cfapps/ipdbproject/IEDIndex3.cfm
Incremental production is calculated as total crude production minus the minimum production in each country in the period under consideration, here from Jan 2001 to Aug 2014. The minimum is used instead of production in Jan 2001 to avoid negative values which cannot be stacked in a graph. (Base-production is the sum of all minimum production).
Therefore, countries with large changes in production show up as large areas. There are 2 types of these changes:
- Short-term (a couple of months ). Examples are Venezuela (strike in 2002/2003), Iraq (war in 2003) and Libya (war in 2011).
- Long-term (over many years). Examples are Russia, the North Sea and now the US
All countries under the white line (above “Other ME”) peaked in 2010. This contributed to the rest-of-world decline 2012-2014 from Fig 2.
Countries are stacked in following order:
1. Growing: the largest contribution came from Former Soviet Union countries, but Russia is now peaking as advised by the Russian Ministry of Finance in July 2014

Fig 4: Incremental FSU crude production
Note the kink in Russia’s curve in 2005. More details here:
https://crudeoilpeak.info/russia-peak
2. Long term decline e.g North Sea

Fig 5: North Sea decline
3. Peaked in the past
4. Countries with geopolitical risks and all other Middle East countries

Fig 6: Incremental crude oil production in Middle East
Increasing production in Iraq has been offset by a drop in Iranian production due to sanctions. The combined average Iran/Iraq production since mid 2008 was 6.4 mb/d
5. Canada and US tight oil

Fig 7: Incremental crude from North America
Other graphs

Fig 8: Incremental crude production in Asia
China is at peak and can hardly offset decline elsewhere in Asia

Fig 9: Incremental crude production in Africa
Africa peaked in 2008 and again in 2010. Even without the war in Libya Africa is in decline. Most serious is the situation in Egypt where oil consumption has exceeded production.

Fig 10: Incremental crude production in Latin America
Venezuela dominates the graph because of the sudden production drop during a strike in 2002/03 (thereby increasing production changes in this period). It is suspicious that Venezuelan production is being reported as unchanged since 2011. Growth in the last years has come from Brazil and Colombia.
Summary by continent

Fig 11: Incremental crude production by continent/region
In Fig 11 all country related incremental production is added for each continent.
The 4 continents Latin America, Asia, Eurasia and Europe are on a crude oil production plateau since mid 2004, at 30.3 mb/d with a standard deviation of 300 kb/d. A short production spike of 900 kb/d in 2010 was caused by the Chinese production peak shown in Fig 8.
We then have the African peak as described in Fig 9. with a production decline of 1.9 mb/d since end 2010. The Middle East did NOT offset this decline.
Finally, North America not only offset this decline but added another 1.8 mb/d over 3 years. Note that this production increase 2010-2014 did not match the huge global increase of 7 mb/d between 2002 and 2005 when oil prices doubled from $25 to $50.
Another doubling to $100 (and more) brought about only 25% of the pre-peak increase. Maybe the world doesn’t like such poor performance and refuses to buy this expensive oil.