The latest IMF Article IV consultation report on Saudi Arabia was published on 9 September 2015.
http://www.imf.org/external/country/sau/
Extract: Government spending has increased substantially in recent years. Consequently, the breakeven oil price rose to $106 a barrel in 2014 from $69 a barrel in 2010. As a result, with the large decline in oil prices, the fiscal deficit has increased sharply and is likely to remain high over the medium-term. These deficits will rapidly erode the fiscal buffers (in the form of government deposits and low public debt) that have been built over the past decade. http://www.imf.org/external/pubs/ft/scr/2015/cr15251.pdf
Let’s put this into some graphs. We start with the fiscal deficit first, then look at the external balance.
Expenditure
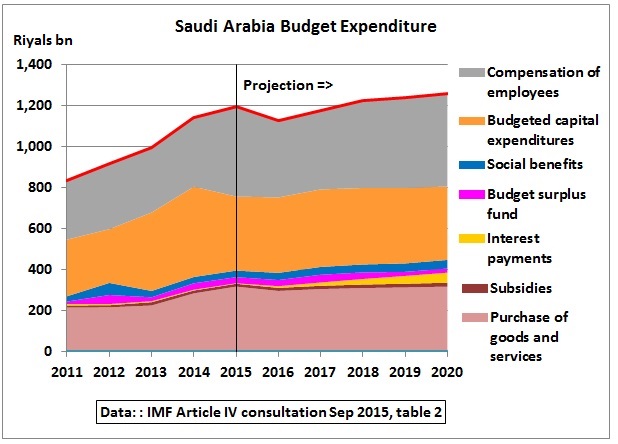
Fig1: Expenditure, Budgetary Central Government Operations
During the period of high oil prices until 2014, expenditure grew by 9-15% pa. In early 2015, King Salman disbursed a bonus of 50 bn Riyal to government employees, contributing to a 30% increase of the annual wage bill. Capital expenditure (transportation, health and education) includes the expansion works at Medina and Mecca.
Budget Balance
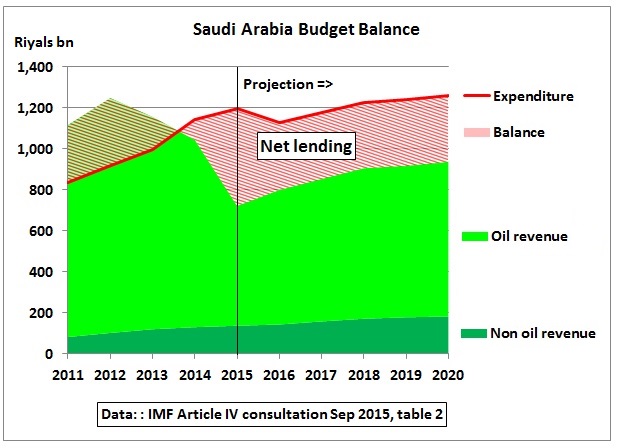
Fig 2: Budget revenue vs expenditure
Oil revenue dropped sharply, starting in 2013 and leading to a negative balance by 2014. It will get worse in 2015. It is clear that the pre 2015 trend cannot continue. The IMF proposes a budget adjustment scenario (ii, Fig 7) by initially reducing expenditure in 2016 and then increasing it moderately by 4% and later 1%. Oil revenue is assumed to grow along a recovery of oil prices. 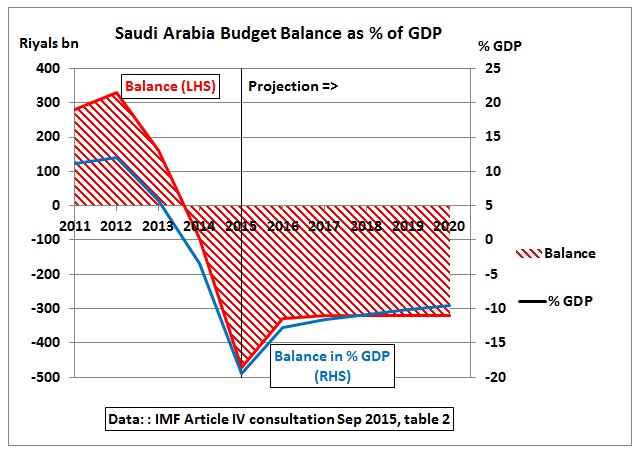
Fig 3: Budget balance as % of GDP
In Fig 3, we take the balance from Fig 2 and add a curve (blue) as percentage of GDP. In 2015, the deficit reaches 20% of GDP. For comparison: commodity dependent Australia had a budget deficit of -2.6% of GDP in 2014/15, the US estimate for 2015 is -2.7%.
Oil price assumptions
The underlying oil prices have been taken from the World Economic Outlook (WEO), assumed as follows: 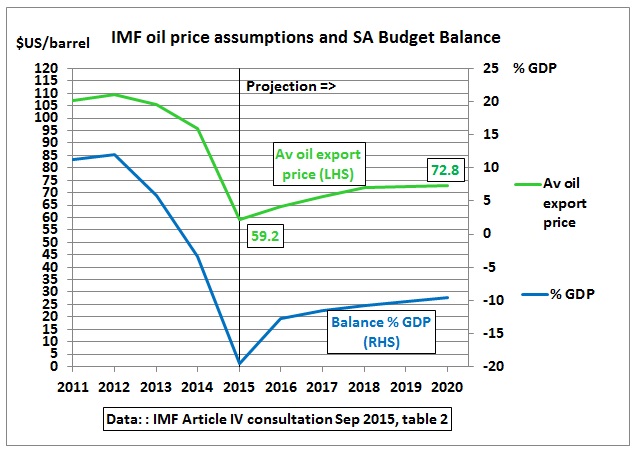
Fig 4: Oil price assumptions and Saudi budget balance
The IMF’s latest World Economic Outlook available at the time of the publication of the Article IV consultation was its July 2015 update:
|
9/7/2015 Oil Price Rebound Oil prices have rebounded more than expected in the second quarter of 2015, reflecting higher demand and expectations that oil production growth in the United States will slow faster than previously forecast. Nevertheless, the average annual oil price expected for 2015—US$59 a barrel—is in line with the oil price assumption in the April 2015 WEO, with a somewhat smaller increase forecast for 2016 and beyond, as global oil supply is running well above 2014 levels and global oil inventories are still rising. The reduction in oil investment may, however, lead to a somewhat weaker boost to activity in North America from lower oil prices than expected earlier. http://www.imf.org/external/pubs/ft/weo/2015/update/02/
|
This July 2015 update in turn was based on the WEO April 2015 as shown in the graph below: 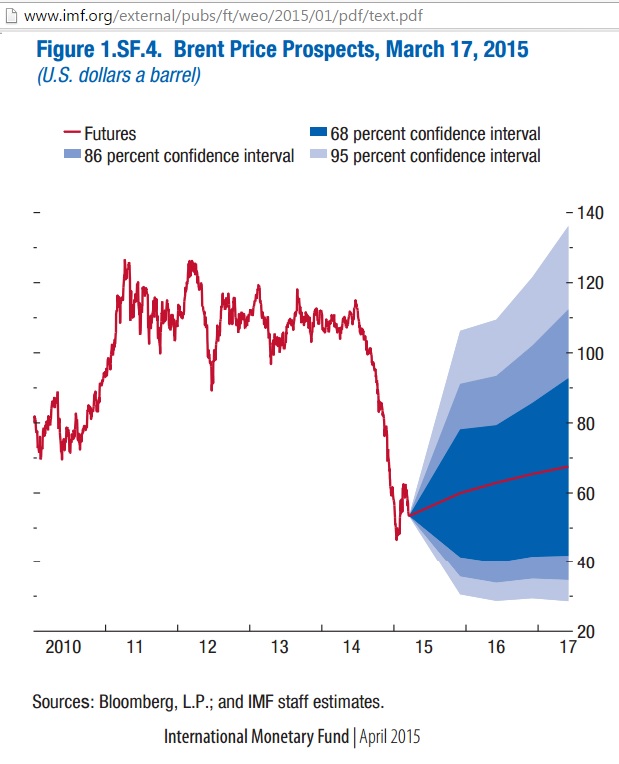
Fig 5: IMF Oil price scenarios in March 2015
http://www.imf.org/external/pubs/ft/weo/2015/01/pdf/text.pdf
The graph shows a huge variability in oil price assumptions for just the next 2 years.
Fiscal Break-even oil price
We have in every year 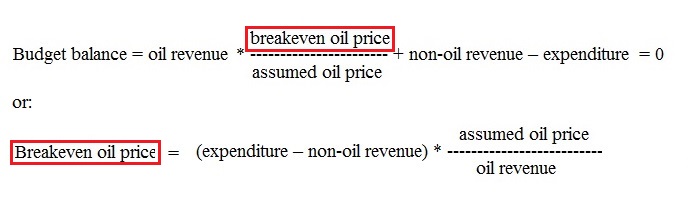 Whereby the oil revenue has been calculated on the basis of assumed oil production, oil exports and oil prices. Apart from these factors, the breakeven oil price mainly depends on expenditure and non-oil revenue.
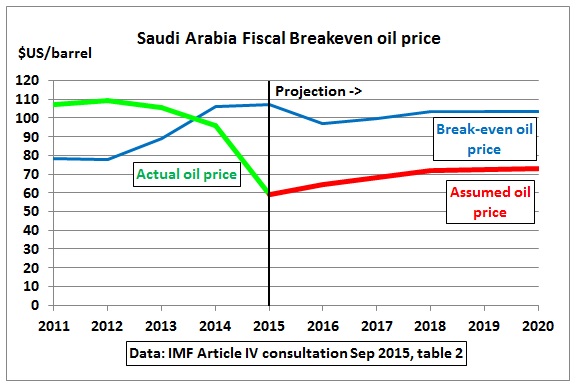
Fig 6: Fiscal breakeven oil price
We see that the fiscal breakeven oil price is around $US100 per barrel.
Fiscal scenarios and net financial wealth
The blue curves from Fig 3 and 4 can be found in the following IMF graph (bottom left panel) 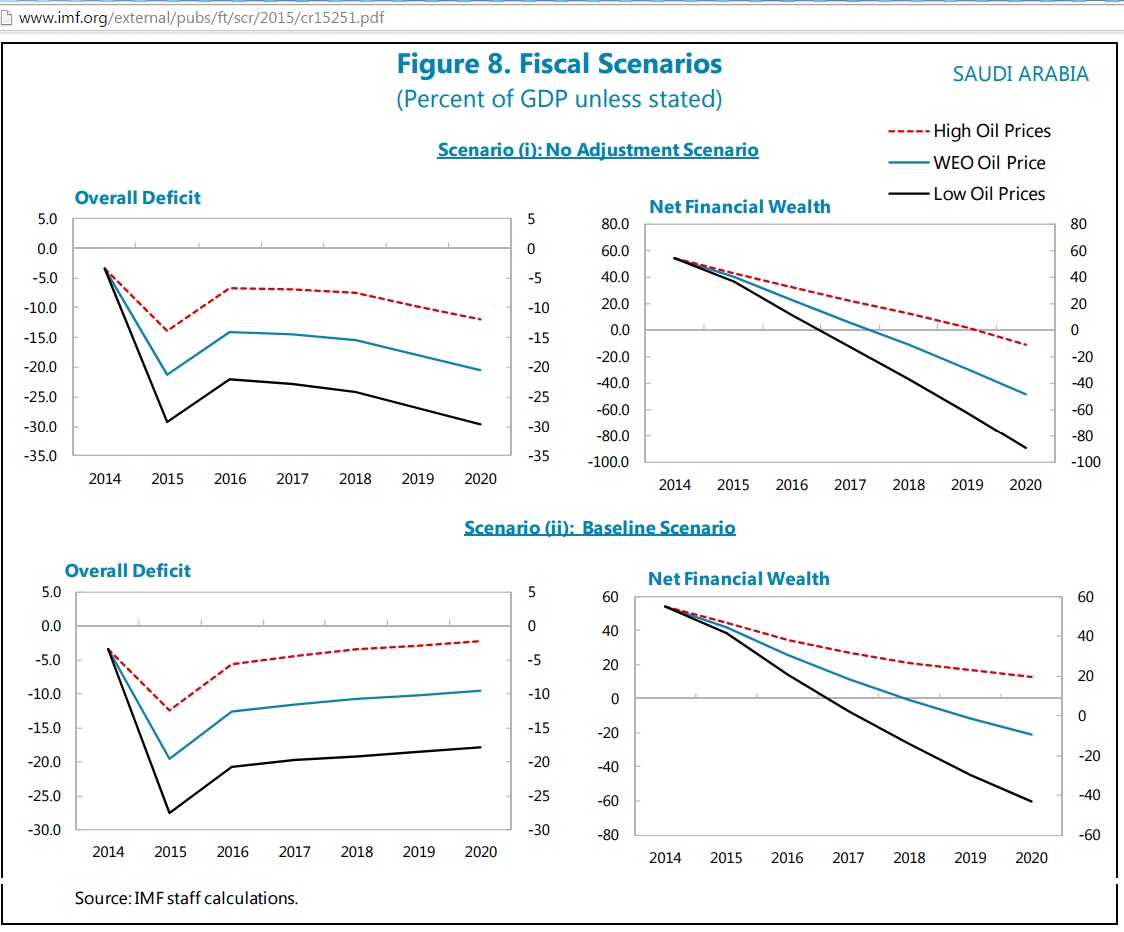
Fig 7 Fiscal scenarios for a range of oil prices
The top panels show the business as usual scenario, the bottom panels the budget adjustment scenario. High and low oil prices mean +- 25% from the WEO assumption. Financial wealth is defined as SAMA government deposits in the banking system less gross public debt. We can see in the bottom right panel that the baseline scenario (blue curve) crosses the zero wealth line in 2018. Let’s have a look at how this comes about: 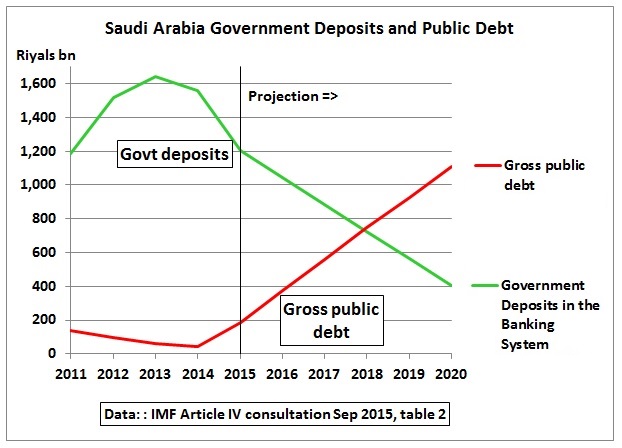
Fig 8: Government deposits and public debt
Government deposits already peaked in 2013 and are now estimated to steadily decline. Debt was very low in 2014 but is now increasing rapidly. The cross-over point is indeed in 2018. The net-wealth is the addition of these 2 curves.
External balance
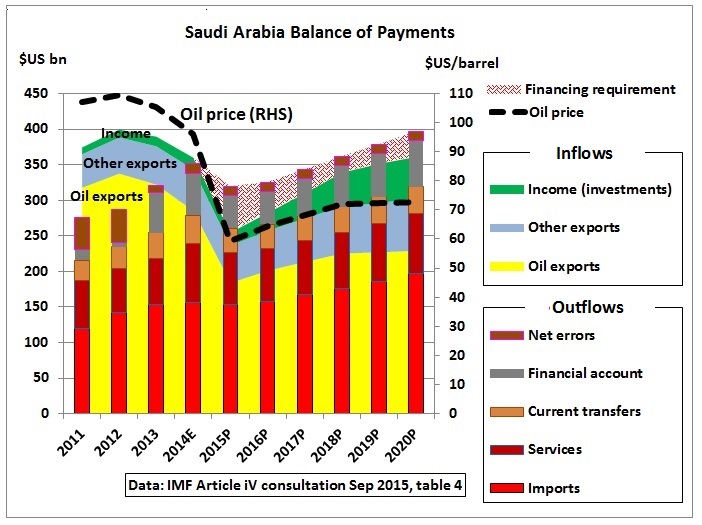
Fig 9: Balance of payments
The inflows are shown as areas and the outflows as columns. The main inflow is from exporting oil. After the oil price drop outflows exceed inflows. Around 80% of the value of oil exports is used for imports.
Breakeven oil price (external balance)
There is another type of breakeven oil price, which balances the current account. This condition can be formulated in following equation: 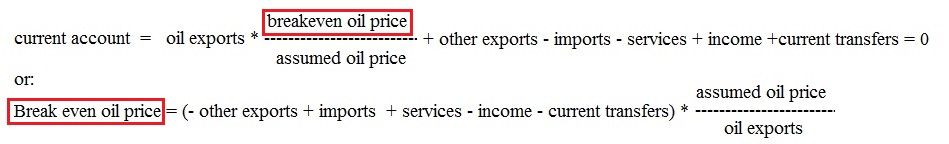
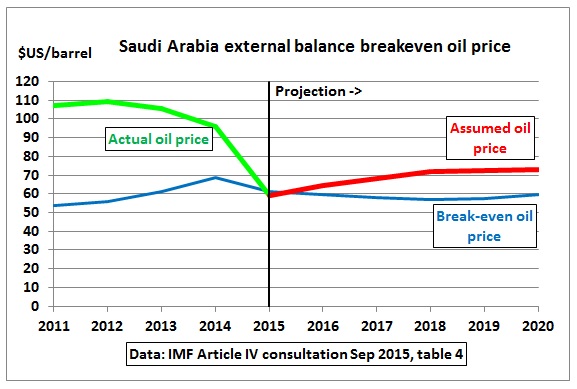
Fig 10: Breakeven oil price to bring current account to zero
We see that this breakeven oil price is much lower, at around $60 a barrel. The IMF report contains the following informative graph, bringing together both types of breakeven oil prices, for Saudi Arabia and neighbouring countries: 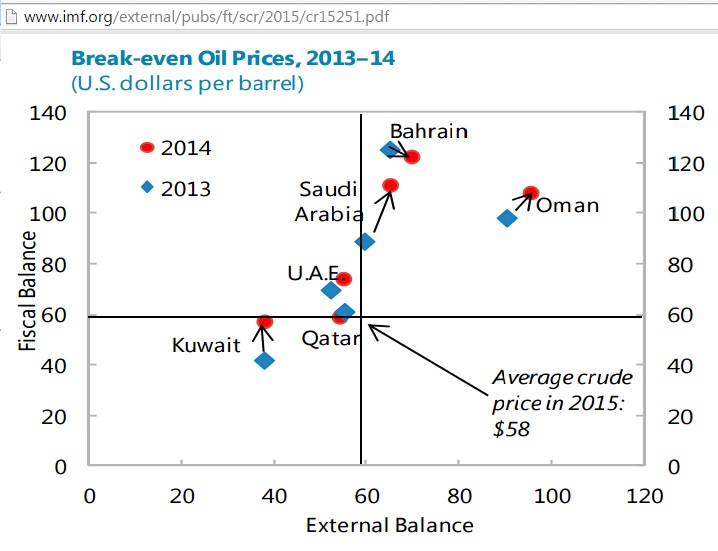
Fig 11: Breakeven oil prices for GCC countries
Net Foreign Assets
The financing requirements from Fig 9 reduce the net foreign assets of SAMA (Saudi Arabia Monetary Authority) as shown in this graph: 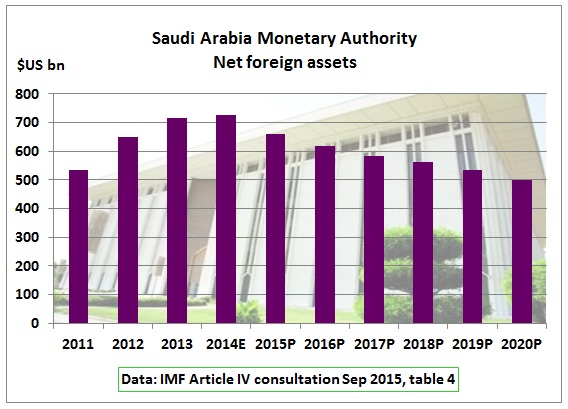
Fig 12: Saudi net foreign assets
Revised oil prices (October 2015)
Shortly after the publication of the Article IV consultation report a new World Economic Outlook was released with oil prices revised downwards, meaning the earlier report may have been too optimistic. WEO IMF Oct 2015 Oil prices are projected to increase gradually over the forecast horizon, from an average of $52 a barrel in 2015 to about $55 a barrel in 2017. 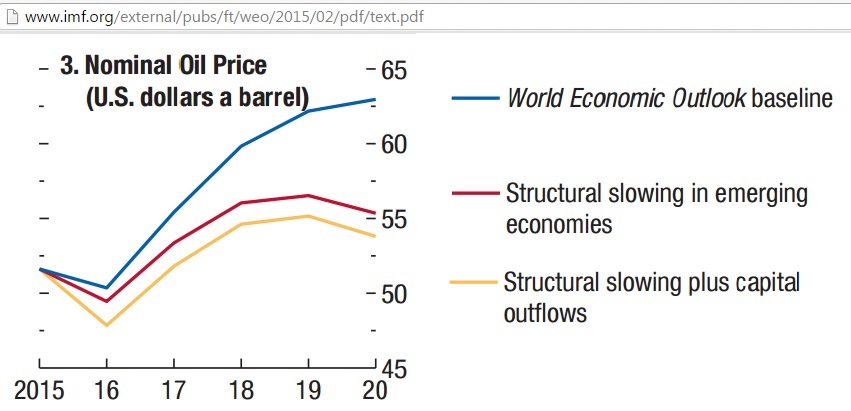
Fig 13: Nominal oil prices assumed by IMF in October 2015
http://www.imf.org/external/pubs/ft/weo/2015/02/pdf/text.pdf
Oil production and Export Assumptions
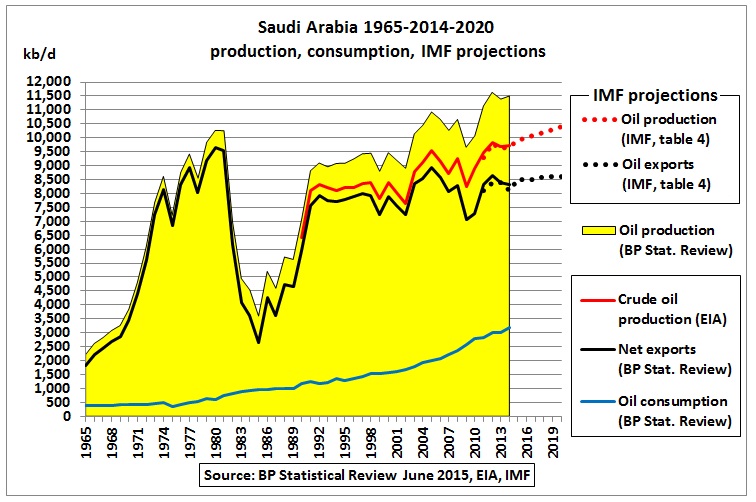
Fig 14: Saudi oil production and exports, actual and IMF assumptions
The IMF’s “oil production” in table 4 is crude oil, approximately in line with data from the EIA (International Energy Statistics), assumed to grow by another 700 kb/d to 10.4 mb/d by 2020. The IMF’s “oil exports” are similar to oil production (crude + NGLs) minus oil consumption from the BP Statistical Review. Exports are not assumed to increase. This implies that domestic consumption will increase by 700 kb/d over the next 5 years. Therefore, if the assumed production increase does not materialise, exports and therefore revenue will be lower than assumed
Conclusion
There are downside risks to the projections in the IMF Article IV report (September 2015). If oil prices remain lower than assumed and exports drop, the fiscal adjustment scenario would require to reduce expenditure further which will not be popular and may lead to domestic problems. Alternatively, the Saudi government would have to borrow more or draw additional funds from its foreign currency reserves. It is claimed that Saudi oil is geologically cheap to produce. What is clear is that it comes with a hidden price tag in the Saudi budget. The number on it is triple digit (Jeff Rubin) which is not good for an oil-dependent global economy as we have learned in 2011-2014. The only logical conclusion is that we have to make our economies less dependent on oil, as fast as possible.