In part 1 of a series of articles on the impact of US tight (shale) oil we examine the impact on US oil consumption.
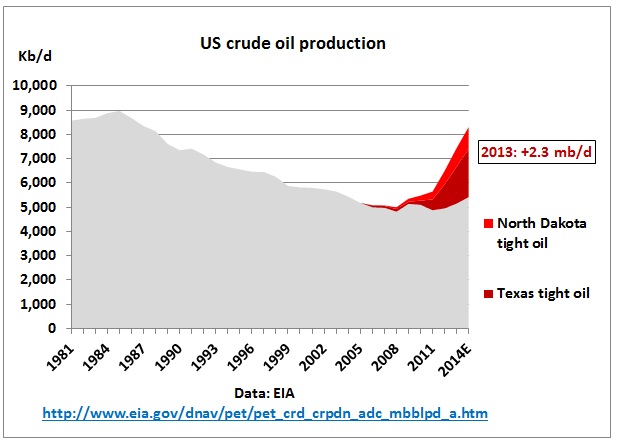
Fig 1: US crude oil production with tight oil from Texas and North Dakota
Data from: http://www.eia.gov/dnav/pet/pet_crd_crpdn_adc_mbbl_a.htm
In 2013, an additional 2.3 mb/d of tight oil was produced from wells in Texas (1.5 mb/d) and North Dakota (0.8 mb/d). Note that these data are preliminary estimates.
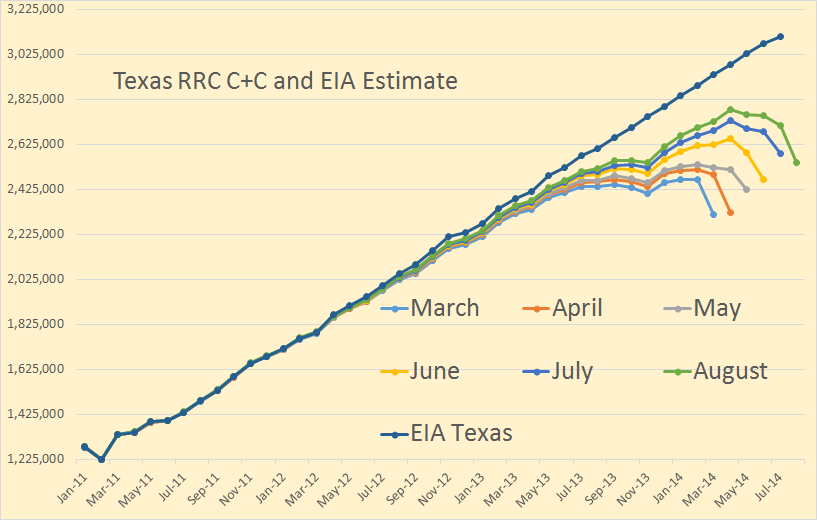
Fig 2: Data from the Texas Rail Road Commission in barrels/day
Graph from: http://peakoilbarrel.com/texas-rrc-oil-gas-report-august-data/
The blue straight line is from the EIA http://www.eia.gov/dnav/pet/hist/LeafHandler.ashx?n=PET&s=MCRFPTX2&f=M
The other lines present the monthly updates of the Texas RRC. We see it takes almost 2 years until numbers stabilize. Around 1.1 mb/d is from conventional oil.
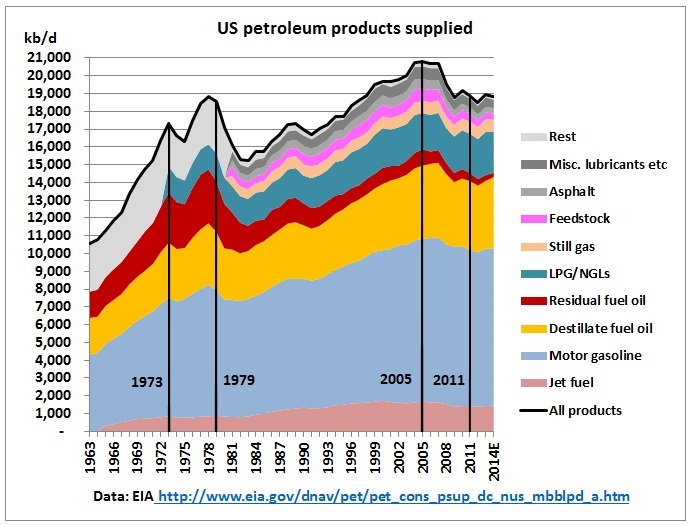
Let’s have a look at US consumption by fuel
 Fig 2: US annual petroleum consumption 1963-2014E
Data from: http://www.eia.gov/dnav/pet/pet_cons_psup_dc_nus_mbblpd_a.htm
This graph shows: consumption growth was stopped in the 1st oil crisis 1973 (successful OPEC embargo after US peak oil in 1970) and the 2nd oil crisis in 1979 (peak oil in Iran) which caused a recession in the 1980s. It took 20 years until consumption was back to end 70s levels. Iraq’s invasion in Kuwait and Desert Storm resulted in a kink in the curve. The next limit was reached in 2005, when global crude production started to peak. A US consumption peak was reached at 20.7 mb/d in 2007. Let’s zoom into the last years:
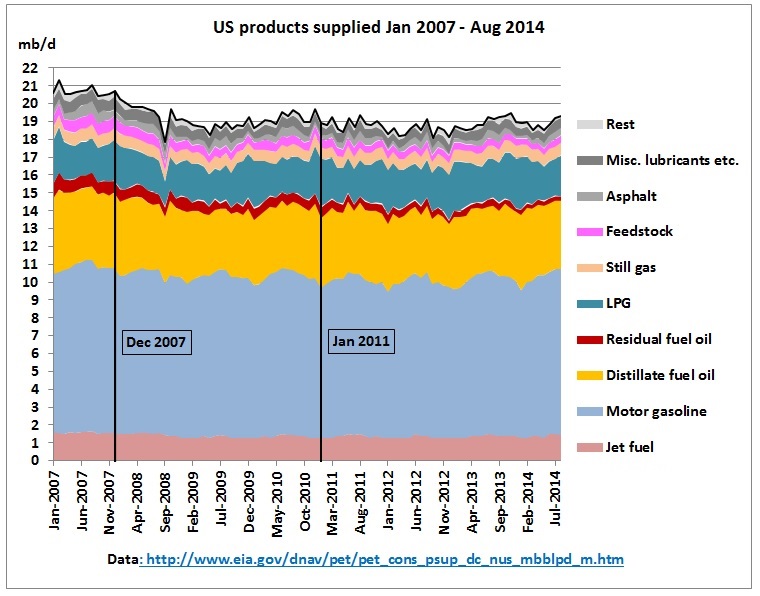
Fig 3: US monthly petroleum consumption Jan 2007 – Aug 2014
Data from: http://www.eia.gov/dnav/pet/pet_cons_psup_dc_nus_mbblpd_m.htm
The recession which started end 2007 and the following financial crisis brought consumption down by around 2 mb/d over 2 years. Since 2009, demand meandered around 18.8 mb/d, with a standard deviation of 360 kb/d. Motor gasoline shows the typical seasonal variation.
In 2011 tight oil production started to skyrocket but US consumption did not increase. Apparently tight oil production did not grow the whole US economy sufficiently enough to increase overall fuel consumption.
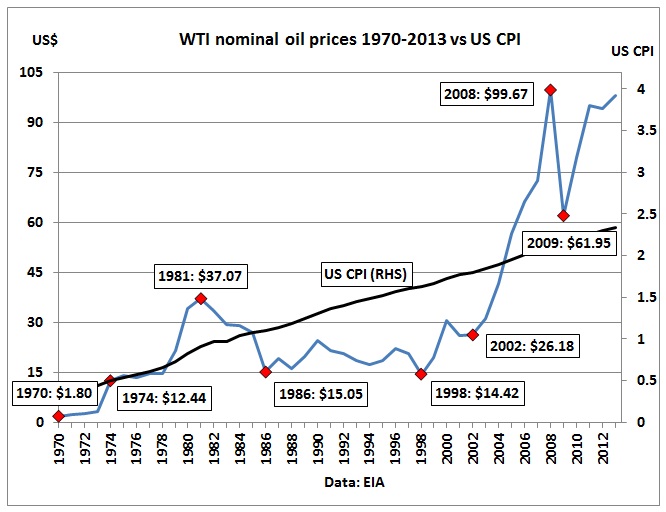
Fig 4: WTI oil prices versus US CPI
Fig 4 shows the oil price historical context of Fig 2 and 3. Oil prices went up 7-fold between the US peak year of 1970 and 1974 when the OPEC embargo was lifted. Oil prices again increased 2.5 fold during and after the Iranian oil peak. This increase was undone over 5 years by a deep recession and a drop in oil consumption by 20% in 3 years. When starting a CPI line at the 1974 oil price one would arrive at a hypothetical oil price of around $60 in 2013.
2nd versus 3rd oil crisis
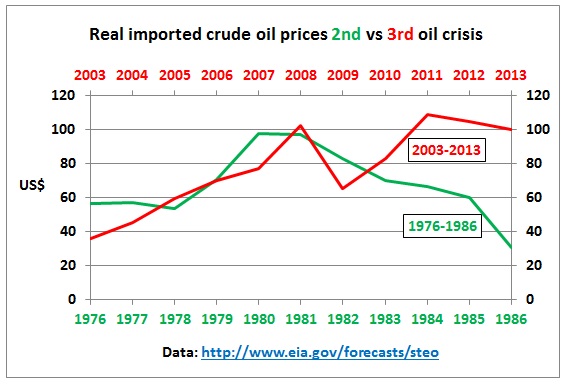 Fig 4: Comparison real oil prices 2nd and 3rd oil crisis
The public is still not aware that we are in the 3rd oil crisis which commenced in 2005 when crude oil started to peak. The above graph overlays real oil prices between 1976-1986 (green, lower horizontal axis) and 2003-2013 (red, upper horizontal axis). These periods have been chosen so that the price peaks in 1981 and 2008 align. The 2nd oil crisis starts with elevated prices coming from the 1st oil crisis in 1973. When comparing the 2nd and 3rd oil crisis we see that oil prices after the 2008 peak went down faster but then went up again and stayed high while after the 2nd crisis oil prices continued to drop and ended up lower in 1986 than in 1976.
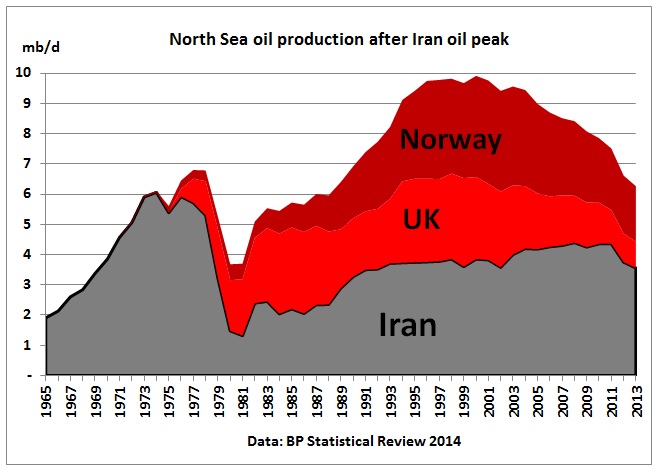
Fig 5 North Sea production stacked on Iran
The 2nd oil crisis was only “temporary” because there was enough oil elsewhere, for example the North Sea – which started up just as this crisis evolved. By 1986, the North Sea had added 3.6 mb/d thereby replacing almost all oil lost in Iran. By 1997, North Sea oil had increased by another 2.4 mb/d, peaking at 6 mb/d. On a net basis, the North Sea added around 4mb/d until it peaked in 2000, setting the scene for the 3rd crisis 5 years later.
US shale oil was developed 3 times faster than the North Sea but it came 5 years too late and is too expensive to play the same role as the North Sea in the 80s and 90s.
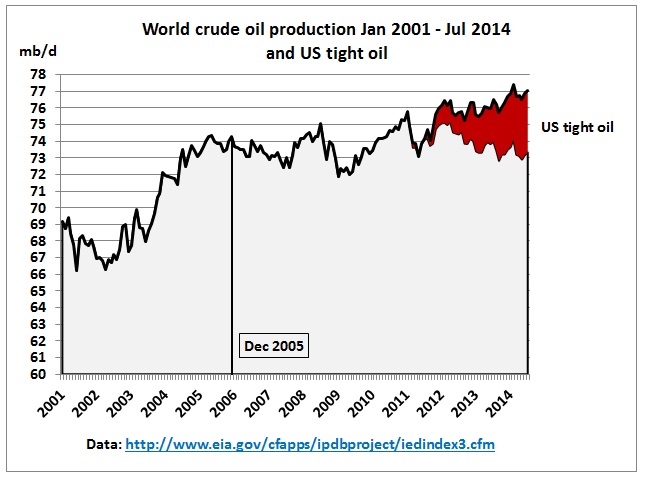
Fig 6 World crude production and US tight oil
Data from: http://www.eia.gov/cfapps/ipdbproject/iedindex3.cfm
Without shale oil crude production would be in decline like between 2005 and 2007.
How about fuel efficiencies?
In its Annual Energy Outlook 2014 The EIA calculated that as a result of demographic changes total vehicle miles travelled (VMT) will still increase at an average annual rate of 0.9% from 2012 to 2040 but that rising fuel economy will more than offset this, with energy consumption by LDVs declining by 70 kb/d pa.
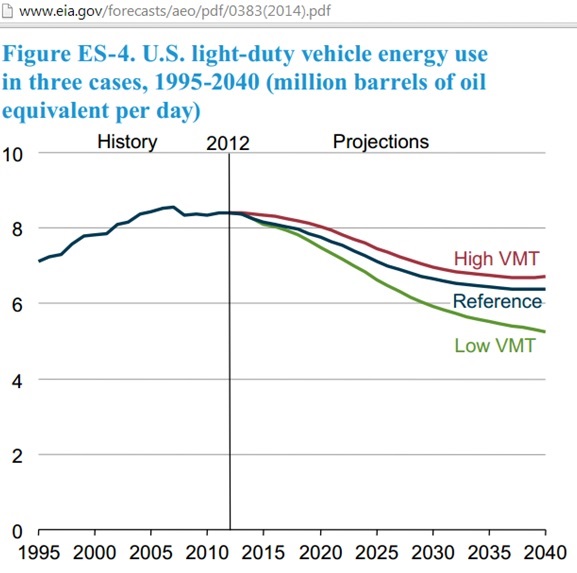
Fig 7: EIA’s assumptions of VMT and associated oil consumption
http://www.eia.gov/forecasts/aeo/pdf/0383(2014).pdf
So in 3 years since 2011 this would be 210 kb/d, much less than the standard deviation. Until 2020 decline in oil consumption as a result of efficiencies will be very modest.
Conclusion
There is no statistical evidence that US oil consumption increased as a result of skyrocketing tight oil production which one would expect in an oil boom. In the next article we’ll look at US oil imports